Escrow Account
Explore what an escrow account is in Canadian real estate, how it protects both parties, and when it's used to hold deposits or other funds.
May 22, 2025
What is an Escrow Account?
An escrow account is a third-party account used to hold funds—such as deposits or property taxes—until specific conditions of a real estate transaction are met.
Why Escrow Accounts Matter in Real Estate
In Canadian real estate, escrow accounts are most commonly used to:
- Hold the buyer’s deposit until closing
- Collect and disburse property taxes or insurance premiums (typically for U.S. mortgages but occasionally used in Canada)
- Secure funds during disputes or conditional agreements
These accounts are managed by neutral third parties like lawyers, notaries, or trust companies. This ensures fairness and legal compliance, protecting both buyers and sellers during the transaction.
For example, the buyer’s deposit is held in trust and only released once all conditions are fulfilled and the deal is finalized.
While not always referred to as 'escrow' in Canadian terminology, the function of holding and safeguarding funds remains the same. These accounts prevent either party from misusing funds or breaching the terms of sale.
Understanding escrow accounts gives buyers and sellers peace of mind and legal protection throughout the closing process.
Example of an Escrow Account in Action
A buyer submits a $25,000 deposit, which is held in a lawyer’s escrow account until the transaction closes two months later.
Key Takeaways
- Holds funds until contract conditions are met.
- Managed by neutral third parties.
- Protects both buyer and seller.
- Ensures secure transfer of funds during closing.
- Especially important for large deposits or disputes.
Related Terms
- Escrow
- Deposit
- Trust Account
- Lawyer Fees
- Closing Process
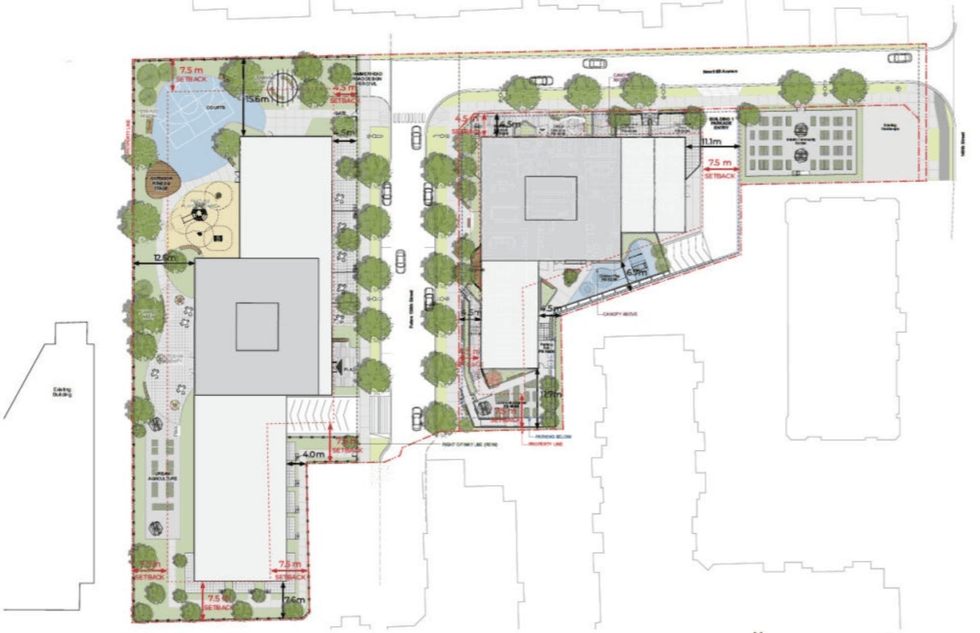
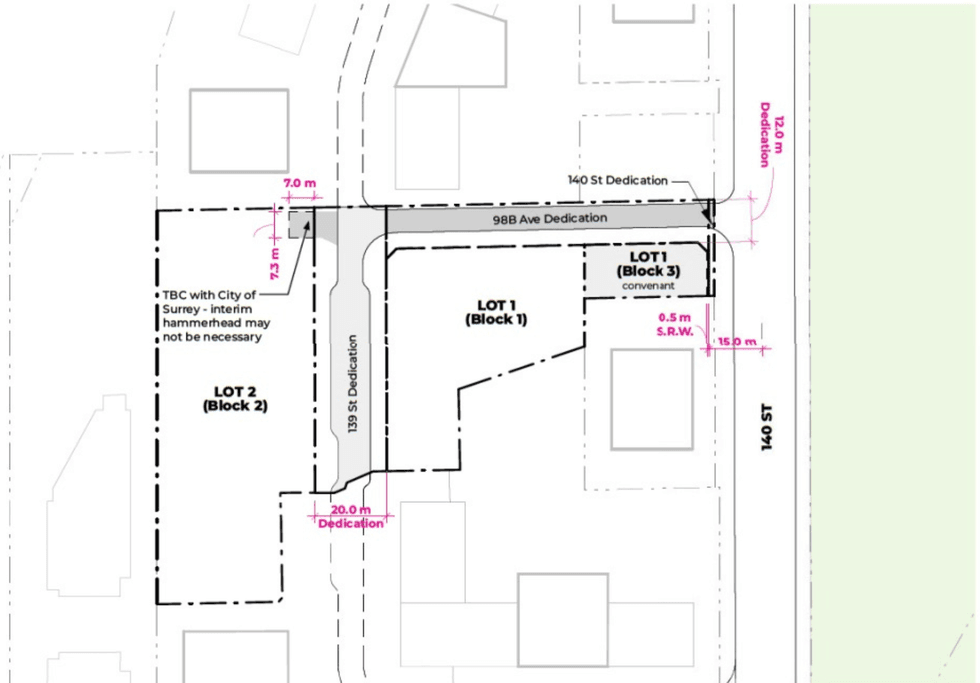 9883 140 Street and the proposed road dedications. (WW+P Architects, Entre Nous Femmes Housing Society)
 The
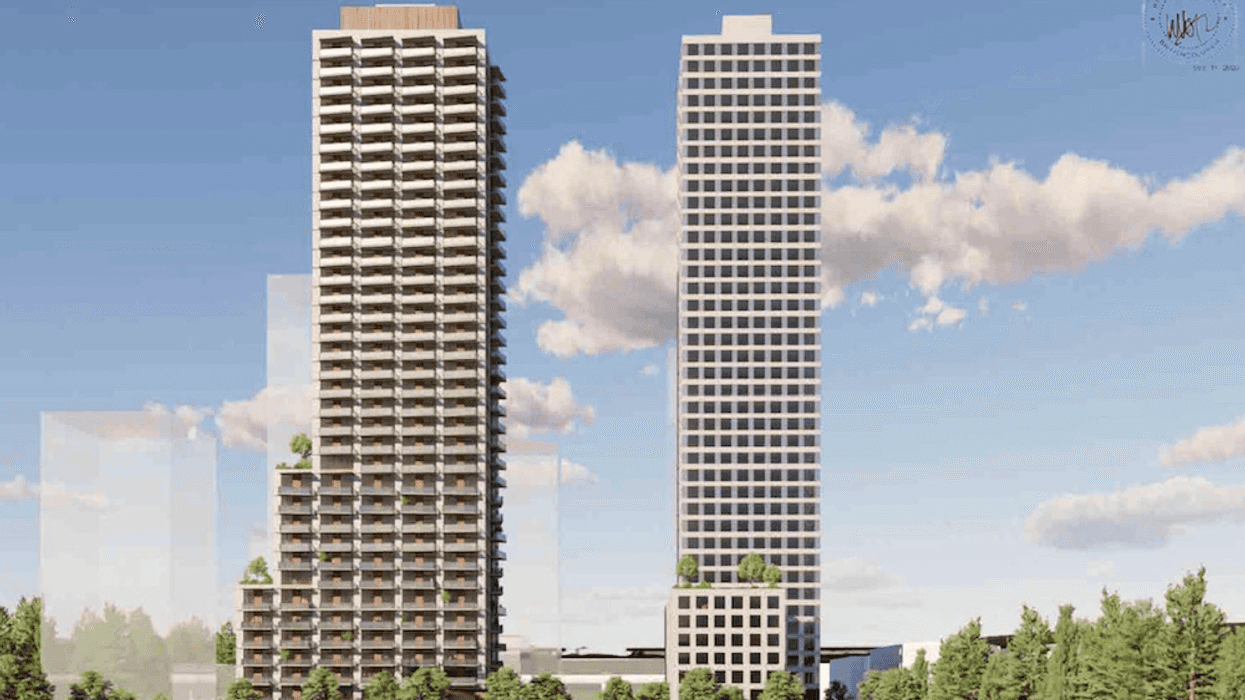
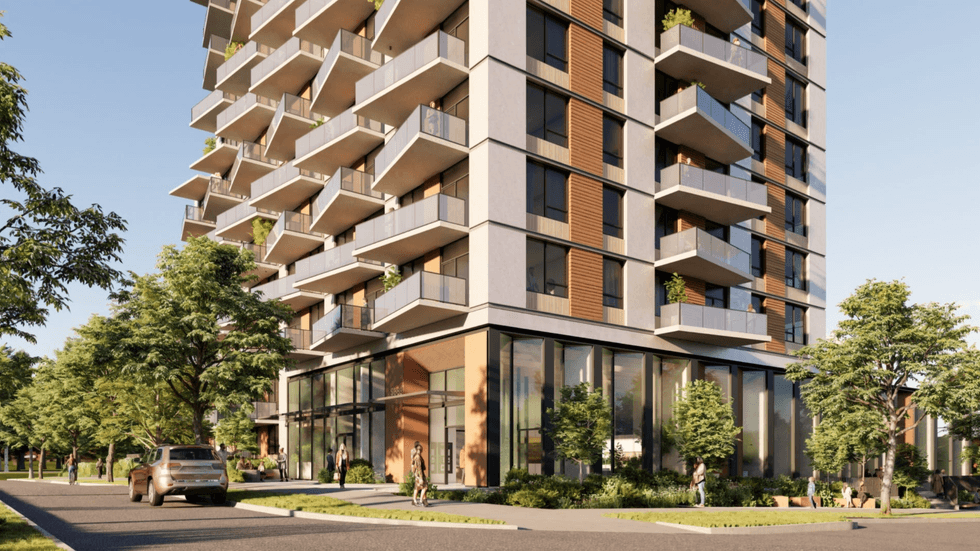 One of the towers proposed for 9883 140 Street. (Entres Nous Femmes Housing Society)




 Canadian respondents were more likely to expect an undersupply of development/redevelopment equity capital (63%) than debt capital (46%) in 2027. These are survey expectations, not measured financing volumes. Source: PwC and ULI, Emerging Trends in Real Estate 2027, pp. 136–137. Original chart.
 Toronto census metropolitan area housing starts fell from 37,718 units in 2024 to 26,087 in 2025, a 30.8% decline (rounded to 31%). Starts measure construction begun, not completed homes. Source: CMHC, as cited in PwC and ULI, Emerging Trends in Real Estate 2027, p. 145. Original chart.




 Illustrative calculation: a $4.5-million value ceiling versus income-based capacity of about $4.25 million at 4%, $3.62 million at 5% and $3.13 million at 6%. Assumes 50-year amortization and 1.15 debt coverage.
 Source: Department of Finance missing-middle backgrounder and Budget 2026 Chapter 3, November 5, 2026. Fiscal-year funding starts are not home-completion dates.
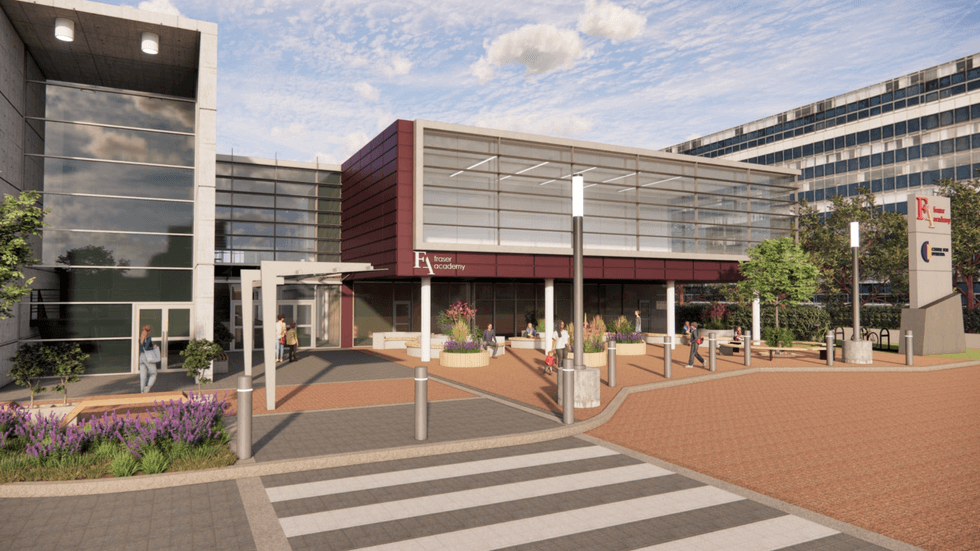 A rendering of Fraser Academy’s new campus. (Fraser Academy)
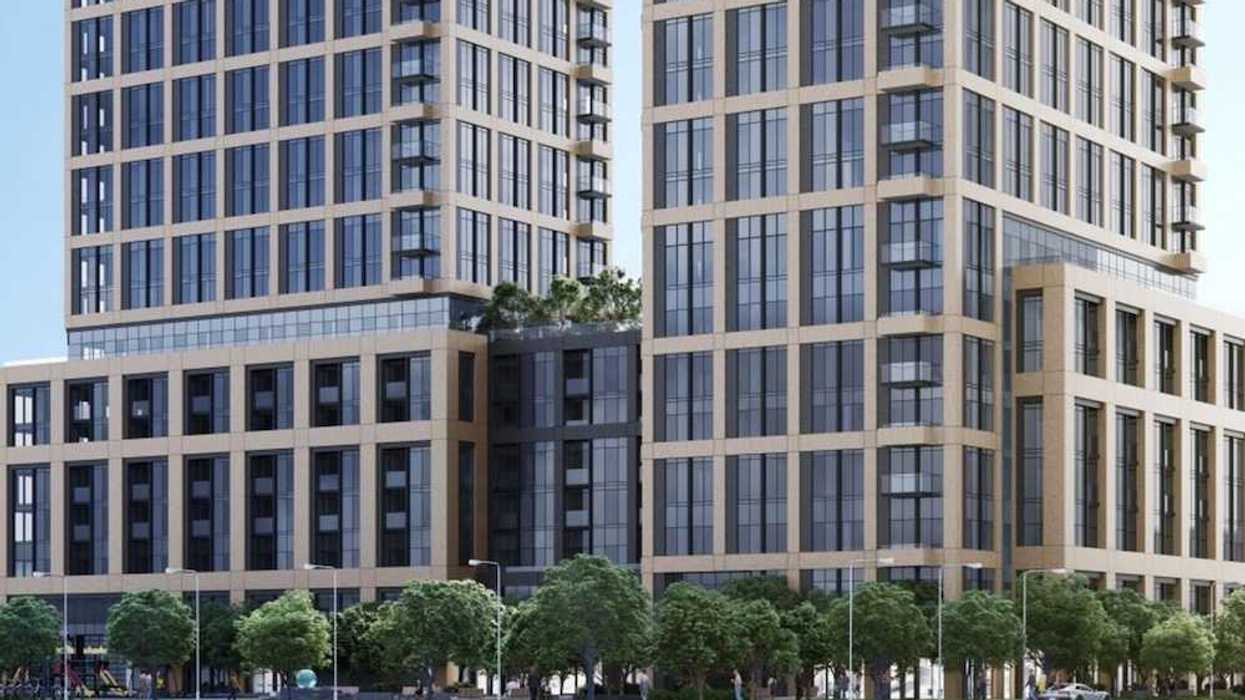
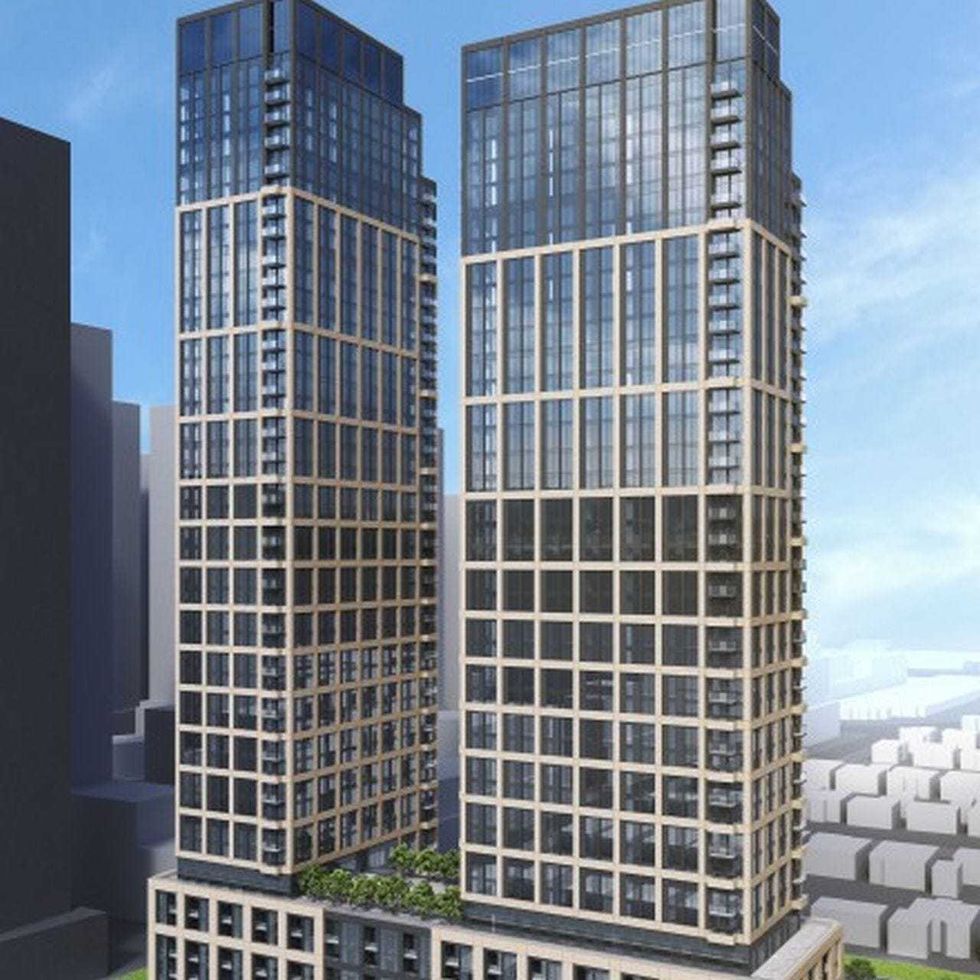 The project planned for 36-48 Steeles Avenue East and 37-49 Highland Park Boulevard in Markham. (Arcadis, Zonix Homes)