Underwriting
May 21, 2025
What is Underwriting?
Underwriting is the process lenders use to assess a borrower’s risk and determine whether to approve a mortgage application.
Why Underwriting Matters in Real Estate
In Canadian real estate, underwriting plays a critical role in securing mortgage financing. Lenders review credit history, income, assets, employment, and the property itself before making a loan decision.
Steps in underwriting may include:- Verifying income and employment
- Reviewing credit score and history
- Assessing debt service ratios
- Appraising the property’s value and condition
Automated underwriting systems may issue quick decisions, while complex applications (e.g. self-employed borrowers) are reviewed manually.
Understanding underwriting helps buyers prepare accurate documents, reduce delays, and improve approval odds.
Example of Underwriting in Action
The lender’s underwriter reviews the buyer’s income, credit, and appraisal to approve the mortgage before closing day.
Key Takeaways
- Evaluates borrower and property risk.
- Required for mortgage approval.
- May be automated or manual.
- Relies on complete documentation.
- Crucial step in the financing process.
Related Terms
- Mortgage Qualification
- Credit Score
- Debt Service Ratios
- Appraisal
- Lender Guidelines
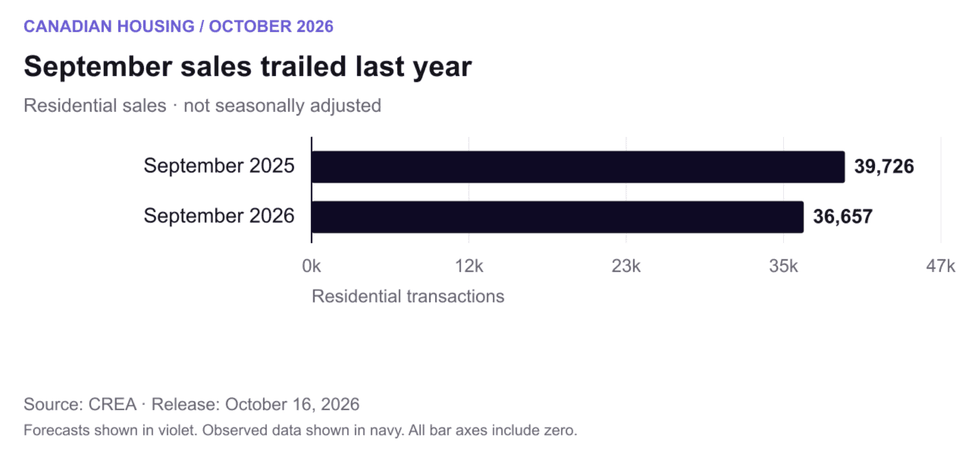 September residential sales, not seasonally adjusted; the annual comparison uses CREA’s revised figures. Chart:
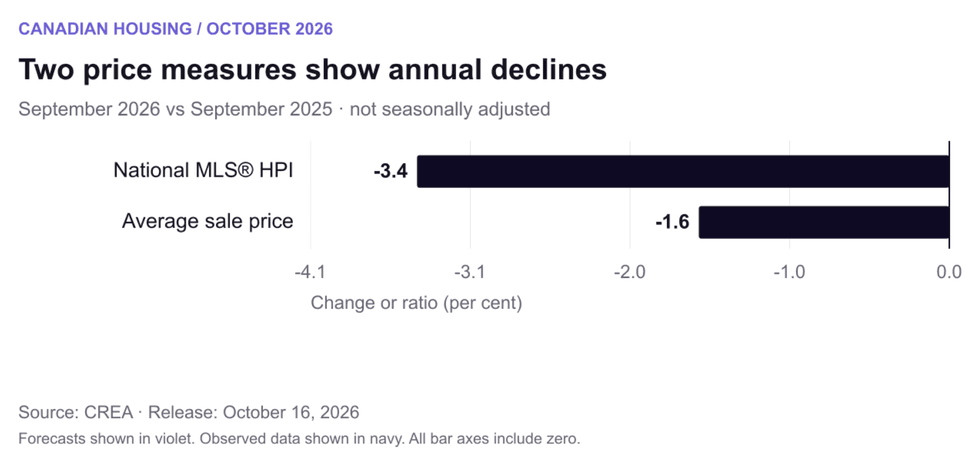 Annual changes in the unadjusted national MLS® HPI and average sale price. The average is affected by the mix of transactions. Chart:
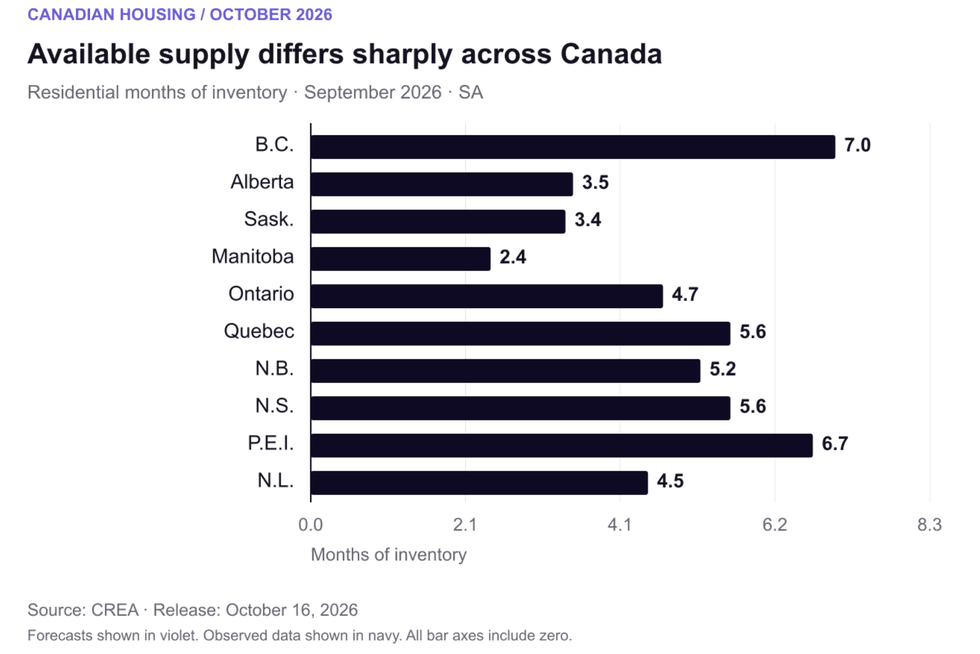 Seasonally adjusted residential months of inventory by province. Local property types can differ substantially. Chart:
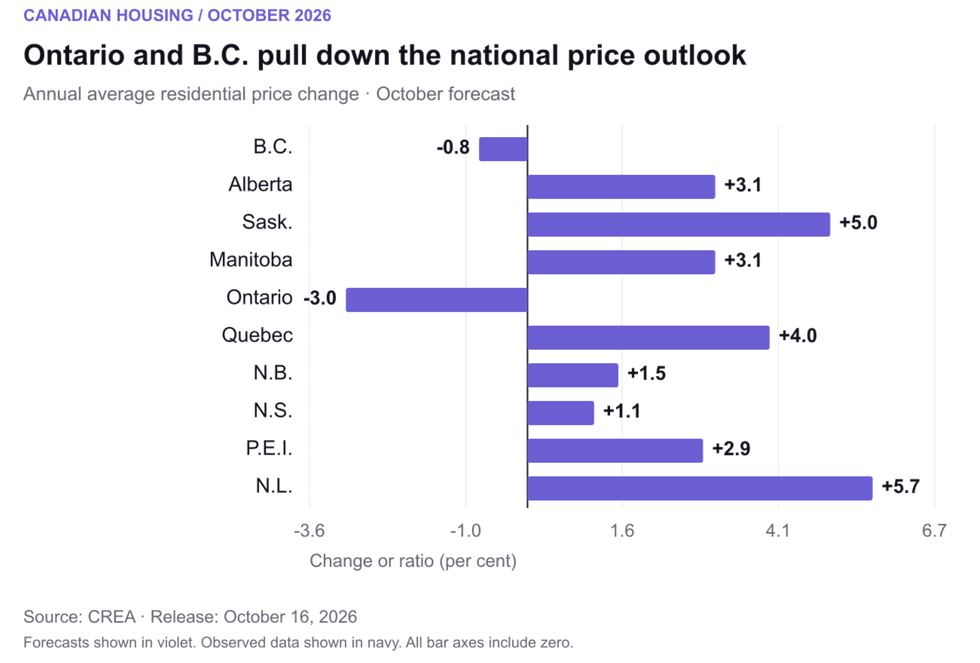 Ontario and B.C. are the two provinces with forecast annual average-price declines in 2026. Chart:
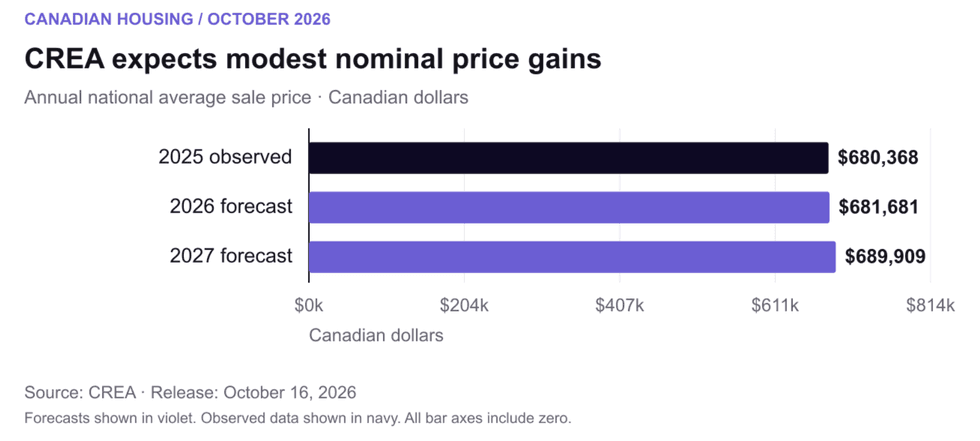 Annual average transaction prices in Canadian dollars. Forecast values are not December price targets. Chart:
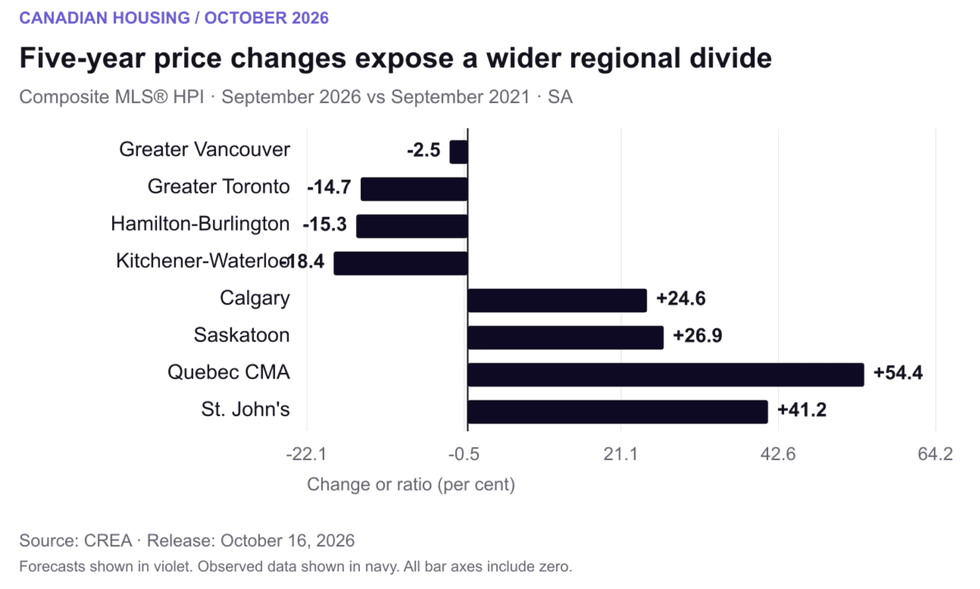 Five-year changes in seasonally adjusted composite MLS® HPI benchmarks, September 2021 to September 2026. Chart: