Underused Housing Tax
The Underused Housing Tax is a federal 1% annual tax on vacant or underused homes owned by non-resident, non-Canadian entities.
September 30, 2025
What is the Underused Housing Tax?
The Underused Housing Tax (UHT) is a federal annual 1% tax on the value of vacant or underused residential property owned by non-resident, non-Canadian individuals or corporations. Certain exemptions apply for Canadian citizens, permanent residents, and qualifying uses of the property.
Why the Underused Housing Tax Matters in Real Estate
The UHT matters in real estate because it aims to address housing supply challenges by discouraging property speculation and foreign ownership of underused homes. It also generates federal revenue and supports broader housing policy goals.
Example of the Underused Housing Tax in Action
A foreign investor owns a vacant condo in Toronto valued at $800,000. Without qualifying exemptions, they must pay $8,000 annually under the Underused Housing Tax.
Key Takeaways
- Federal tax on underused or vacant housing by non-residents.
- Set at 1% of property value annually.
- Aims to discourage speculation and improve supply.
- Exemptions available for citizens, residents, and qualifying uses.
- Applies nationwide, separate from provincial or municipal taxes.
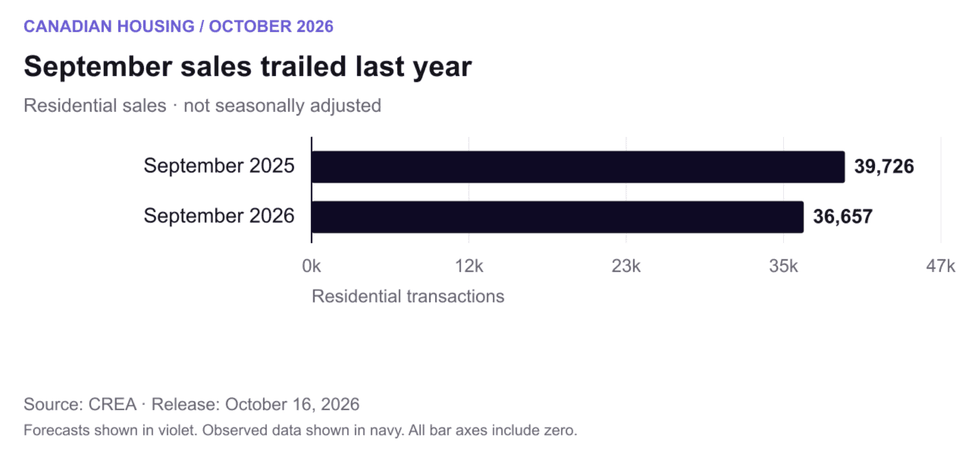 September residential sales, not seasonally adjusted; the annual comparison uses CREA’s revised figures. Chart:
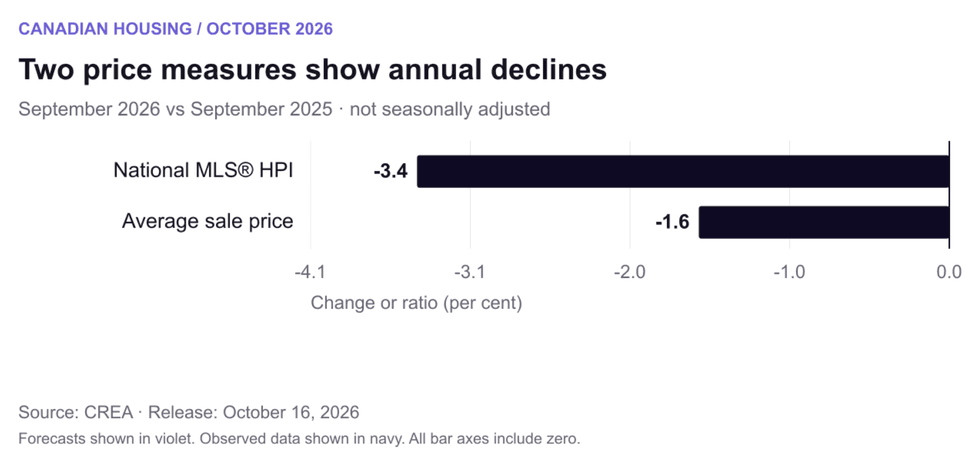 Annual changes in the unadjusted national MLS® HPI and average sale price. The average is affected by the mix of transactions. Chart:
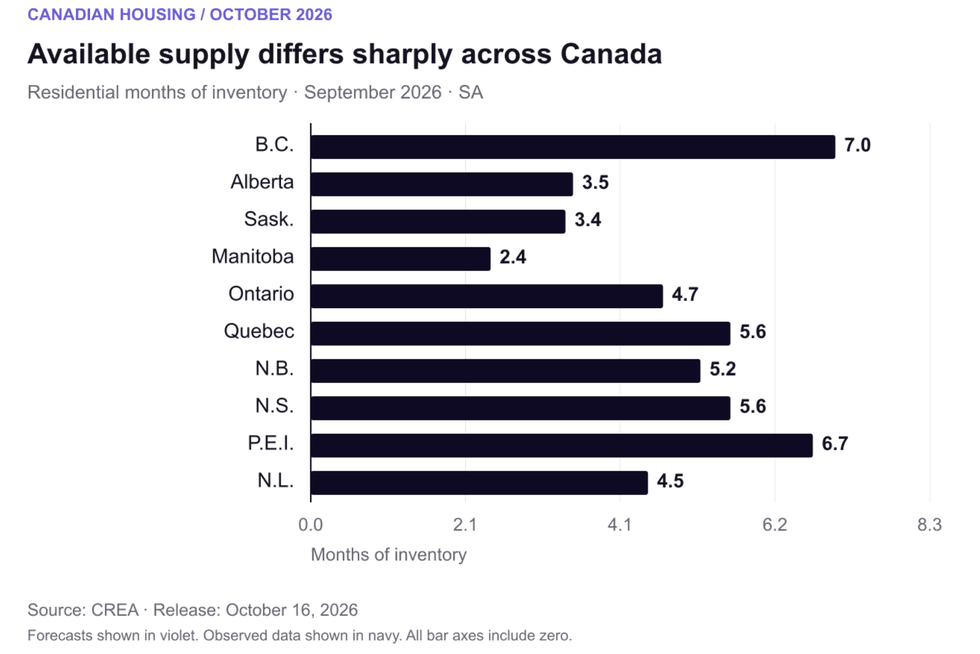 Seasonally adjusted residential months of inventory by province. Local property types can differ substantially. Chart:
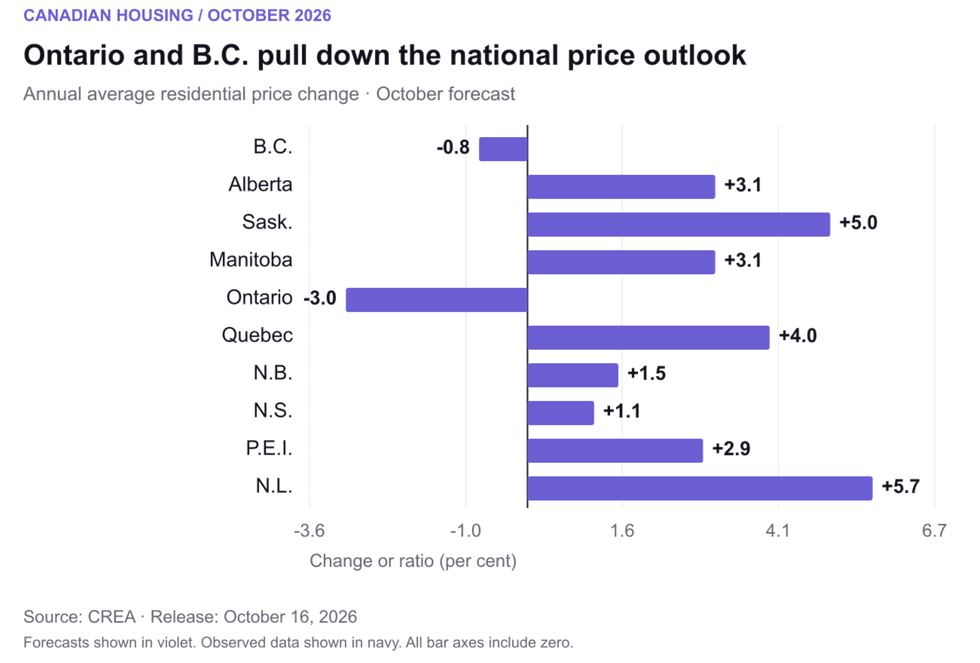 Ontario and B.C. are the two provinces with forecast annual average-price declines in 2026. Chart:
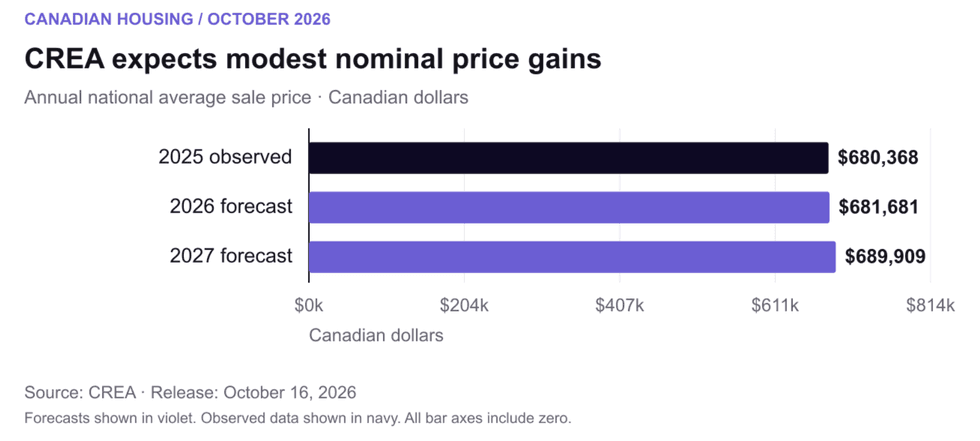 Annual average transaction prices in Canadian dollars. Forecast values are not December price targets. Chart:
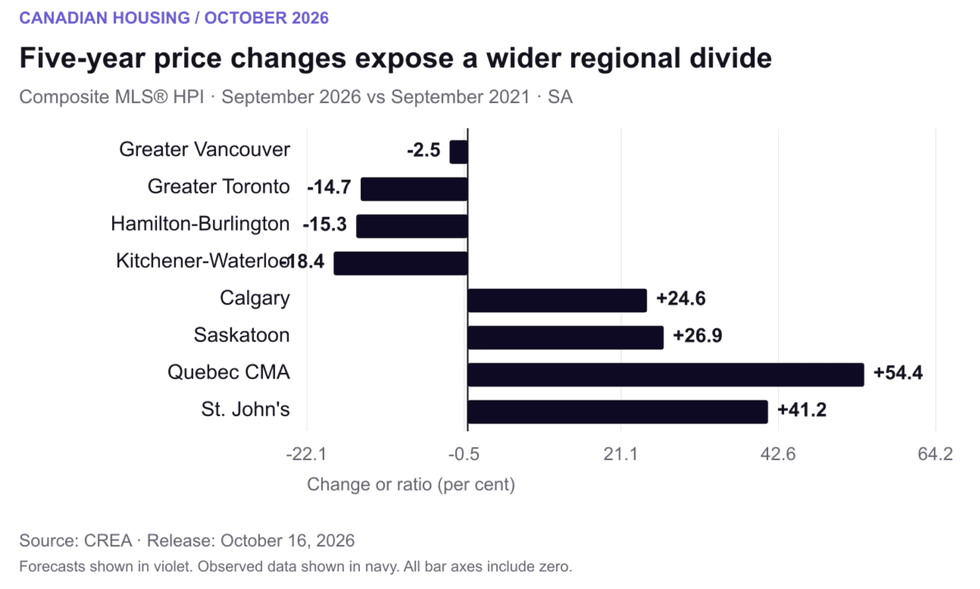 Five-year changes in seasonally adjusted composite MLS® HPI benchmarks, September 2021 to September 2026. Chart: