CMHC Insurance
Learn what CMHC Insurance is, when it's required in Canadian real estate, how much it costs, and how it affects homebuyers with low down payments.
May 22, 2025
What is CMHC Insurance?
CMHC Insurance, also known as mortgage loan insurance, is a government-backed insurance policy provided by the Canada Mortgage and Housing Corporation (CMHC) that protects lenders in case a borrower defaults on a high-ratio mortgage.
Why CMHC Insurance Matters in Real Estate
In Canada, homebuyers who make a down payment of less than 20% are required by law to obtain mortgage loan insurance from CMHC or another approved provider. This insurance protects the lender — not the borrower — by covering losses in the event of mortgage default.
While it doesn’t benefit the buyer directly, CMHC Insurance enables them to purchase a home with as little as 5% down, which is crucial in high-priced housing markets. It helps stabilize the housing market and reduces risk for lenders, making mortgages more accessible to Canadians with lower savings.
The cost of CMHC Insurance is based on a sliding scale tied to the loan-to-value ratio and is typically added to the mortgage principal or paid as a lump sum. Premiums range from 2.8% to 4% of the mortgage amount, depending on the size of the down payment.
Understanding CMHC Insurance is key for budgeting, especially for first-time homebuyers, and for making informed decisions about down payment strategy and overall affordability.
Example of CMHC Insurance
A buyer in Ontario purchases a $500,000 home with a 10% down payment. Since this is less than 20%, they must pay a CMHC Insurance premium of $13,950, which is added to their mortgage.
Key Takeaways
- Required for down payments under 20%.
- Protects the lender in case of borrower default.
- Provided by CMHC and other approved insurers.
- Cost is based on mortgage size and down payment.
- Enables access to homeownership with smaller savings.
Related Terms
- High-Ratio Mortgage
- Loan-to-Value Ratio (LTV)
- Mortgage Default
- Down Payment
- Mortgage Pre-Approval
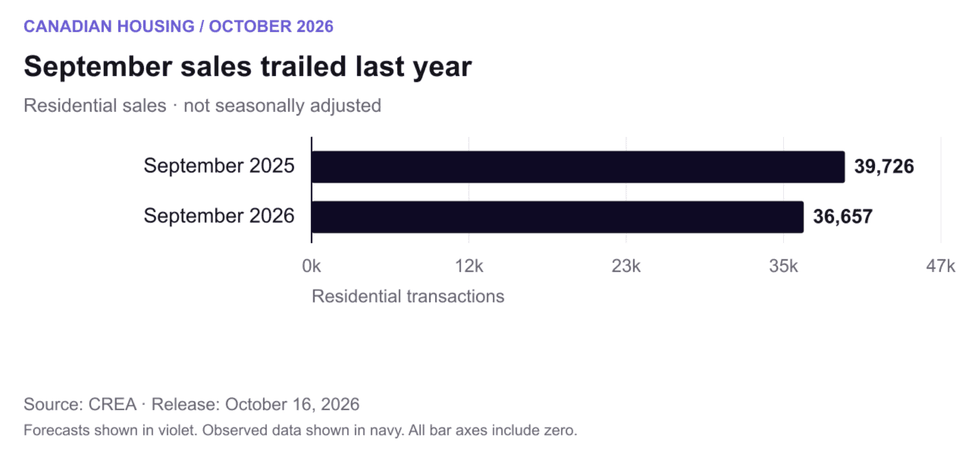 September residential sales, not seasonally adjusted; the annual comparison uses CREA’s revised figures. Chart:
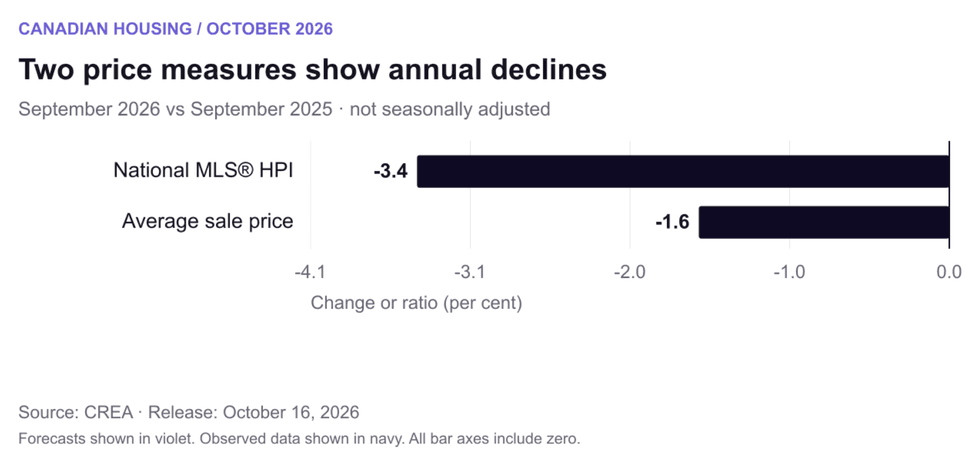 Annual changes in the unadjusted national MLS® HPI and average sale price. The average is affected by the mix of transactions. Chart:
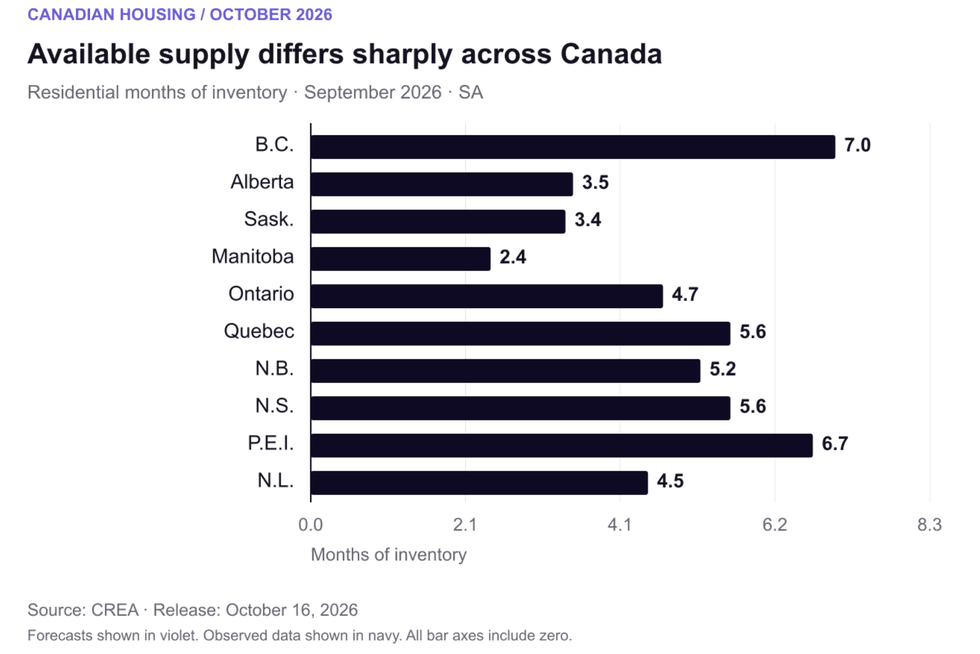 Seasonally adjusted residential months of inventory by province. Local property types can differ substantially. Chart:
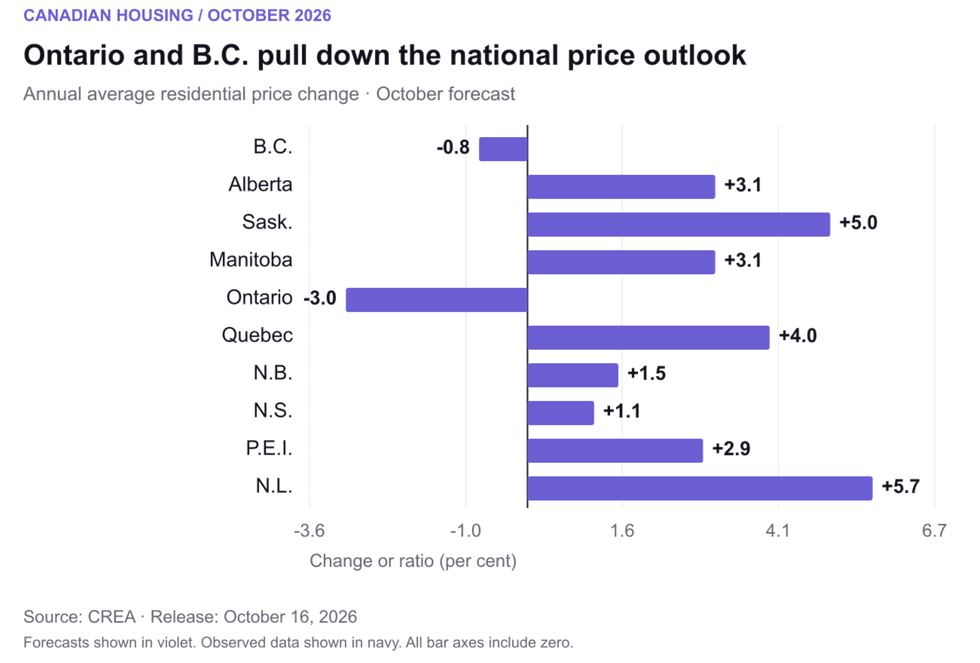 Ontario and B.C. are the two provinces with forecast annual average-price declines in 2026. Chart:
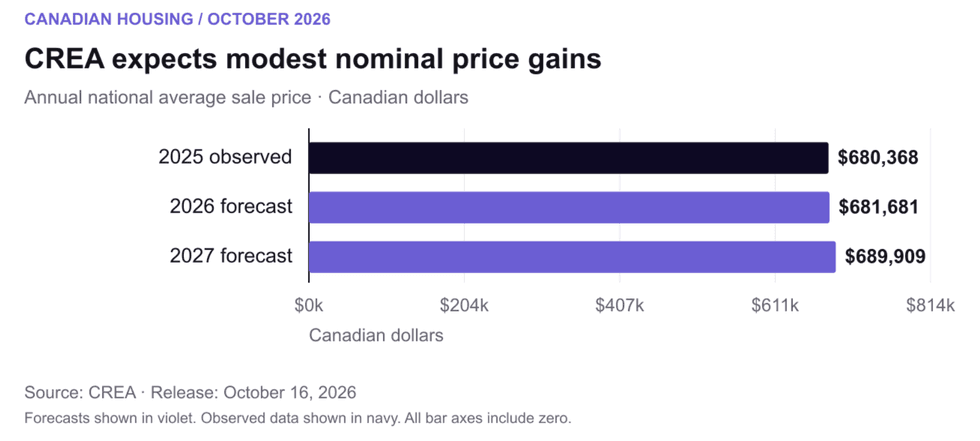 Annual average transaction prices in Canadian dollars. Forecast values are not December price targets. Chart:
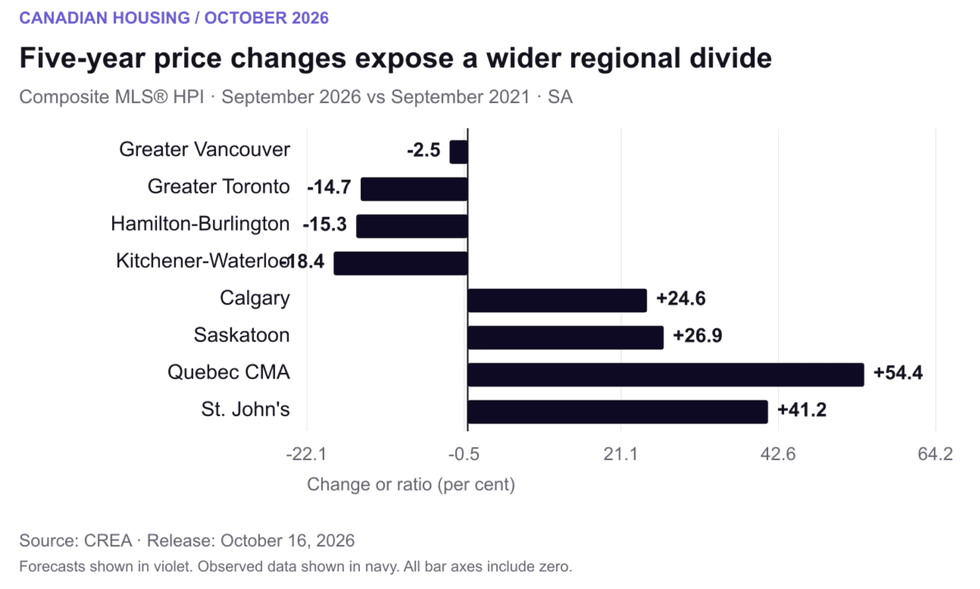 Five-year changes in seasonally adjusted composite MLS® HPI benchmarks, September 2021 to September 2026. Chart: