Mortgage Insurance
Explore mortgage insurance in Canadian real estate — how it works, who it protects, and what homebuyers need to know when putting less than 20% down.
May 22, 2025
What is Mortgage Insurance?
Mortgage insurance protects the lender—not the borrower—in case the borrower defaults on a high-ratio mortgage with a down payment under 20%.
Why Mortgage Broker Fees Matter in Real Estate
In Canada, mortgage insurance is mandatory for insured mortgages. It is typically provided through the Canada Mortgage and Housing Corporation (CMHC), Sagen, or Canada Guaranty.
Key characteristics include:- Required for down payments between 5% and 19.99%
- Premiums are based on the loan-to-value (LTV) ratio
- Cost is often added to the mortgage principal
Although it protects the lender, it enables buyers to enter the housing market with less capital. Premiums are non-refundable and do not reduce mortgage interest.
Understanding mortgage insurance helps buyers plan for total costs and choose between insured and conventional mortgages.
Example of Mortgage Insurance in Action
A buyer with a 10% down payment pays a 3.1% CMHC insurance premium, which is added to their mortgage balance.
Key Takeaways
- Required for down payments under 20%.
- Protects lenders, not borrowers.
- Premium varies with LTV ratio.
- Enables lower entry costs for buyers.
- Offered through approved insurers.
Related Terms
- CMHC Insurance
- Loan-to-Value Ratio (LTV)
- Down Payment
- Government Incentive
- Pre-Approval
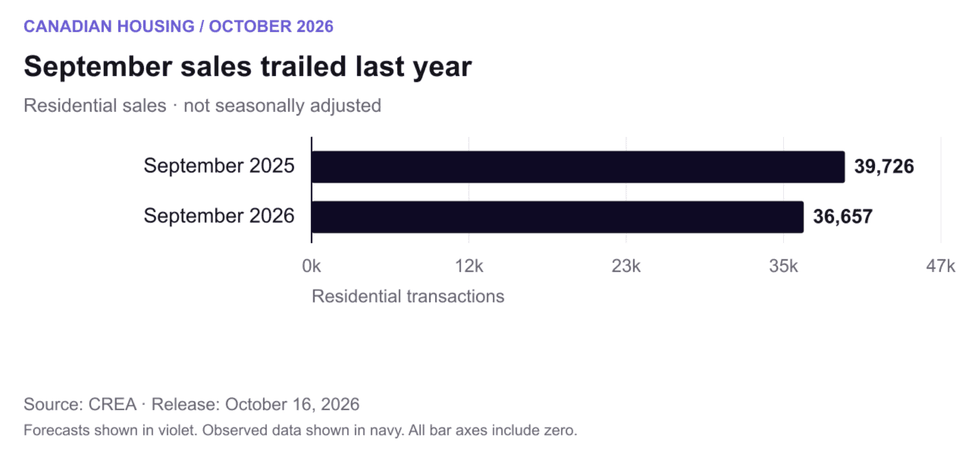 September residential sales, not seasonally adjusted; the annual comparison uses CREA’s revised figures. Chart:
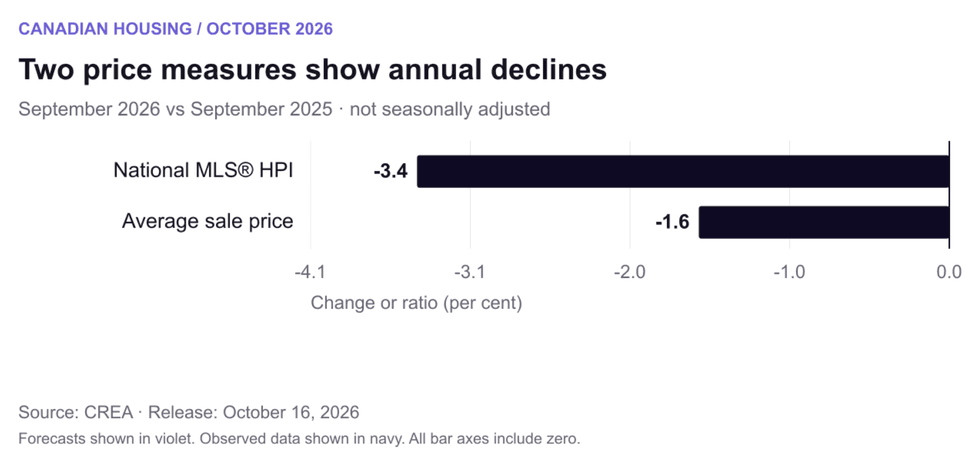 Annual changes in the unadjusted national MLS® HPI and average sale price. The average is affected by the mix of transactions. Chart:
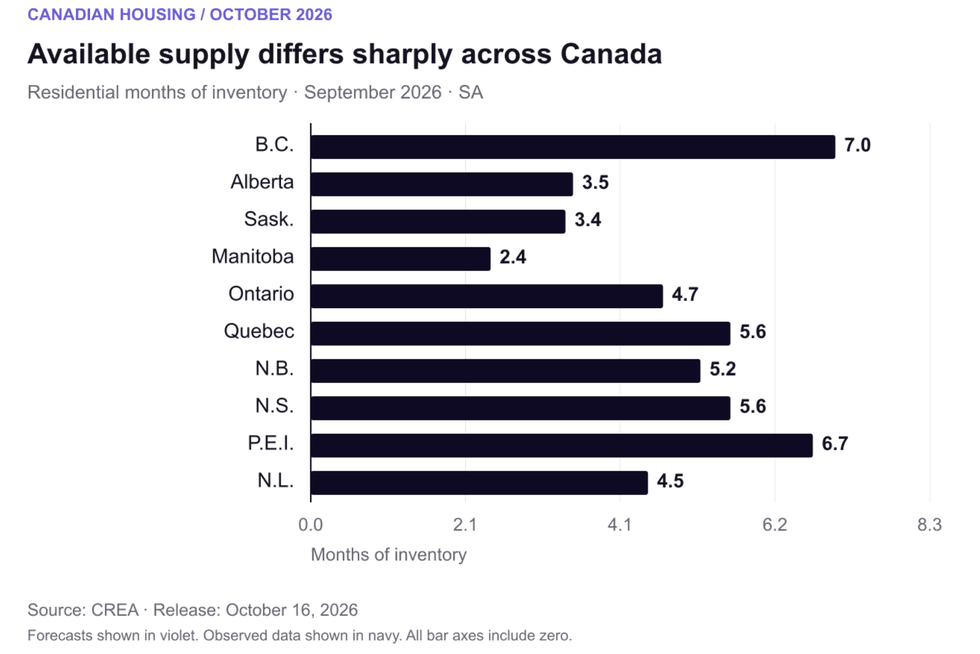 Seasonally adjusted residential months of inventory by province. Local property types can differ substantially. Chart:
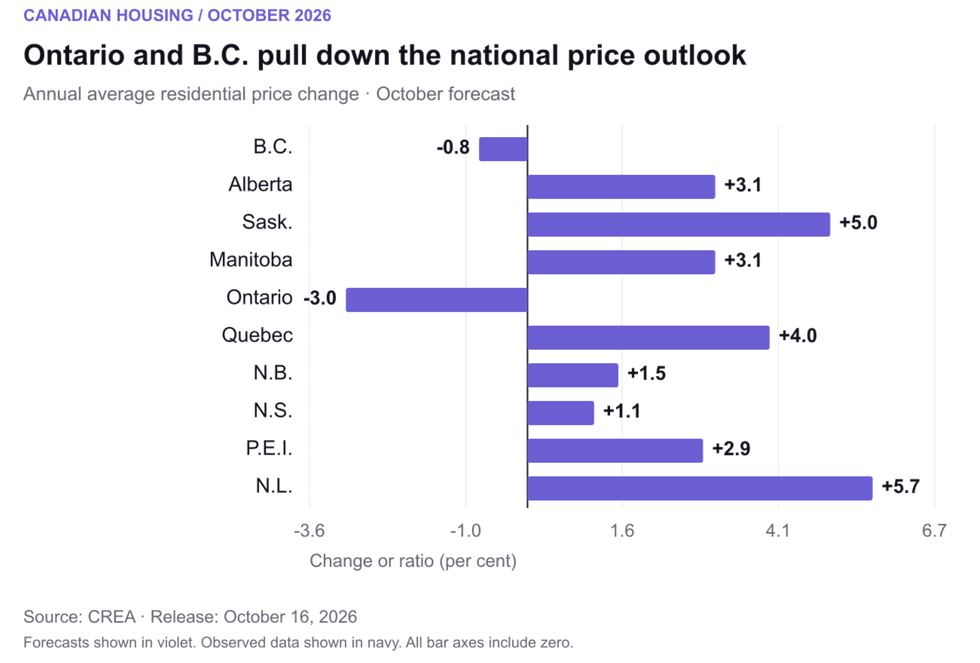 Ontario and B.C. are the two provinces with forecast annual average-price declines in 2026. Chart:
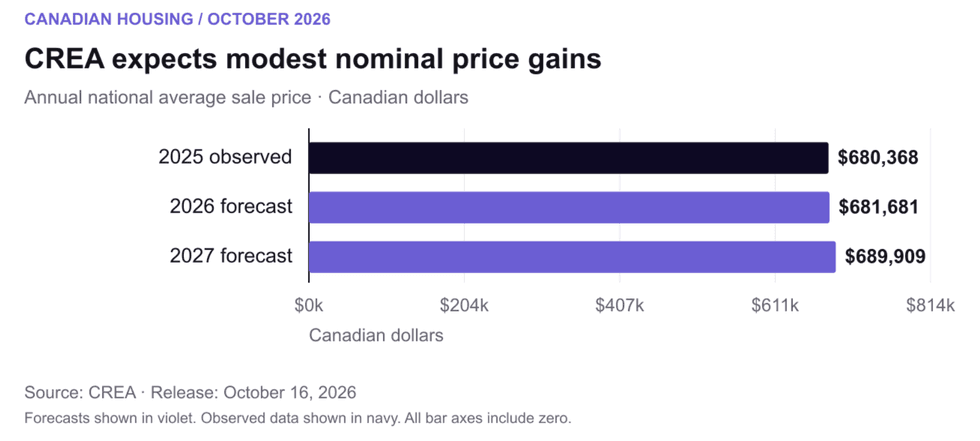 Annual average transaction prices in Canadian dollars. Forecast values are not December price targets. Chart:
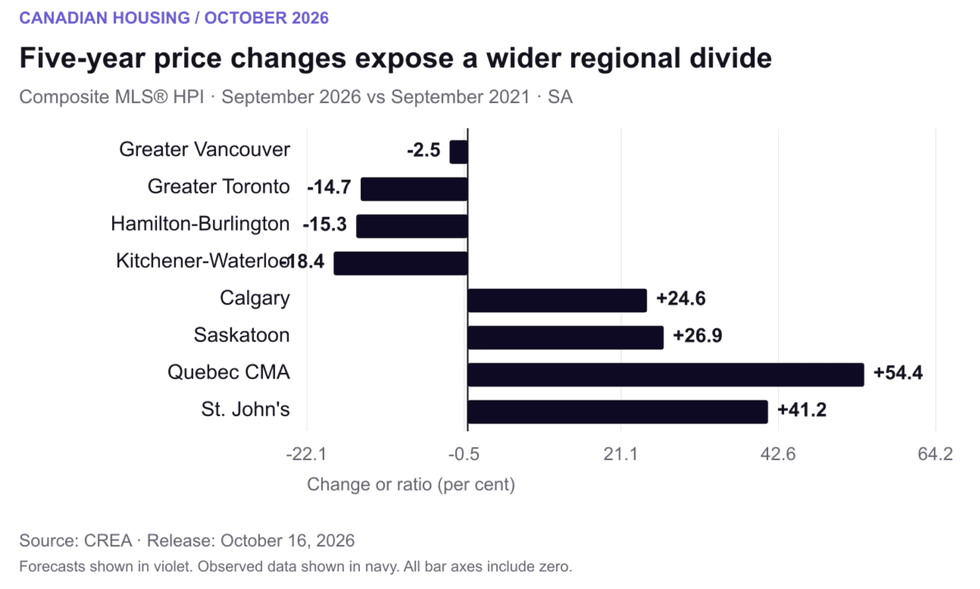 Five-year changes in seasonally adjusted composite MLS® HPI benchmarks, September 2021 to September 2026. Chart: