A two-building seniors residential complex in Ottawa's Citiplace neighbourhood has officially changed hands following a court-ordered sale, according to filings in Ontario Superior Court and a press release.
The complex consists of two separate buildings — the 125-suite Ravines Retirement Residence at 626 Prado Private and the adjacent 138-suite Ravines Senior Suites at 636 Prado Private — along the Nepean Creek near Rideau River in Ottawa.
Both buildings share an on-site management team as well as above-ground and underground corridors, as they were developed together by Ontario-based developer Choo Communities under its Ashcroft Homes brand — whose ReStays boutique hotel in Ottawa was sold last month as part of another receivership proceeding, as previously reported by STOREYS.
The Insolvencies
The proceedings began after Ashcroft Homes obtained creditor protection under the Companies’ Creditors Arrangement Act (CCAA) on December 5, 2024 for several of its corporate affiliates and projects, including 2139770 Ontario Inc. — the legal owner of Ravines Retirement Residence — and 2265132 Ontario Inc. — the legal owner of Ravines Senior Suites.
“According to Mr. Choo, despite a history of generating significant revenues and having significant net equity holdings, in recent years various members of the Ashcroft Homes Group have encountered liquidity issues related to rising interest rates and a decline in occupancy rates,” said the judge presiding over the case. “This has left the applicants finding themselves in a position of insufficient liquidity to meet their current debt obligations.”
An affidavit sworn by owner David Choo stated that they began working with lenders in late-2023 to address those shortfalls, which “resulted in a series of forbearance agreements and cross-guarantees being established that were designed to buy time to restore occupancy rates, including in some cases by the finalisation of construction, refinance existing lenders, and sell assets in order to pay down debt.”
The lender on Ravines Retirement Residence was Vancouver-based Central 1 Credit Union, which was owed $38,373,232.02 as of August 19, 2024.
The lender on Ravines Senior Suites was then ACM Advisors, a majority-owned subsidiary of EQ Bank (TSX: EQB), which was owed $45,234,932 as of October 2024. A second-ranking mortgage was held by Institutional Mortgage Capital (IMC).
Following the initial creditor protection period, however, the lenders on several of the projects opposed the continuation of the CCAA proceeding and initiated their own receivership proceedings against the properties.
The Sales Process
The two Ravines properties were placed under receivership and managed by two different receivers — BDO and KSV Restructuring (now known as AlixPartners) — that ultimately collaborated on the court-ordered sales process, with the properties being listed for sale by Newmark and made available for purchase separately or as a package, given some of the shared components.
BJ Bhal, David Kalinowsky, Mark Gallagher, Norm LeZotte, and Amani Jawhari served as the listing team, which listed the property on an unpriced basis and described the properties as an “Institutional-grade, continuum-of-care campus” that’s also “Well-positioned for short-term financing with clear path to equity takeout at stabilization,” according to a sales brochure obtained by STOREYS.
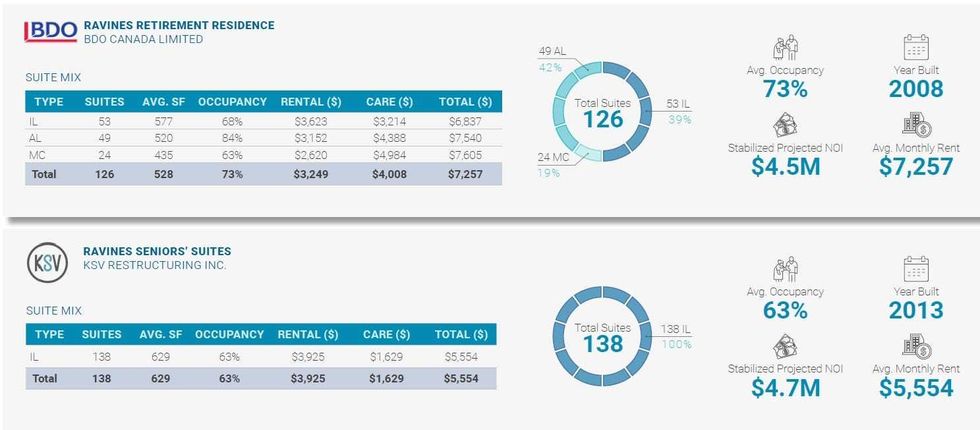
Ravines Retirement Residence has an occupancy rate of 73% and brings in $7,257 in average monthly rent while Ravines Senior Suites has an occupancy rate of 63% and average monthly rent income of $5,554.
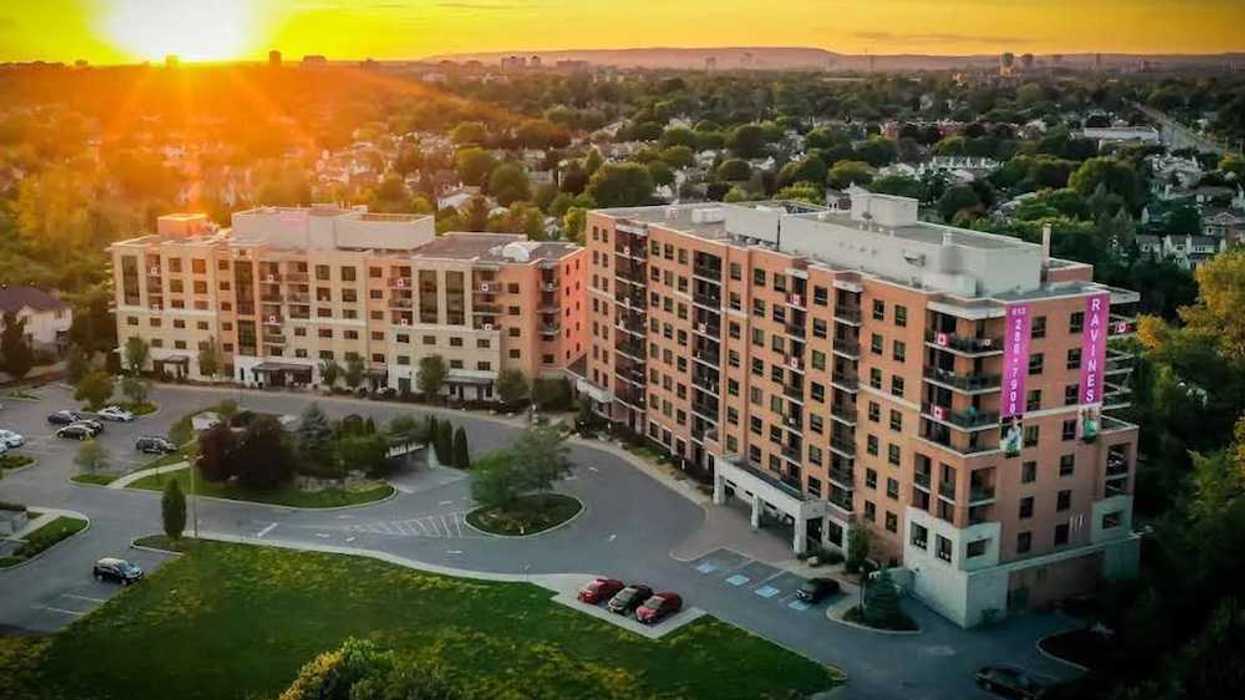
 An overview of the two Ravine buildings. (Newmark)
According to a report prepared by AlixPartners dated August 18, 2026, a total of 32 parties signed confidentiality agreements, eight tours were conducted, and two parties ultimately submitted a letter of intent. The selected bidder was set to buy both buildings and had 60 days for due diligence, but then asked to extend the due diligence period several times.
“By this time, the Receiver had significant concerns about the repeated requests for extensions made by the Original Purchaser,” said the AlixPartners. “The Receiver was also concerned in learning that the Original Purchaser had been engaged in discussions with, among others, David Choo and/or his representatives which facially appeared to be in violation of its obligations under its NDA.”
The Receiver nonetheless agreed to an extension to April 28, but the purchaser then said on that day that they were not proceeding with the transaction. A dispute arose over the deposit, but was ultimately settled with $15,000 of the deposit retained by the Receiver and the rest returned.
Verve Senior Living
With the transaction falling through, Newmark re-canvassed a short-list of prospective purchasers “to determine whether any buyer would be willing to ‘step into the shoes of’ the Original Purchaser.” Newmark approached six parties, the original purchaser expressed interest in re-submitting an offer, but the Receiver ultimately selected an offer from Verve Senior Living, a brand operated by Diversicare Canada Management Services Co.
The transaction was approved by the court on September 9 and the properties are now beneficially owned by Verve Nepean Limited Partnership through The Ravines SS Inc. and The Ravines PPP Inc. Verve announced the acquisition this week, saying the complex began operating as Verve The Ravines on September 22 with the existing staff in place and that they intend to invest $20 million in the property over the next two years.
“We are very excited about The Ravines and what it represents for Verve,” said President of Verve Senior Living Scott Quinney. “We see an outstanding community with great people, a strong reputation, and tremendous potential. Our commitment is to invest in the building, invest in the resident experience, invest in our team members, and in the future of senior living in the greater Ottawa and Nepean areas.”
According to the respective Receivers, as of July 31, 2026, Central 1 Credit Union was owed $42,206,830.40, while ACM was owed $29.5 million and IMC was owed $13.9 million. Central 1 is expected to see a shortfall while ACM and IMC are both expected to be repaid in full.