First-Time Home Buyer RRSP Withdrawal
Learn how first-time buyers can use the RRSP Home Buyers’ Plan in Canada to withdraw funds for a down payment and what rules apply.
May 22, 2025
What is the First-Time Home Buyer RRSP Withdrawal?
The First-Time Home Buyer RRSP Withdrawal, also known as the Home Buyers’ Plan (HBP), allows eligible Canadians to withdraw up to $35,000 from their Registered Retirement Savings Plan (RRSP) to buy or build their first home.
Why the First-Time Home Buyer RRSP Withdrawal Matters in Real Estate
This program provides a valuable resource for first-time buyers by enabling them to access retirement savings without immediate tax consequences.
Key features include:
- Withdraw up to $35,000 (or $70,000 per couple)
- Funds must be repaid to the RRSP over 15 years
- No tax withheld at withdrawal if conditions are met
- Must not have owned a home in the past four years
To qualify, the buyer must have a written agreement to buy or build a qualifying home. The withdrawn funds can be used for the down payment or other purchase-related expenses.
The repayment schedule begins the second year after withdrawal, with annual minimum payments. If a repayment is missed, the amount is added to the person’s taxable income for that year.
The HBP helps reduce borrowing needs and makes it easier to afford a first home. However, it’s important to understand the long-term impact on retirement savings and stay on track with repayments to avoid tax penalties.
Example
A first-time buyer withdraws $25,000 from their RRSP for a down payment. They repay $1,667 annually over 15 years to avoid tax on the withdrawal.
Key Takeaways
- Withdraw up to $35,000 from RRSP tax-free.
- Must be repaid over 15 years.
- Useful for down payments.
- Helps reduce mortgage size and interest.
- Must meet first-time buyer eligibility.
Related Terms
- Home Buyer’s Plan (HBP)
- Down Payment
- RRSP
- First-Time Home Buyer Incentive
- Tax-Free Savings Account (TFSA)
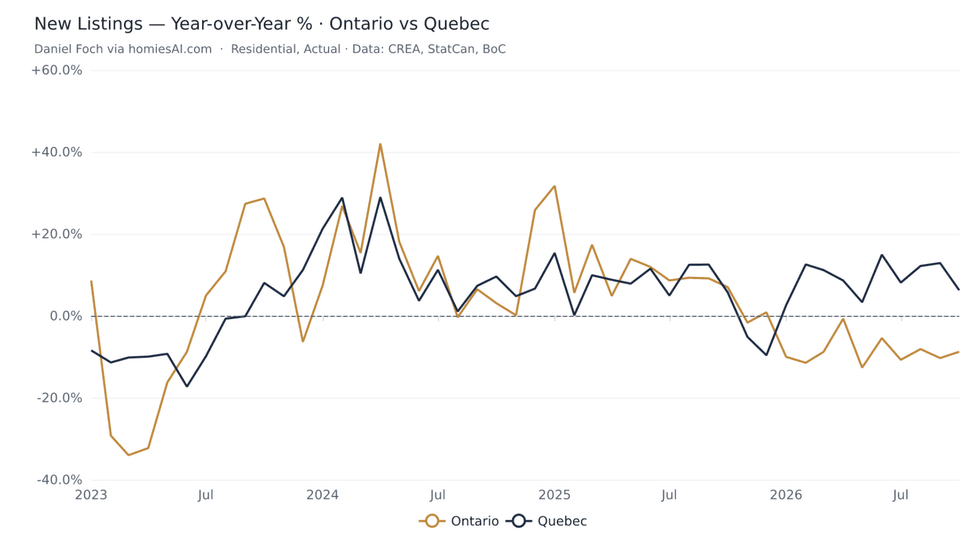 Chart: New listings, year-over-year %, Ontario vs Quebec. Daniel Foch via homiesai.com/stats. Data:
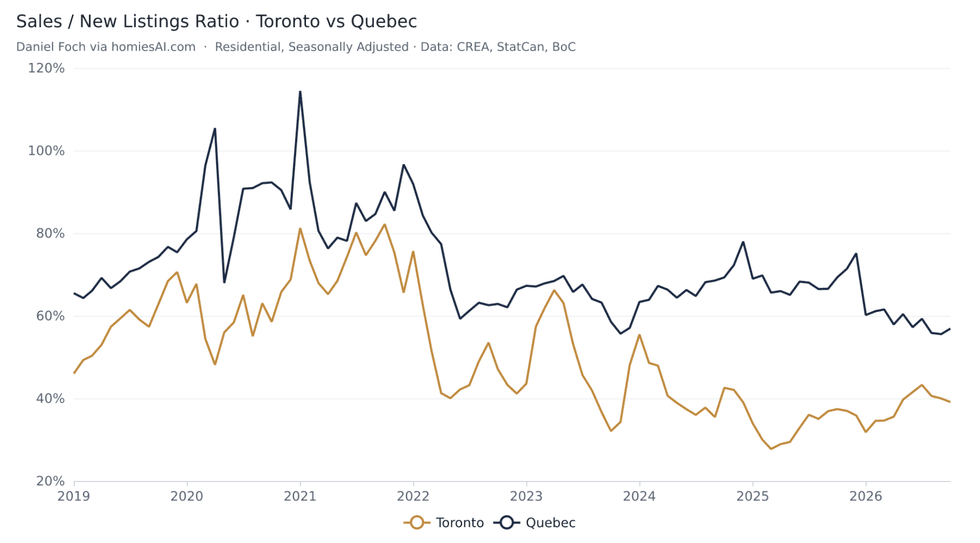 Chart: Sales-to-new-listings ratio, seasonally adjusted. Toronto vs Quebec. Daniel Foch via homiesai.com/stats. Data: CREA.
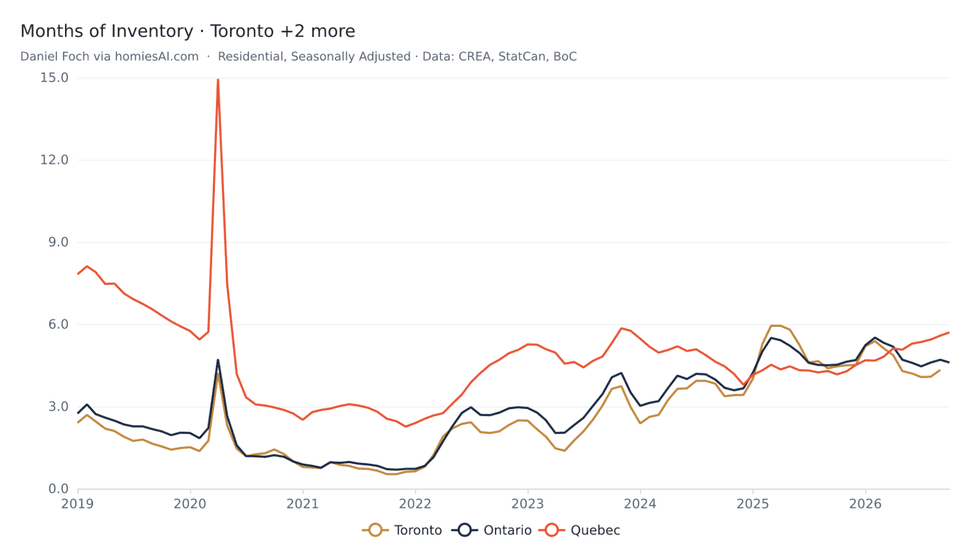 Chart: Months of inventory, seasonally adjusted. Daniel Foch via homiesai.com/stats. Data: CREA.
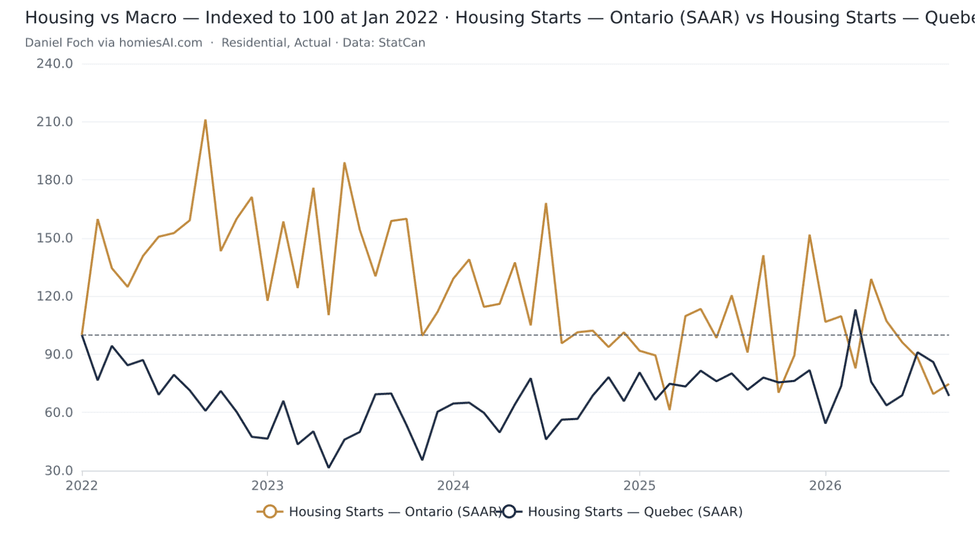 Chart: Housing starts, seasonally adjusted annual rate, Ontario vs Quebec, indexed to January 2022. Daniel Foch via homiesai.com/stats. Data: CMHC via Statistics Canada.
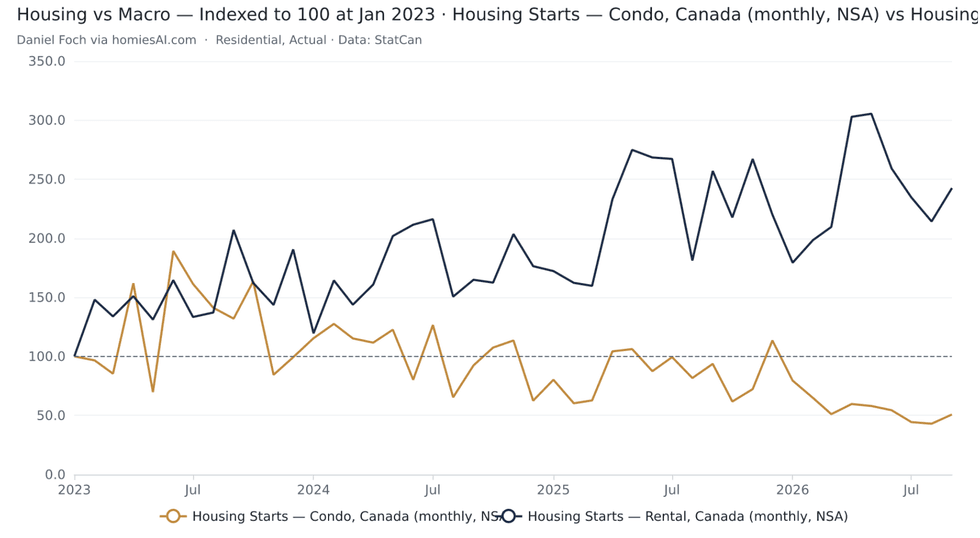 Chart: Condo vs rental housing starts, Canada, indexed to January 2023. Daniel Foch via homiesai.com/stats. Data: CMHC via Statistics Canada.
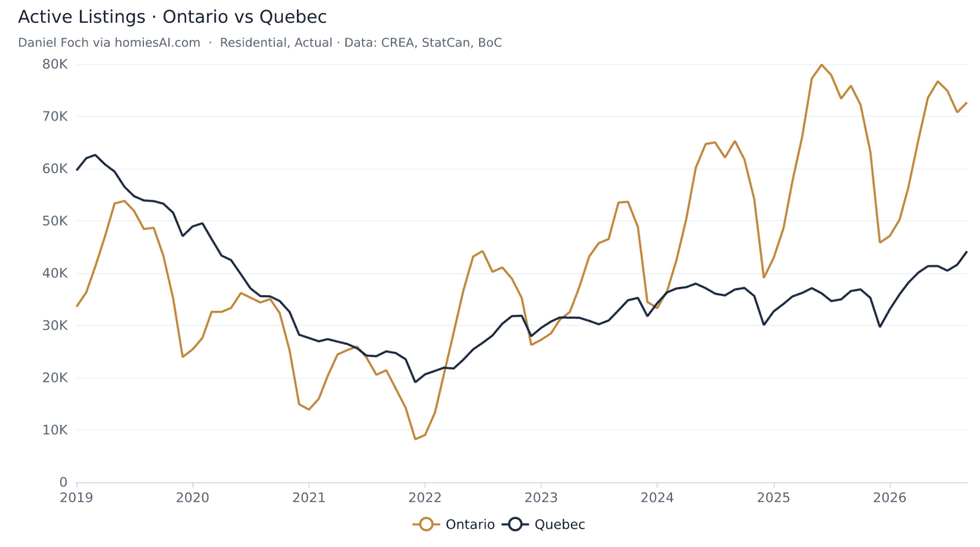 Chart: Active residential listings, Ontario vs Quebec. Daniel Foch via homiesai.com/stats. Data: CREA.



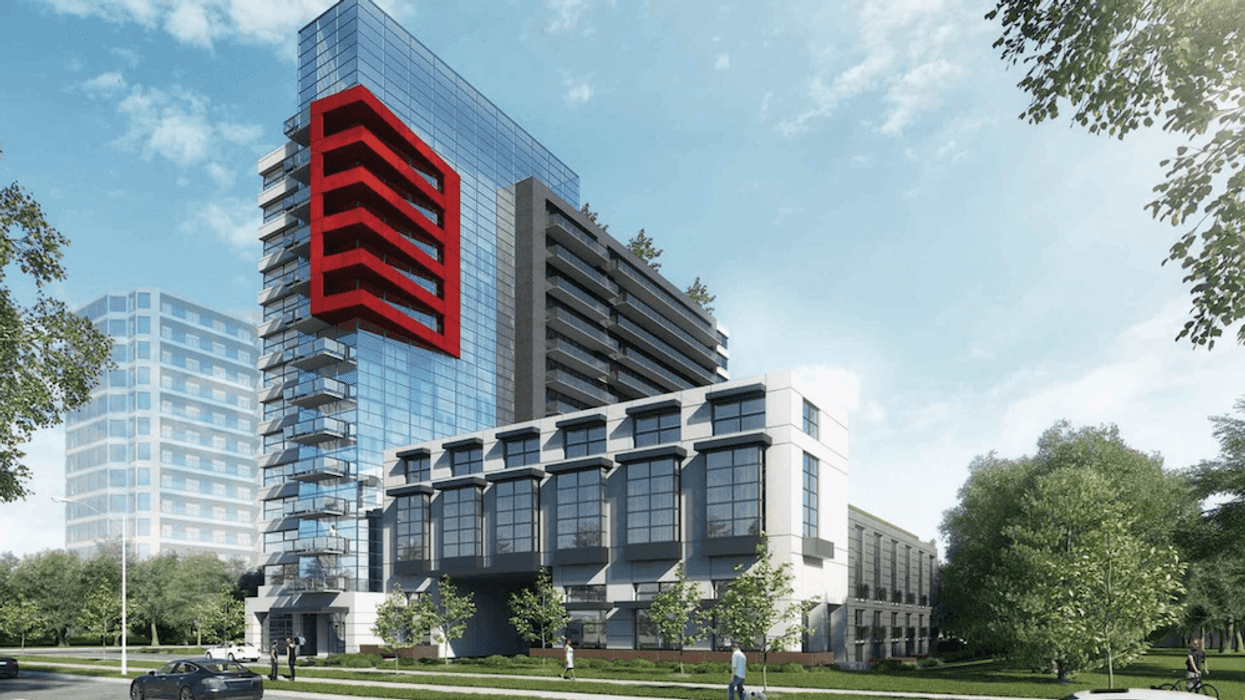
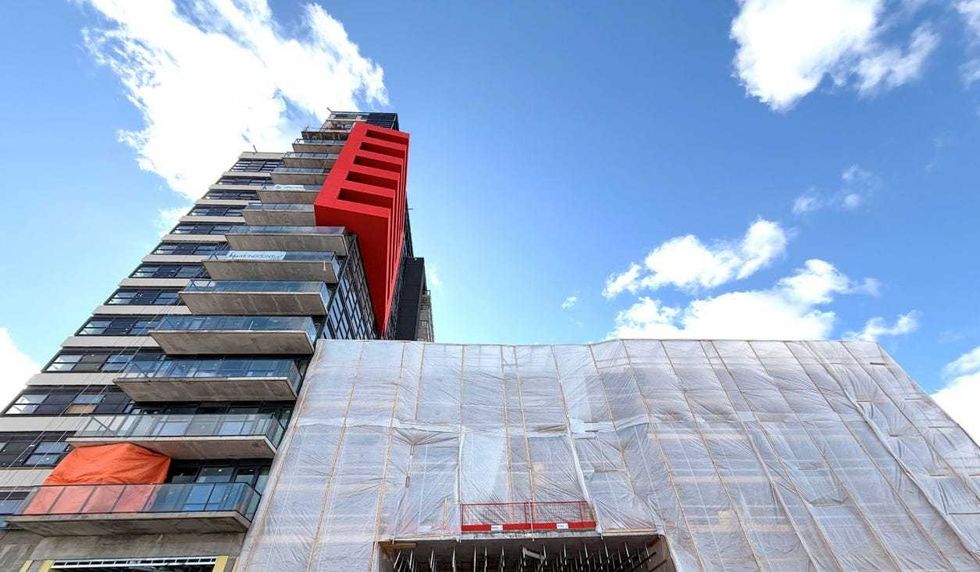 The Highlight of Mississauga as of March 2026. (Grant Thornton)
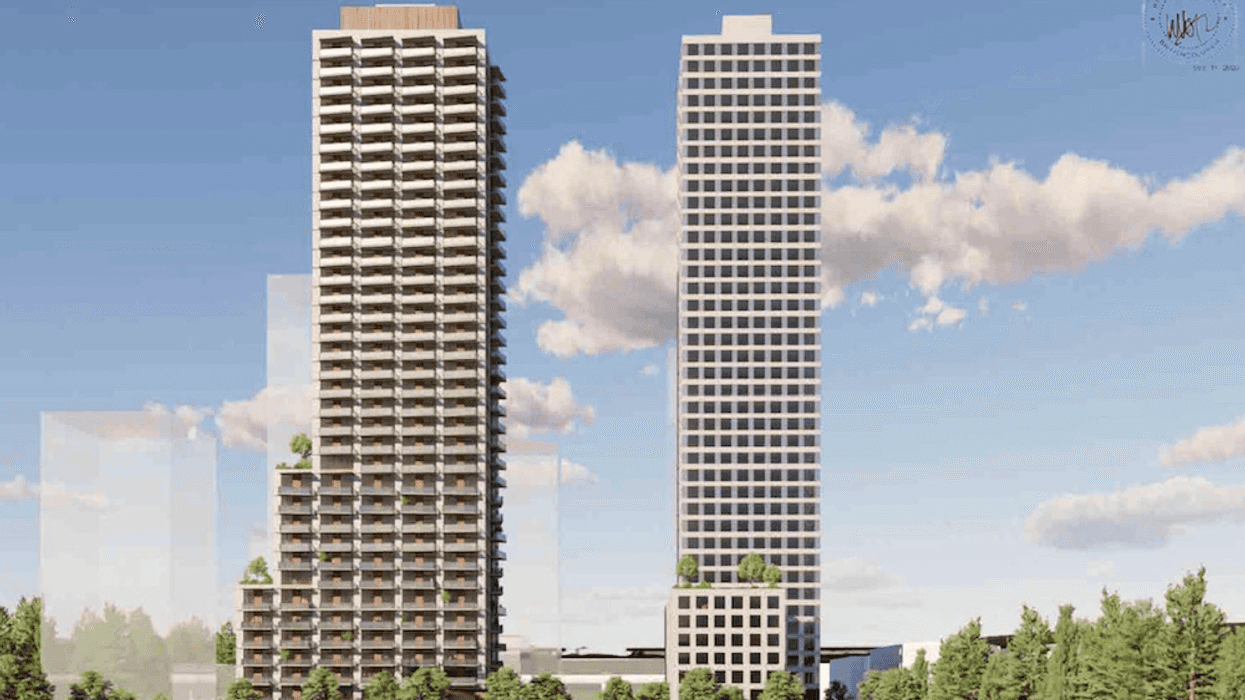
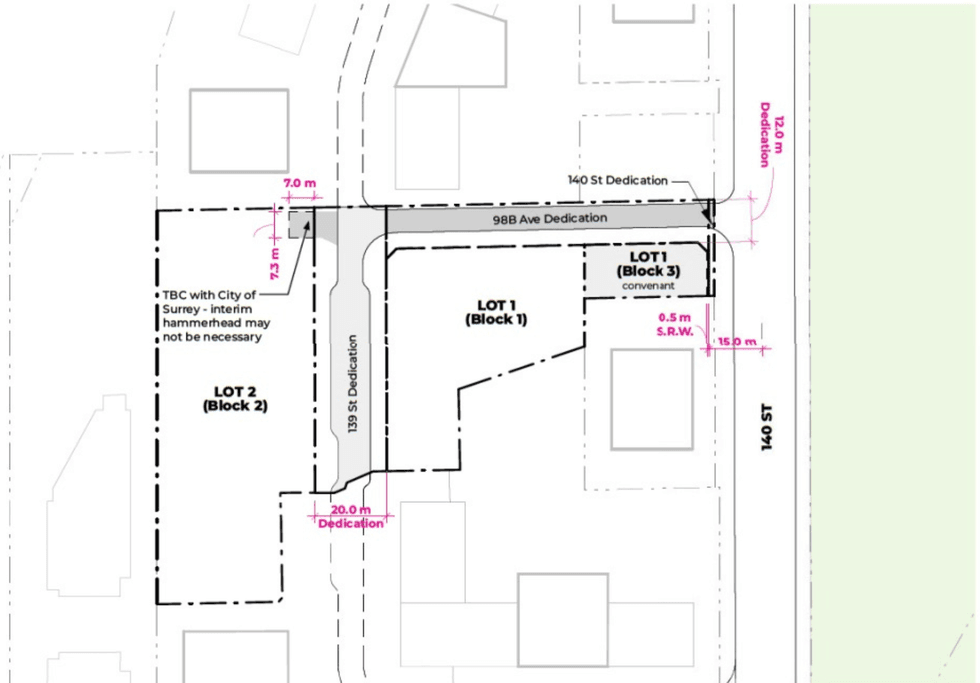 9883 140 Street and the proposed road dedications. (WW+P Architects, Entre Nous Femmes Housing Society)
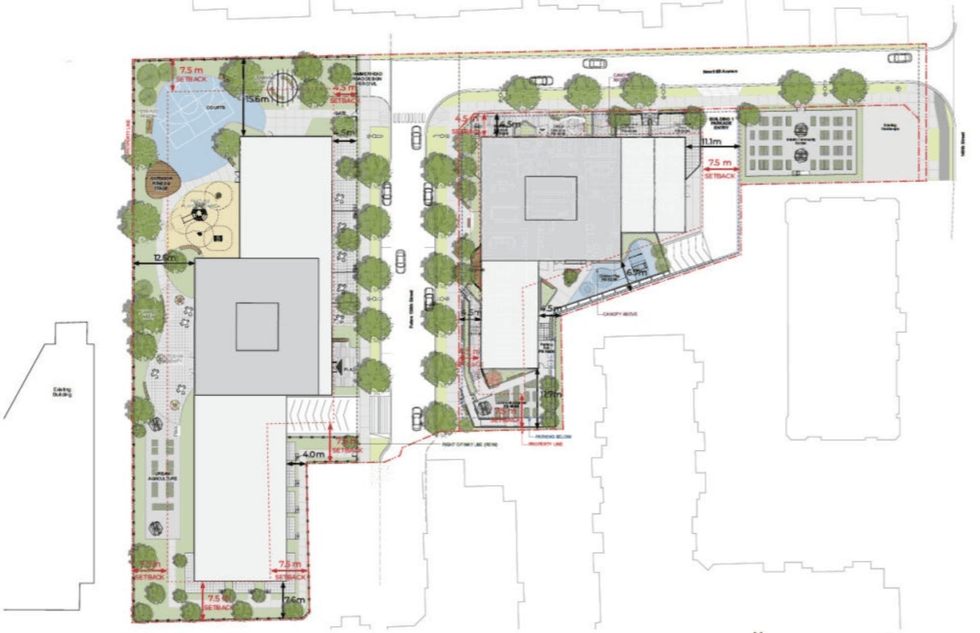 The
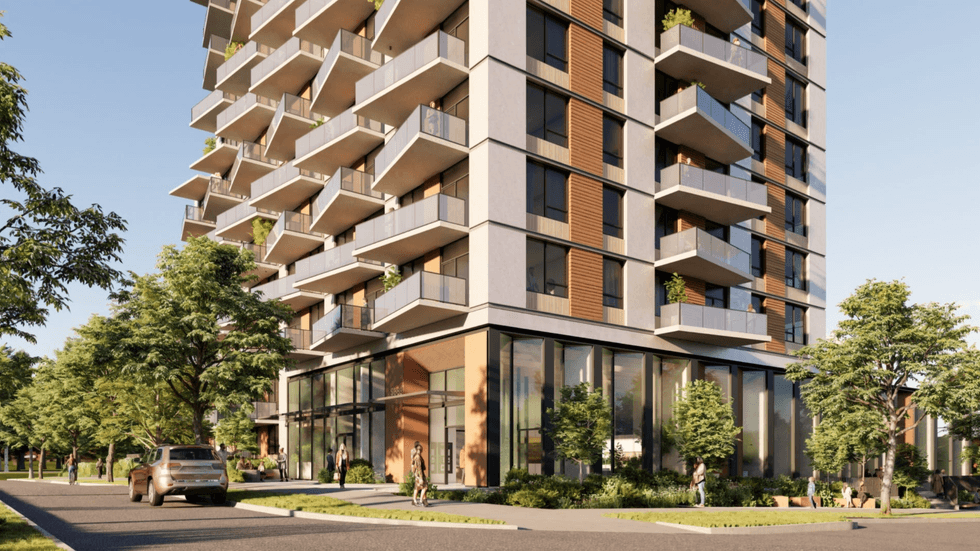 One of the towers proposed for 9883 140 Street. (Entres Nous Femmes Housing Society)

 Canadian respondents were more likely to expect an undersupply of development/redevelopment equity capital (63%) than debt capital (46%) in 2027. These are survey expectations, not measured financing volumes. Source: PwC and ULI, Emerging Trends in Real Estate 2027, pp. 136–137. Original chart.
 Toronto census metropolitan area housing starts fell from 37,718 units in 2024 to 26,087 in 2025, a 30.8% decline (rounded to 31%). Starts measure construction begun, not completed homes. Source: CMHC, as cited in PwC and ULI, Emerging Trends in Real Estate 2027, p. 145. Original chart.




 Illustrative calculation: a $4.5-million value ceiling versus income-based capacity of about $4.25 million at 4%, $3.62 million at 5% and $3.13 million at 6%. Assumes 50-year amortization and 1.15 debt coverage.
 Source: Department of Finance missing-middle backgrounder and Budget 2026 Chapter 3, November 5, 2026. Fiscal-year funding starts are not home-completion dates.