Convertible Mortgage
Explore convertible mortgages in Canadian real estate — what they offer, when they’re used, and their benefits for borrowers.
July 27, 2025
What is a Convertible Mortgage?
A convertible mortgage is a loan that starts with a short-term, often variable rate, giving the borrower the option to convert to a longer-term fixed rate without penalty during the term.
Why Convertible Mortgages Matter in Real Estate
In Canadian financing, convertible mortgages offer flexibility to adapt to changing interest rates and borrower needs.
Key features:
- Starts with short-term or variable rate
- Option to lock in fixed rate later
- May have slightly higher initial rate than traditional variable loans
Understanding convertible mortgages helps borrowers balance flexibility and stability.
Example of a Convertible Mortgage in Action
The buyer chose a convertible mortgage, planning to switch to a fixed rate if interest rates began to rise.
Key Takeaways
- Starts flexible, option to lock fixed rate
- Helps manage interest rate risk
- Useful in uncertain rate environments
- May have slightly higher initial rate
- No penalty for conversion during term
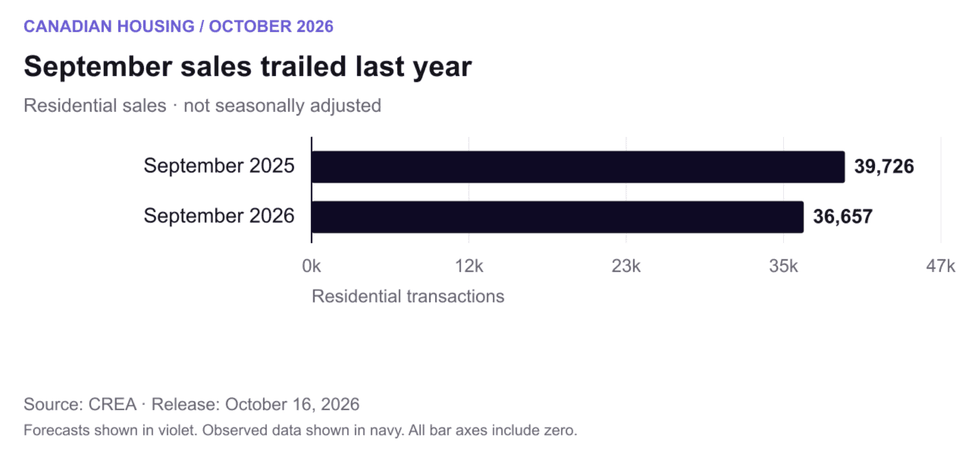 September residential sales, not seasonally adjusted; the annual comparison uses CREA’s revised figures. Chart:
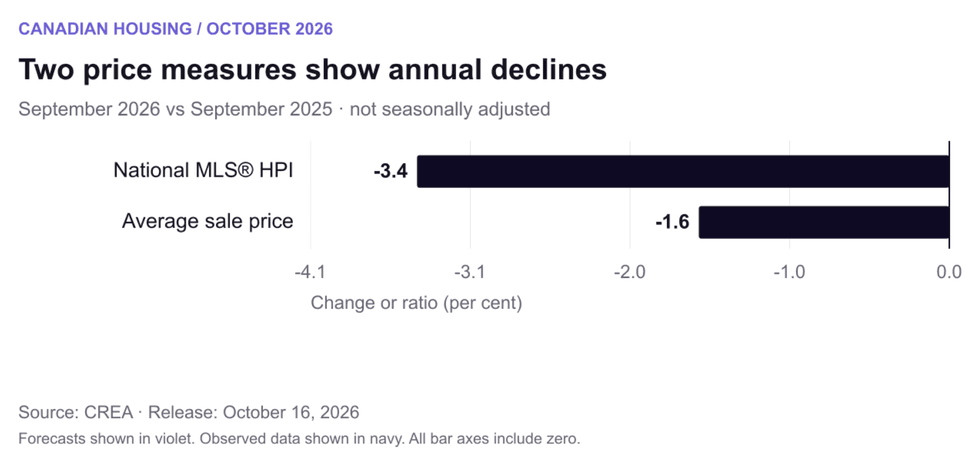 Annual changes in the unadjusted national MLS® HPI and average sale price. The average is affected by the mix of transactions. Chart:
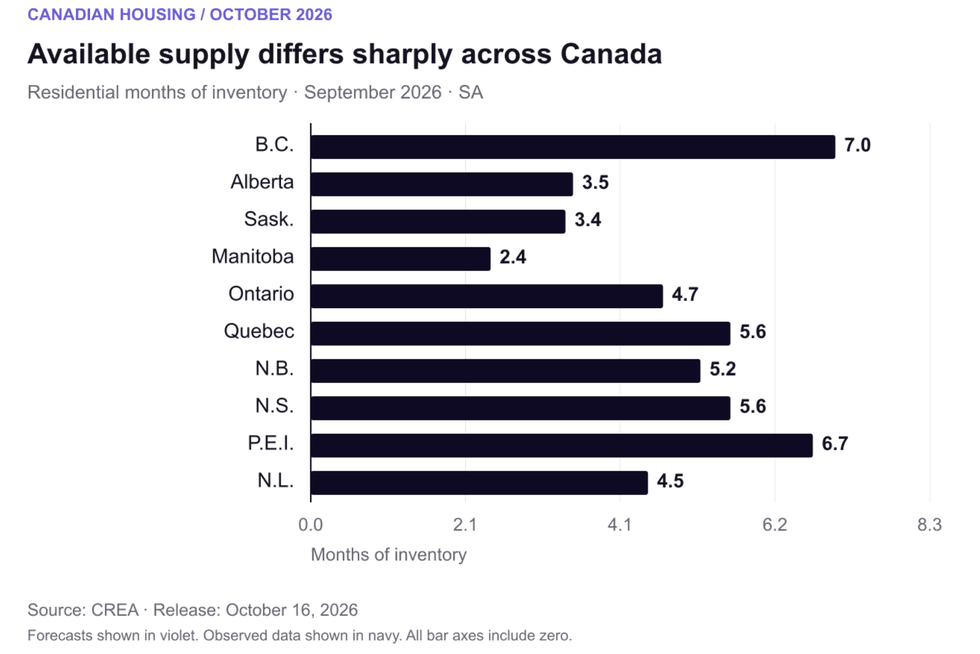 Seasonally adjusted residential months of inventory by province. Local property types can differ substantially. Chart:
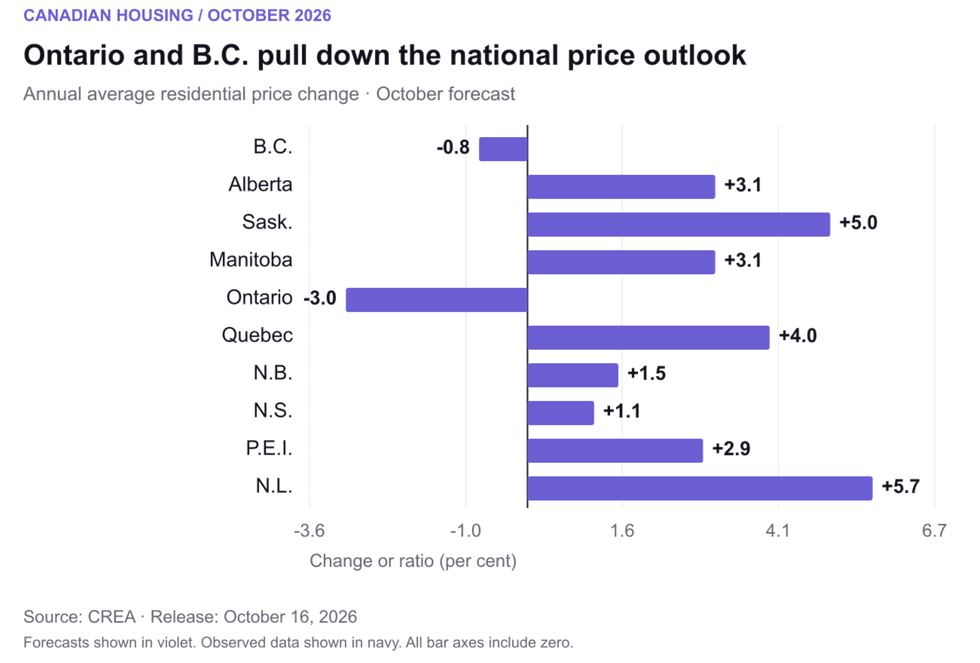 Ontario and B.C. are the two provinces with forecast annual average-price declines in 2026. Chart:
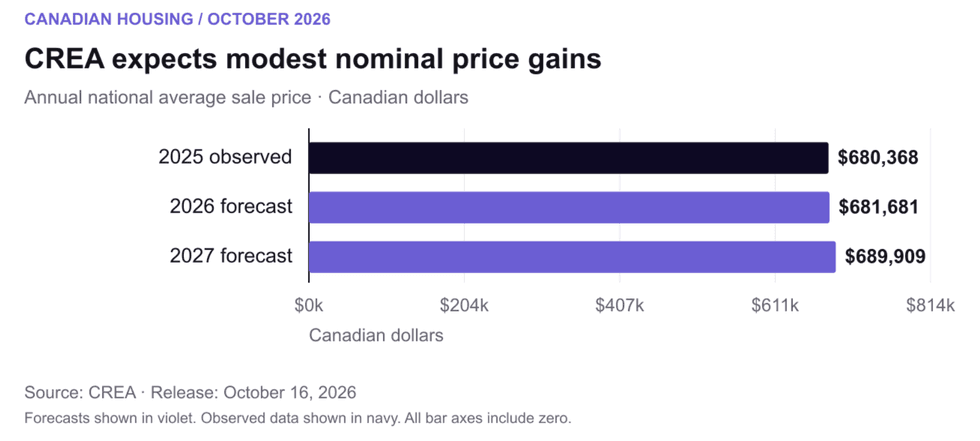 Annual average transaction prices in Canadian dollars. Forecast values are not December price targets. Chart:
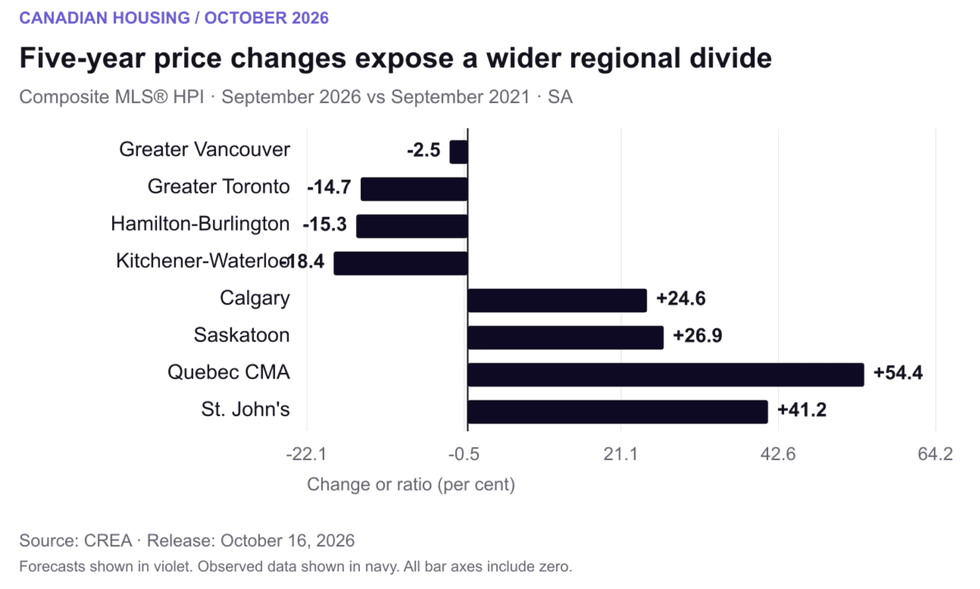 Five-year changes in seasonally adjusted composite MLS® HPI benchmarks, September 2021 to September 2026. Chart: