Blended Mortgage
Understand blended mortgages in Canadian real estate — what they are, when they’re used, and their advantages for borrowers.
July 27, 2025
What is a Blended Mortgage?
A blended mortgage combines two different mortgage loans or interest rates into one, resulting in a new single loan with a blended interest rate.
Why Blended Mortgages Matter in Real Estate
In Canadian mortgage financing, blended mortgages help borrowers modify financing without full refinancing, often during porting or top-up situations.
Key features:
- Mixes existing loan with new funds
- Creates an average (blended) interest rate
- May avoid penalties for breaking existing mortgage
Understanding blended mortgages helps homeowners manage changing financing needs.
Example of a Blended Mortgage in Action
The homeowner used a blended mortgage to combine their existing loan with additional funds for a home addition.
Key Takeaways
- Combines old and new mortgage loans
- Creates a blended interest rate
- Useful for adding funds or porting
- May reduce penalty costs
- Supports flexible financing
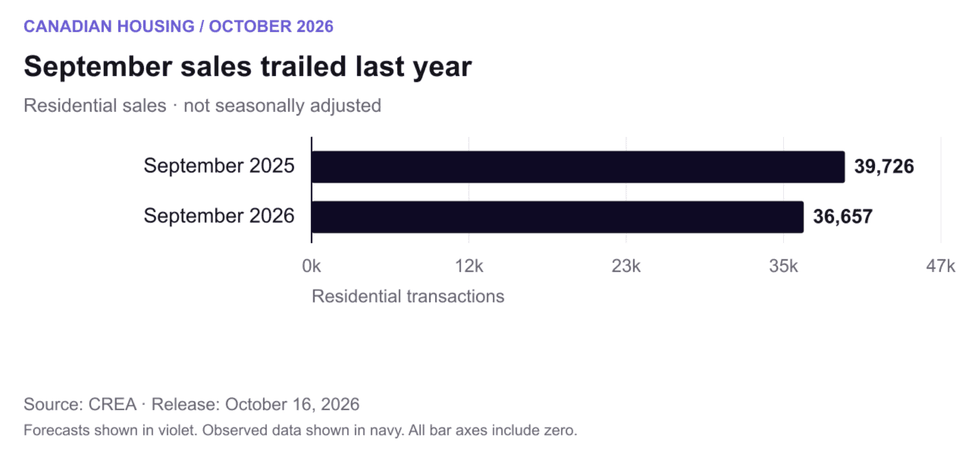 September residential sales, not seasonally adjusted; the annual comparison uses CREA’s revised figures. Chart:
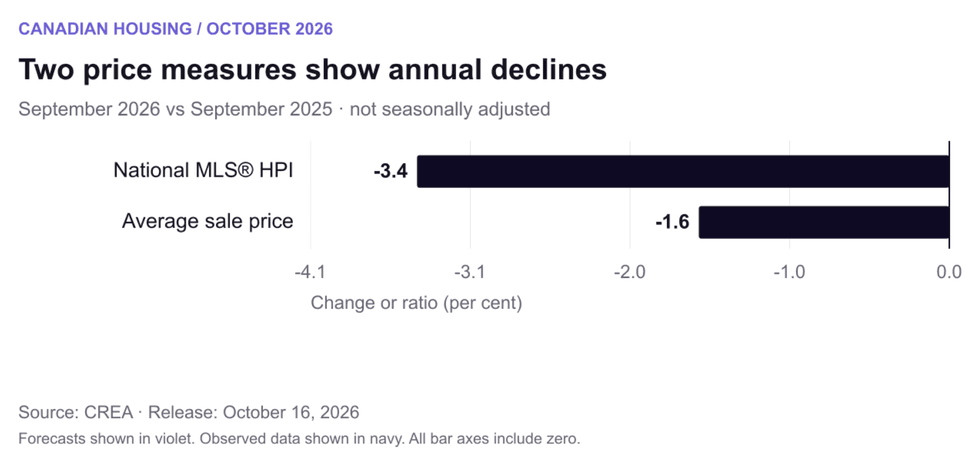 Annual changes in the unadjusted national MLS® HPI and average sale price. The average is affected by the mix of transactions. Chart:
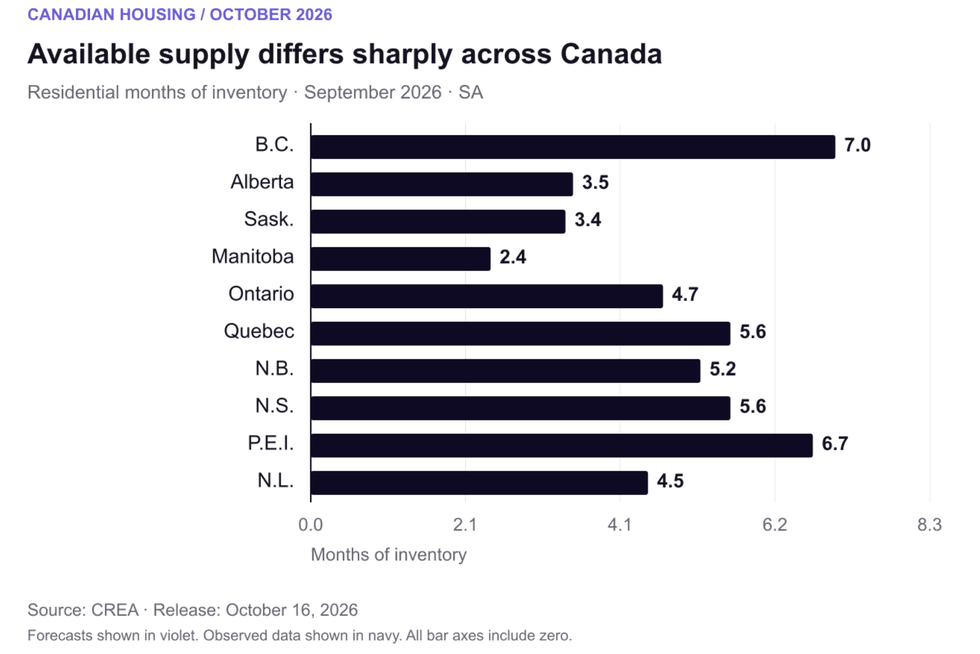 Seasonally adjusted residential months of inventory by province. Local property types can differ substantially. Chart:
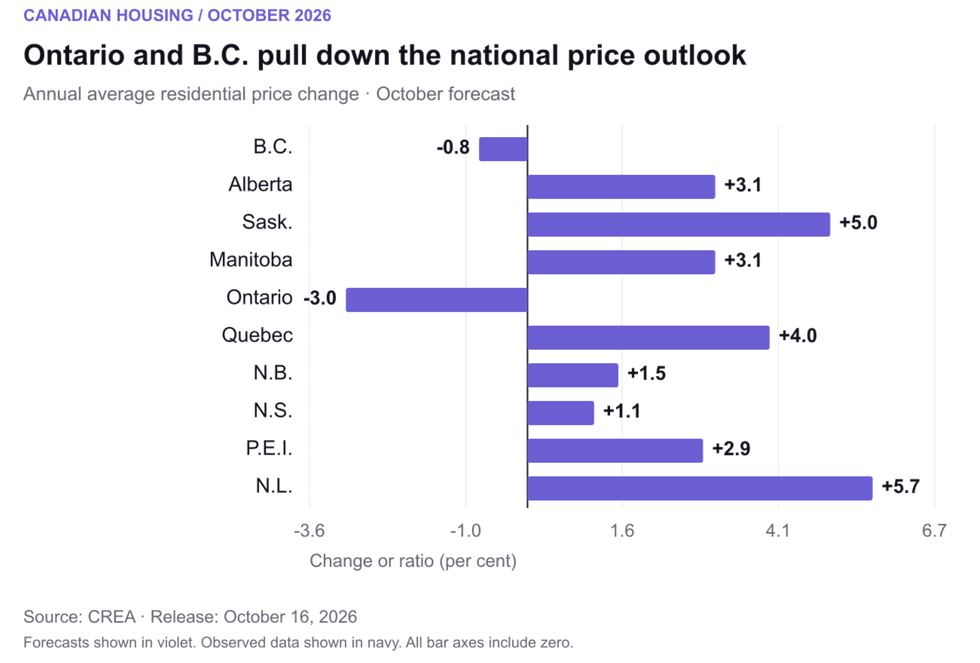 Ontario and B.C. are the two provinces with forecast annual average-price declines in 2026. Chart:
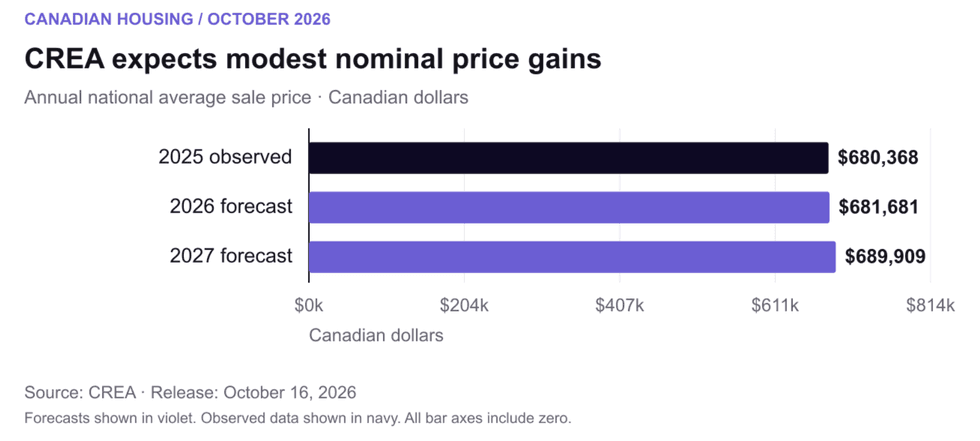 Annual average transaction prices in Canadian dollars. Forecast values are not December price targets. Chart:
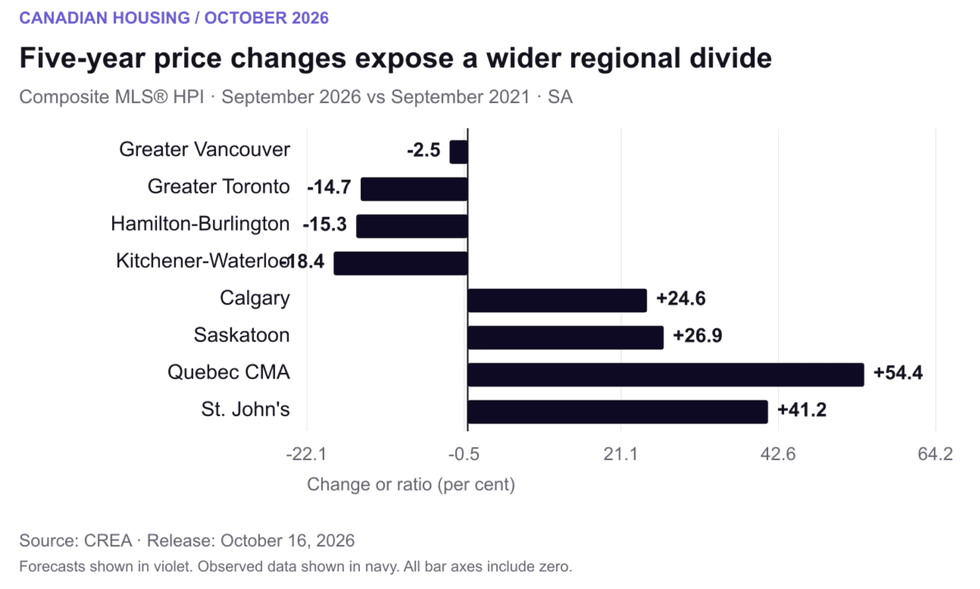 Five-year changes in seasonally adjusted composite MLS® HPI benchmarks, September 2021 to September 2026. Chart: