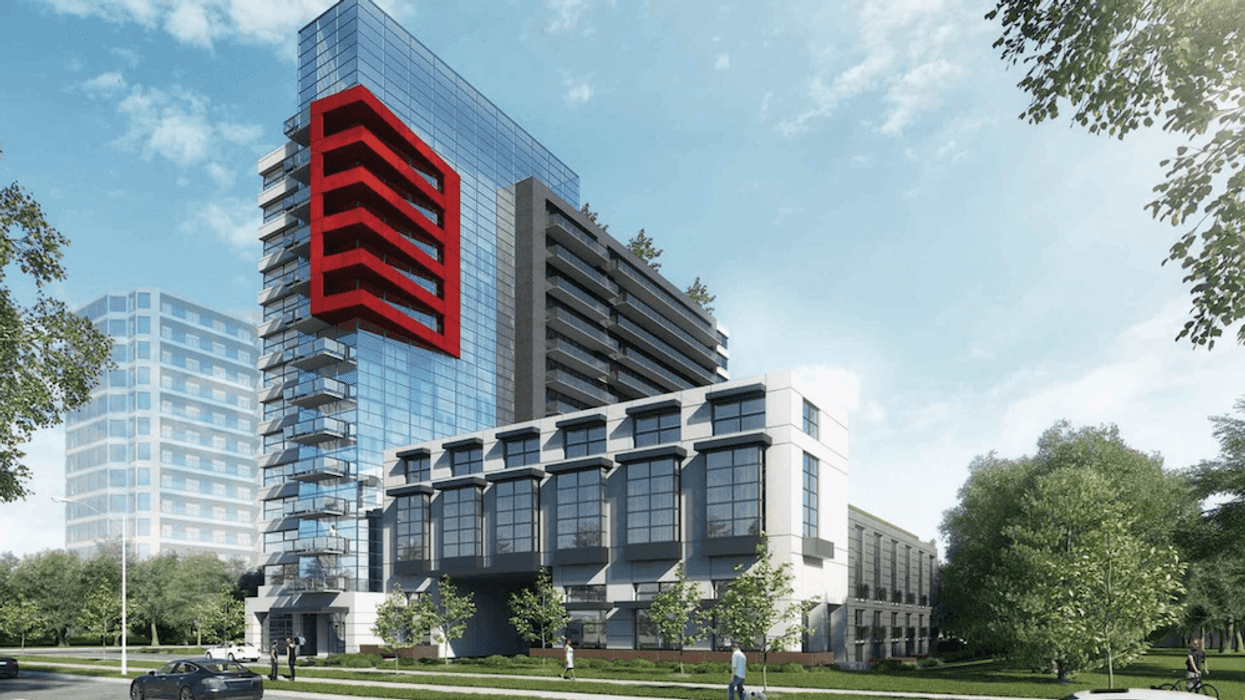
A large condo project in Mississauga that became insolvent and was placed under creditor protection mid-construction over four years ago has officially been sold, according to filings in Ontario Superior Court.
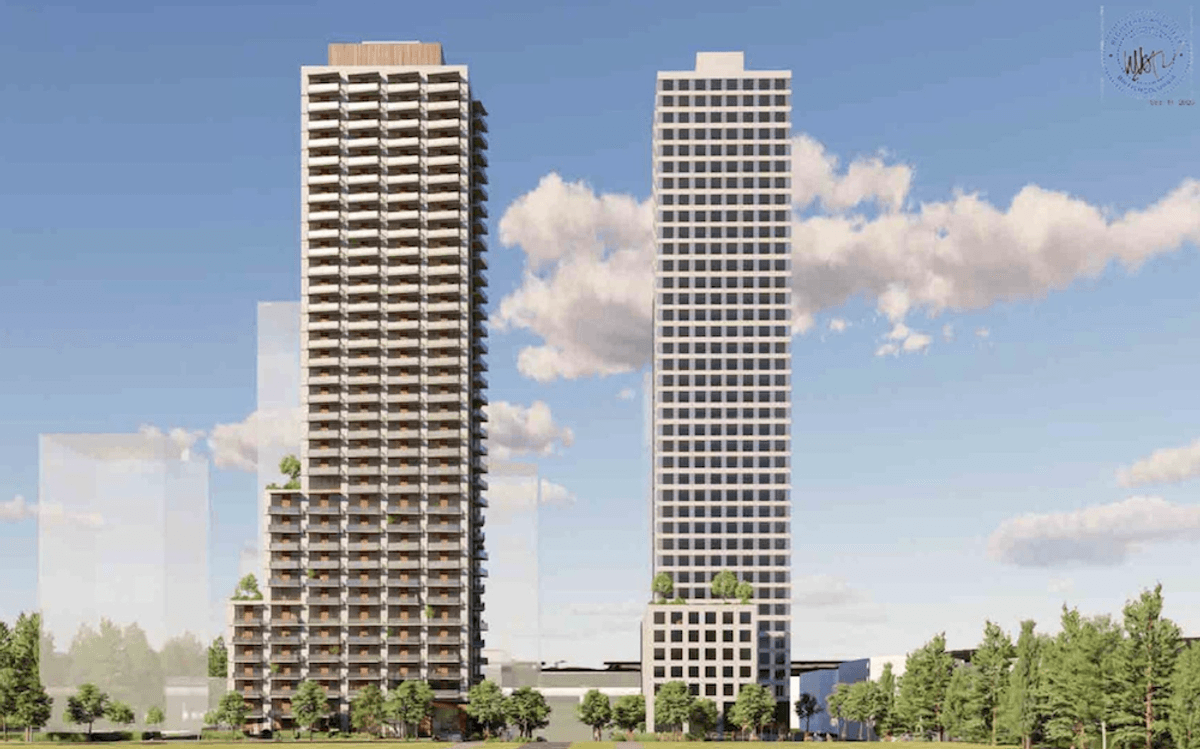
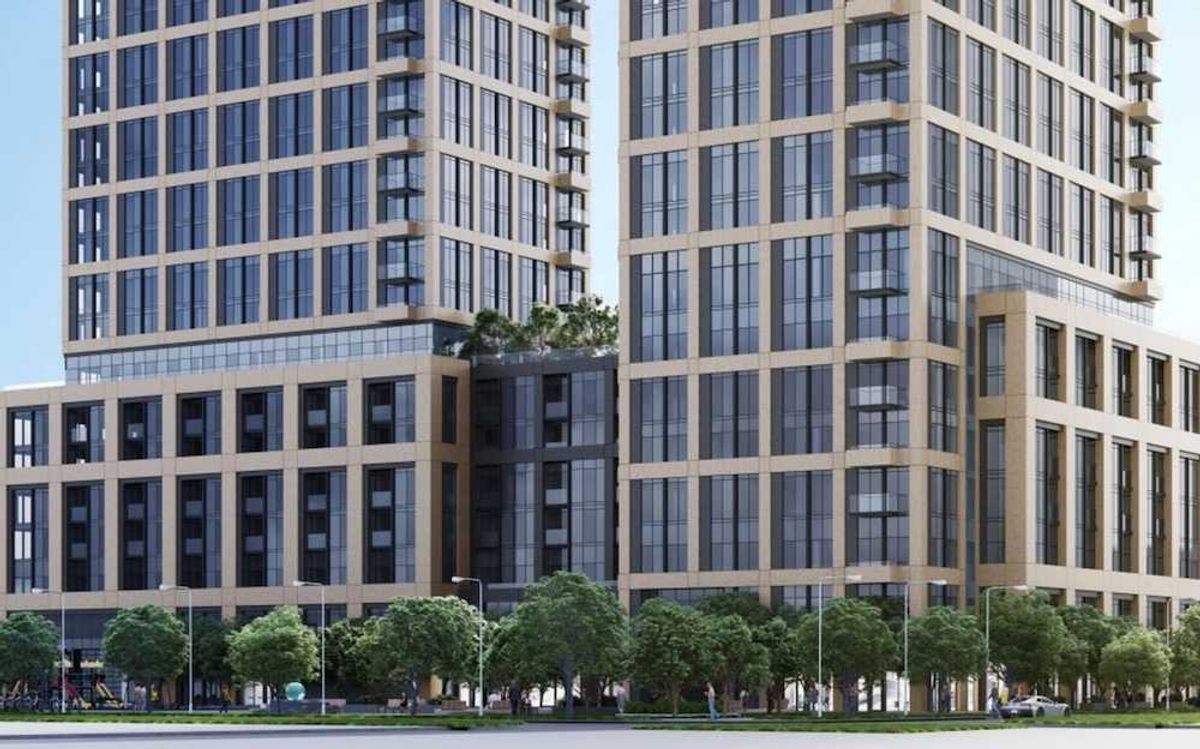
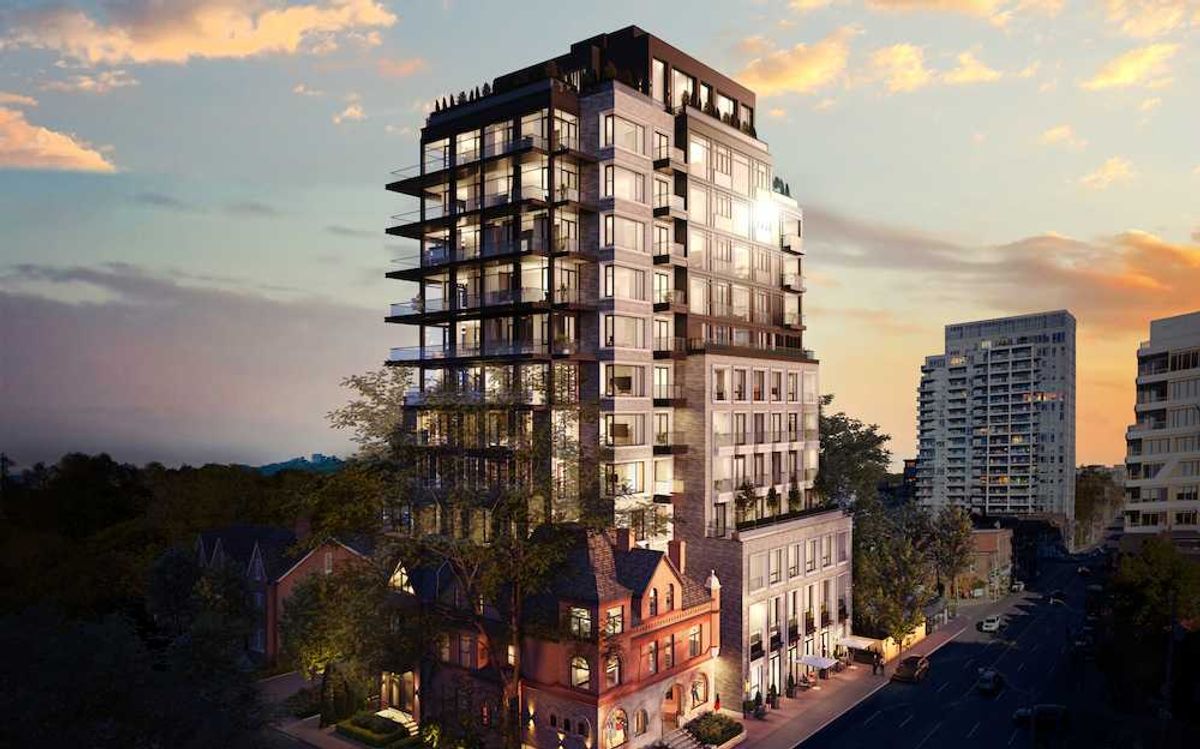
The project is known as Highlight of Mississauga and is located at 4064, 4070, and 4078 Dixie Road, right across the street from Rockwood Mall in Mississauga.
The developer was a company called Hazelton Development Corporation (HDC) and the project website identifies an individual named Du Zhixian as the company’s President. Court documents also refer to him as Joe Du, and note that the company is majority-owned by “a prominent construction family in China.”
For the site, Hazelton Development Corporation was developing a 14-storey project with 265 strata units, including both condos and townhomes. Presales launched around May 2018 and 261 of 265 units were pre-sold, generating a total of $111,633,085 in revenue.
Construction commenced in September 2019 and completion was targeted for April 2021, but the project faced delays and liquidity issues that resulted in HDC seeking out creditor protection under the federal Companies’ Creditors Arrangement Act (CCAA) in April 2022, by which construction had reached Level 12.
The Debts
For the project, Hazelton took out a first-ranking mortgage with Meridian Credit Union in May 2019 for a construction loan with a principal amount of up to $50 million, plus a stand-by letter of credit facility up to $2 million.
It also took out a second mortgage with Centurion Mortgage Capital Corporation — which was folded into Centurion Asset Management in 2024 — for a construction facility of up to $19.9 million, plus a cost-overrun facility up to $3.5 million.
As of the time of their filing, HDC owed approximately $20,694,142 to Meridian and $20,673,626 to Centurion, for a total of $41,367,768, with interest continuing to accrue.
According to HDC, certain shareholders also loaned HDC approximately $6.35 million between September 2019 and March 2022, and a company called Triumph Eastern Investments Inc. also advanced six loans between October 2021 and March 2022.
Various amounts were also owed to contractors.
The Insolvency
Hazelton Development Corporation said they faced trouble from the onset as the COVID-19 pandemic hit just a few months after construction commenced. In March 2020, they notified purchasers that the project would be delayed. Construction later resumed, but HDC had to issue additional delay notices in May 2021, November 2021, January 2022, and March 2022.
“The initial construction budget for the Project was $101,183,823,” said HDC. “By November 2021, under previous management, the forecasted construction budget had increased by $11,672,011 to $113,669,237. These increases were due to, among other things: two significant delays on account of Covid-19 lock-downs, an increased level of supervision and project management, substantial increases to the hard costs budget for concrete, masonry, mechanical equipment and electrical work, and various material increases to the soft costs budget.”
Construction loan agreements often include obligations that borrowers maintain a minimum debt-to-equity ratio, but although HDC was able to raise additional equity from shareholders, it was not enough to satisfy Meridian’s requirement, and the lender ceased advances in July 2021, forcing HDC to rely on Centurion and buyer deposits.
In March 2022, the Du family bought out a group of shareholders, which gave them an 80% stake in HDC, and brought in new management to stabilize the project. A month later, in April 2022, HDC filed for creditor protection.
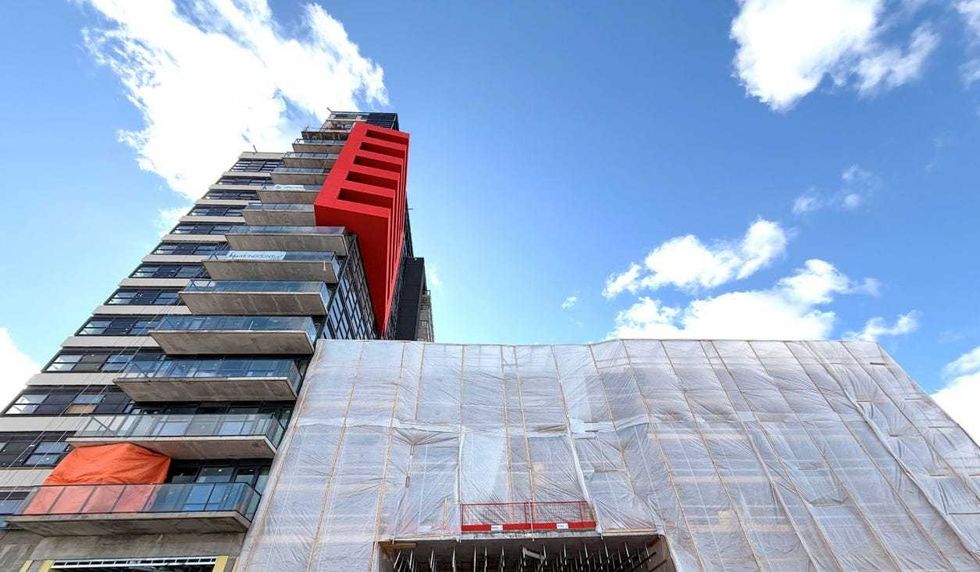 The Highlight of Mississauga as of March 2026. (Grant Thornton)
Under Creditor Protection
In July 2022, Toronto-based non-bank lender Firm Capital (TSX: FC) emerged as a sponsor and agreed to loan up to $80 million to pay off various debts and finance the construction of Highlight of Mississauga. The plan was approved, and construction then resumed.
In February 2023, the court then granted an order allowing the presale purchasers to be given two options. The first option would allow them to carry on with the purchase under revised terms, while the second option would terminate the presale agreement and see the buyer be compensated for their deposit with a 12% premium.
Although there were disputes with contractors and various other delays, construction continued and reached approximately 92.6% completion by February 2026, when the court-appointed Monitor said that “The ongoing deficiencies, construction challenges, weather-related delays, rising completion costs, and the Company’s funding constraints, have resulted in further delays to completion” and that “The Monitor understands that completion of the Project may no longer be feasible.”
By then, most of the presale purchasers had taken the compensation option and there were 197 unsold units. Lien claims by contractors had also continued to pile up, totalling to $10,802,325.
The Sale
The court-ordered sales process commenced in late-February. According to a report prepared by the Monitor, 15 parties signed confidentiality agreements and five toured the site. One party submitted a letter of intent in June, but reduced their offer during negotiations the following month, citing higher-than-anticipated expected taxes.
The Monitor then engaged other bidders, but could not find a better offer. Feedback from the market was that the project was better suited as a rental building, that the cost to complete was anywhere from $15 million to $30 million, and that the required remedial work was an added level of uncertainty.
“When it became apparent that there would be no unconditional bids,” said the Monitor, Firm Capital then began discussions to buy the project themselves through a reverse vesting order that would see them buy the shares of Hazelton Development Corporation — a share sale — instead of directly buying the real estate. Firm Capital’s purchase agreement also required that the remaining 48 presale contracts be terminated.
The purchase price is equivalent to the sum of various floating amounts, totalling to around $73.5 million, plus $802,000 in cash consideration, for a total of around $74.3 million estimated at September 30, 2026.
The sale approval court hearing was originally scheduled for October 1, but was then delayed due to various stakeholders raising objections. The hearing was delayed to October 22, then October 26, before it was finally approved by the Ontario Superior Court on November 4.