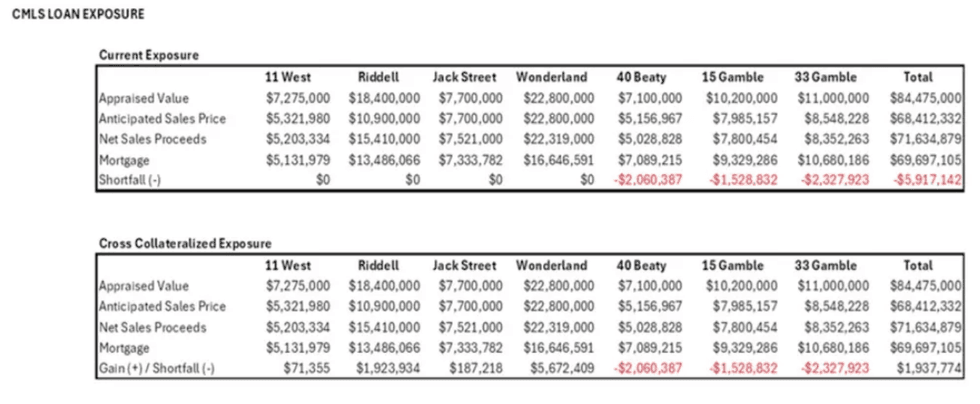
Contingent Liability
Learn about contingent liabilities in Canadian real estate — what they are, how they impact valuations, and why they matter to investors.
August 07, 2025
What is Contingent Liability?
A contingent liability is a potential financial obligation that may occur depending on the outcome of a future event.
Why Contingent Liability Matters in Real Estate
In Canadian real estate, contingent liabilities can arise from legal disputes, environmental remediation obligations, or pending property tax appeals.
Key points:
- Disclosed on financial statements if probable and estimable
- May impact property valuations and lending decisions
- Can include guarantees or pending lawsuits
Understanding contingent liabilities helps investors and lenders evaluate potential risks.
Example of Contingent Liability in Action
The developer disclosed a contingent liability for potential soil contamination cleanup on the property.
Key Takeaways
- Potential obligation dependent on future events
- May affect property valuations and creditworthiness
- Common in environmental, tax, or legal issues
- Must be disclosed if probable and measurable
- Key in risk assessment during transactions
Related Terms
- Environmental Site Assessment
- Record of Site Condition
- Debt Service Ratios
- Due Diligence
- Title Insurance

 Canadian respondents were more likely to expect an undersupply of development/redevelopment equity capital (63%) than debt capital (46%) in 2027. These are survey expectations, not measured financing volumes. Source: PwC and ULI, Emerging Trends in Real Estate 2027, pp. 136–137. Original chart.
 Toronto census metropolitan area housing starts fell from 37,718 units in 2024 to 26,087 in 2025, a 30.8% decline (rounded to 31%). Starts measure construction begun, not completed homes. Source: CMHC, as cited in PwC and ULI, Emerging Trends in Real Estate 2027, p. 145. Original chart.







 Illustrative calculation: a $4.5-million value ceiling versus income-based capacity of about $4.25 million at 4%, $3.62 million at 5% and $3.13 million at 6%. Assumes 50-year amortization and 1.15 debt coverage.
 Source: Department of Finance missing-middle backgrounder and Budget 2026 Chapter 3, November 5, 2026. Fiscal-year funding starts are not home-completion dates.