Second Mortgage
Learn what a second mortgage is in Canadian real estate, how it works, and what homeowners should consider when borrowing against home equity.
May 29, 2025
What is a Second Mortgage?
A second mortgage is a loan secured against a property that already has a first (primary) mortgage, allowing the homeowner to borrow additional funds using home equity.
Why a Second Mortgage Matters in Real Estate
In Canadian real estate, second mortgages are used for renovations, debt consolidation, investments, or accessing liquidity without refinancing the original mortgage.
Key characteristics include:- Higher interest rates than first mortgages
- Shorter terms and interest-only options
- Must be registered in second position on title
If the homeowner defaults, the first mortgage lender is paid before the second lender. Borrowers should assess repayment capacity and the impact on overall debt.
Example of a Second Mortgage
A homeowner takes out a $60,000 second mortgage to renovate their kitchen while keeping their low-interest first mortgage intact.
Key Takeaways
- Loan secured by equity behind first mortgage.
- Higher interest due to greater risk.
- Used for renovations or debt consolidation.
- Adds to total property debt load.
- Requires careful planning and registration.
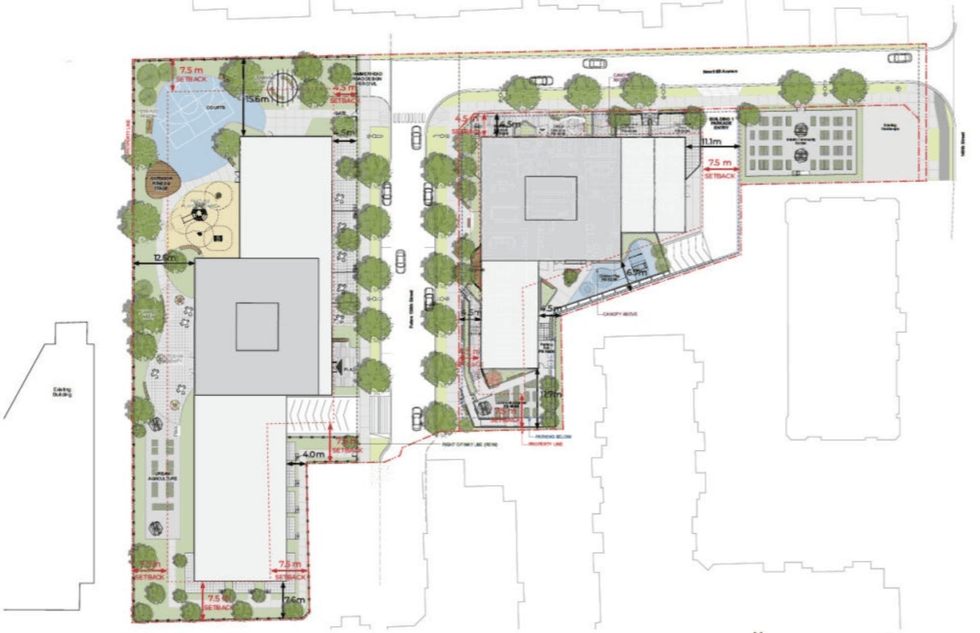
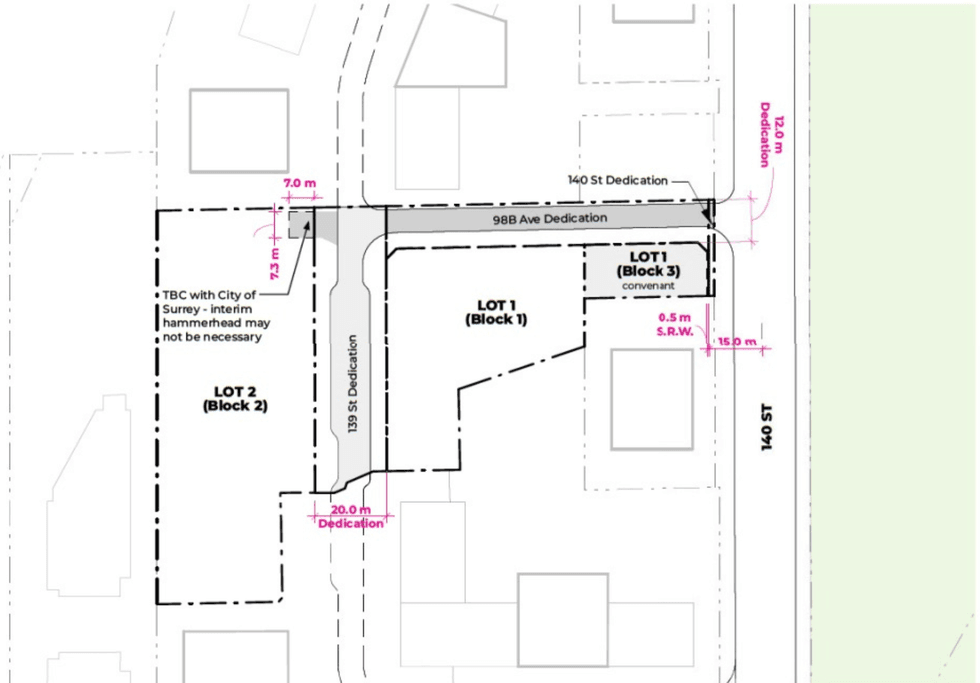 9883 140 Street and the proposed road dedications. (WW+P Architects, Entre Nous Femmes Housing Society)
 The
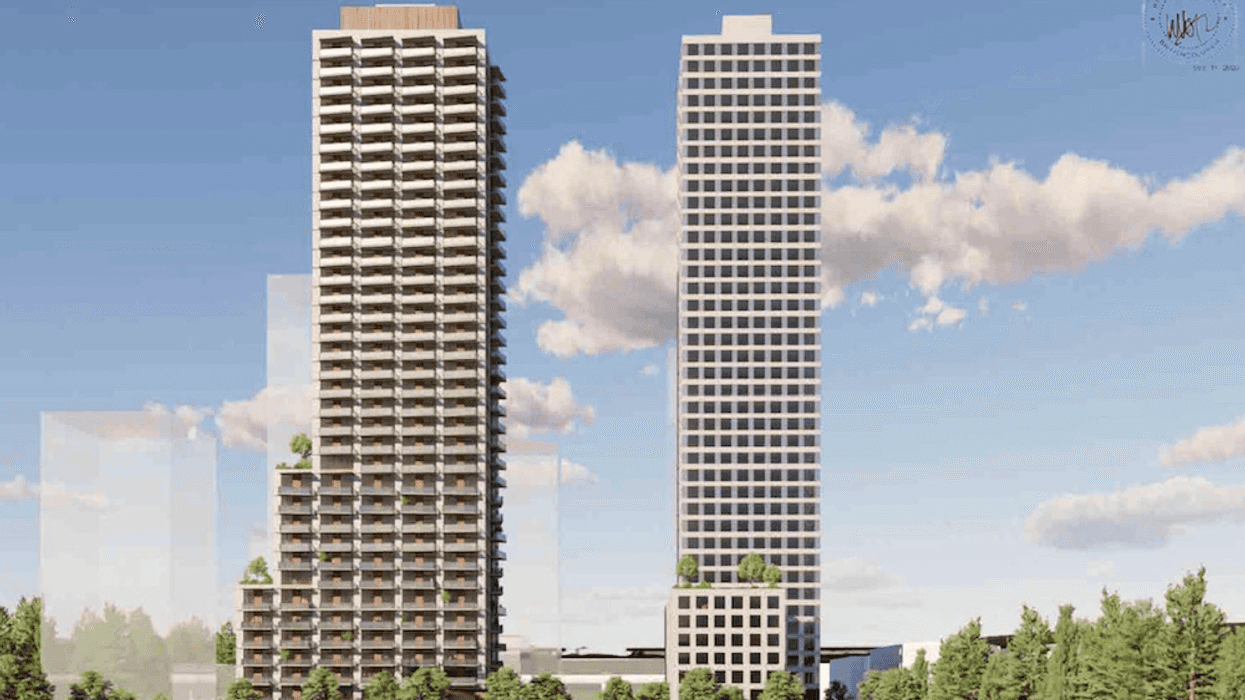
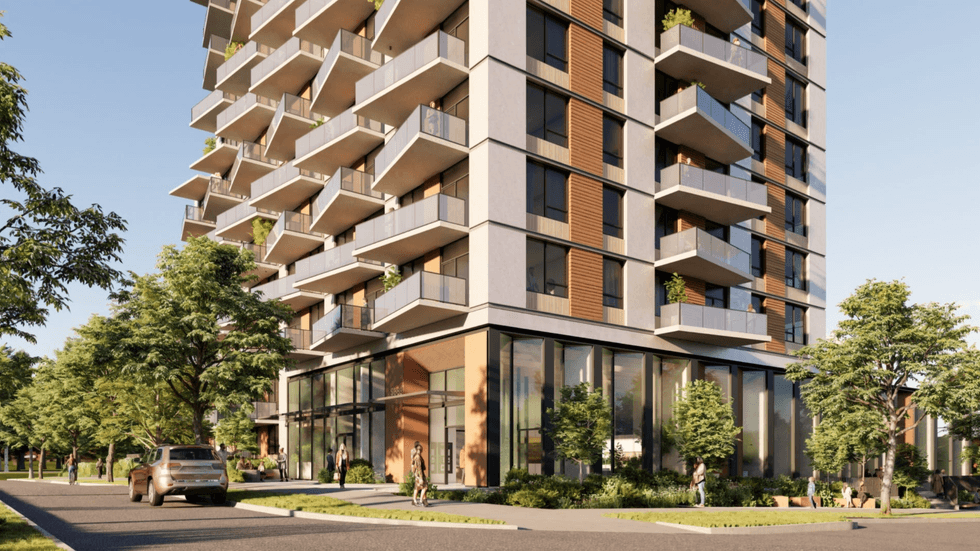 One of the towers proposed for 9883 140 Street. (Entres Nous Femmes Housing Society)




 Canadian respondents were more likely to expect an undersupply of development/redevelopment equity capital (63%) than debt capital (46%) in 2027. These are survey expectations, not measured financing volumes. Source: PwC and ULI, Emerging Trends in Real Estate 2027, pp. 136–137. Original chart.
 Toronto census metropolitan area housing starts fell from 37,718 units in 2024 to 26,087 in 2025, a 30.8% decline (rounded to 31%). Starts measure construction begun, not completed homes. Source: CMHC, as cited in PwC and ULI, Emerging Trends in Real Estate 2027, p. 145. Original chart.




 Illustrative calculation: a $4.5-million value ceiling versus income-based capacity of about $4.25 million at 4%, $3.62 million at 5% and $3.13 million at 6%. Assumes 50-year amortization and 1.15 debt coverage.
 Source: Department of Finance missing-middle backgrounder and Budget 2026 Chapter 3, November 5, 2026. Fiscal-year funding starts are not home-completion dates.
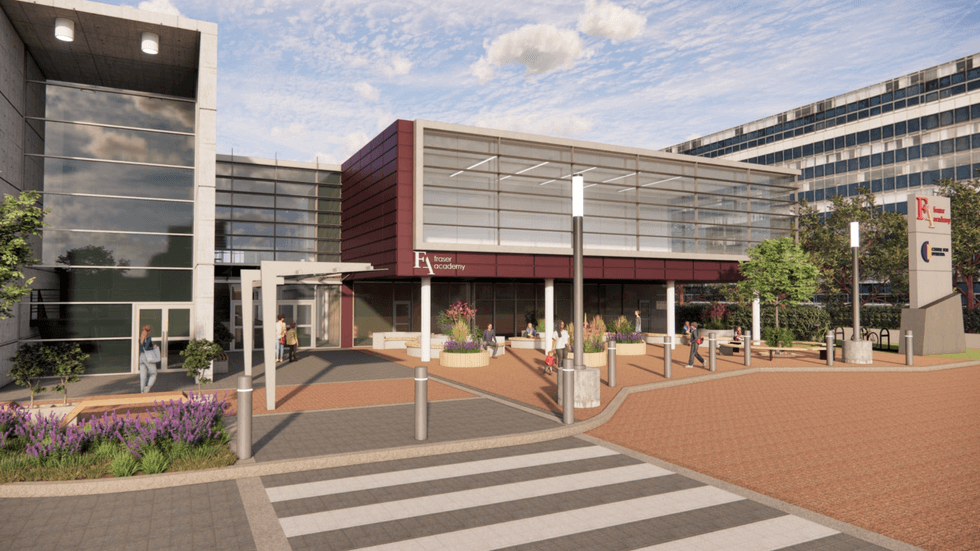 A rendering of Fraser Academy’s new campus. (Fraser Academy)
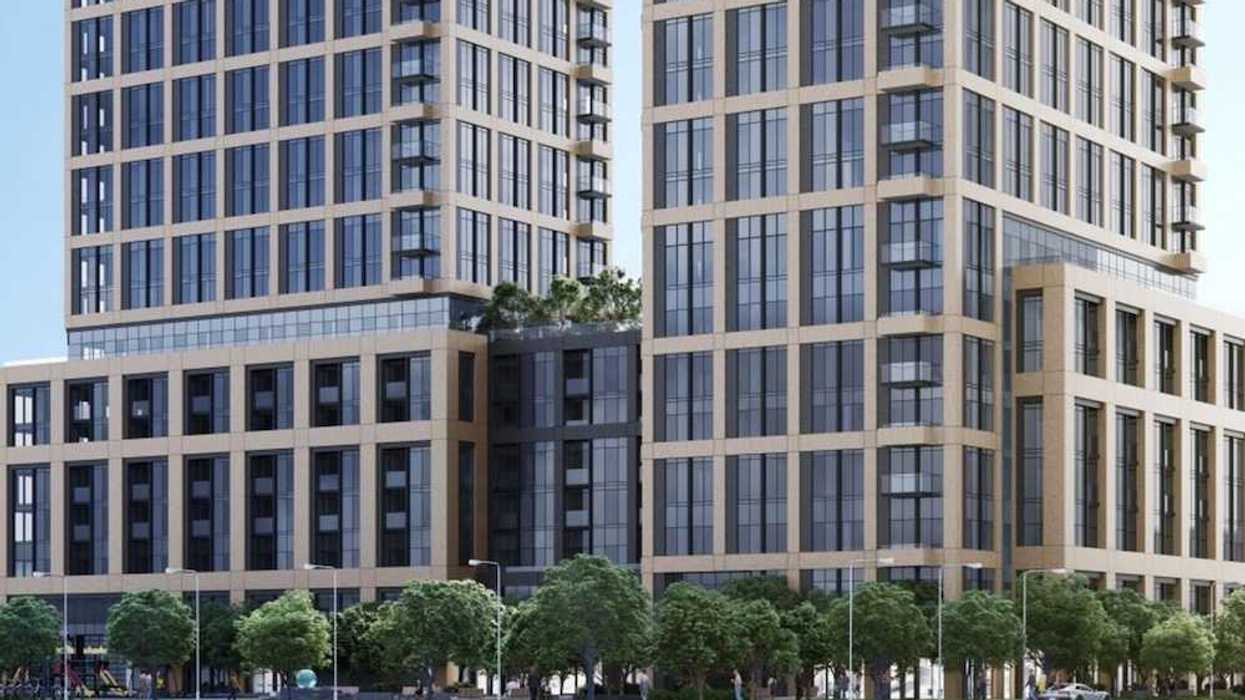
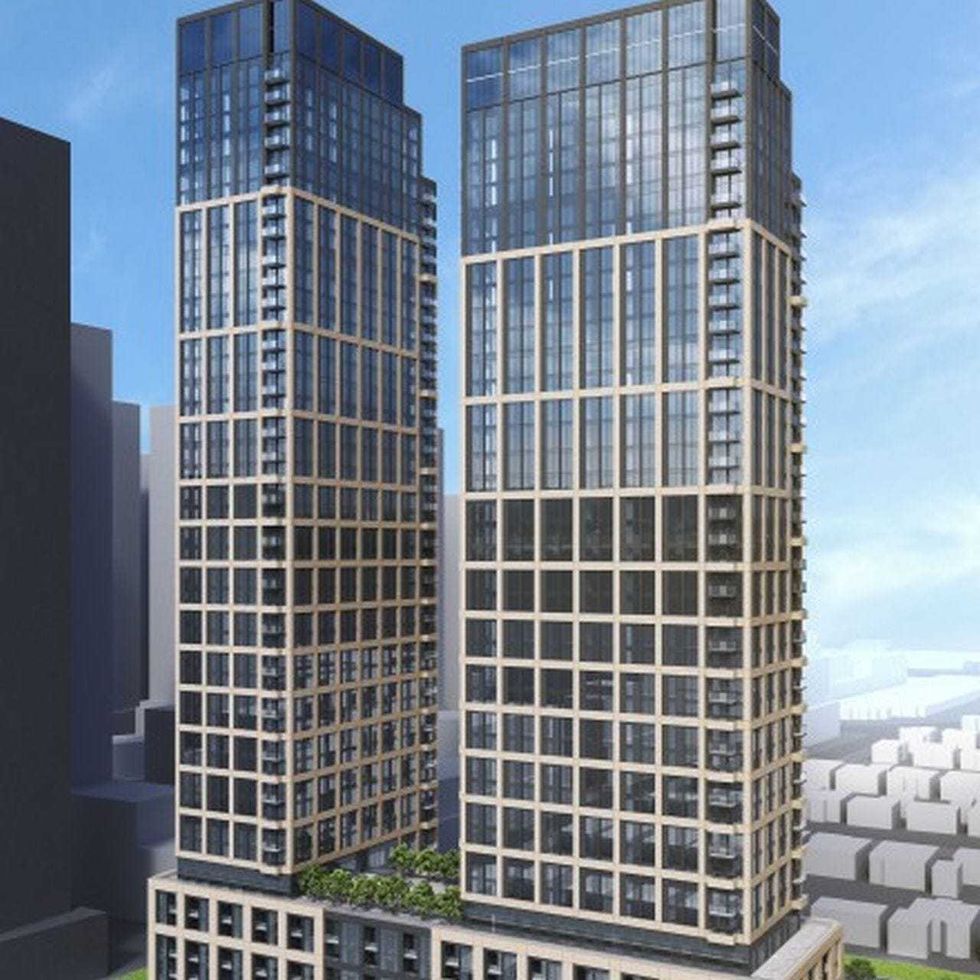 The project planned for 36-48 Steeles Avenue East and 37-49 Highland Park Boulevard in Markham. (Arcadis, Zonix Homes)