Insurance Appraisal
Learn what an insurance appraisal is in Canadian real estate, how it's calculated, and why it’s essential for setting proper property coverage limits.
May 22, 2025
What is an Insurance Appraisal?
An insurance appraisal is a professional valuation of a property used to determine the appropriate amount of insurance coverage needed for rebuilding or replacement in the event of a loss.
Why Insurance Appraisals Matter in Real Estate
In Canadian real estate, insurance appraisals ensure homeowners, condo corporations, and lenders have accurate coverage based on the property's construction, age, features, and materials—not its market value
Key features include:- Reflects rebuilding cost (not resale value)
- Conducted by certified appraisers
- Required for condo reserve planning and lender underwriting
Outdated or missing appraisals can result in underinsurance, leaving property owners exposed to financial loss.
Understanding insurance appraisals helps property owners secure adequate protection and comply with legal and mortgage requirements.
Example of an Insurance Appraisal in Action
A condo board commissions an insurance appraisal to verify the replacement cost of the building for its annual policy renewal.
Key Takeaways
- Determines rebuilding cost for insurance.
- Used for residential and condo policies.
- Conducted by certified professionals.
- Different from market appraisals.
- Prevents underinsurance.
Related Terms
- Replacement Cost
- Actual Cash Value
- Home Insurance
- Coverage Limit
- Reserve Fund
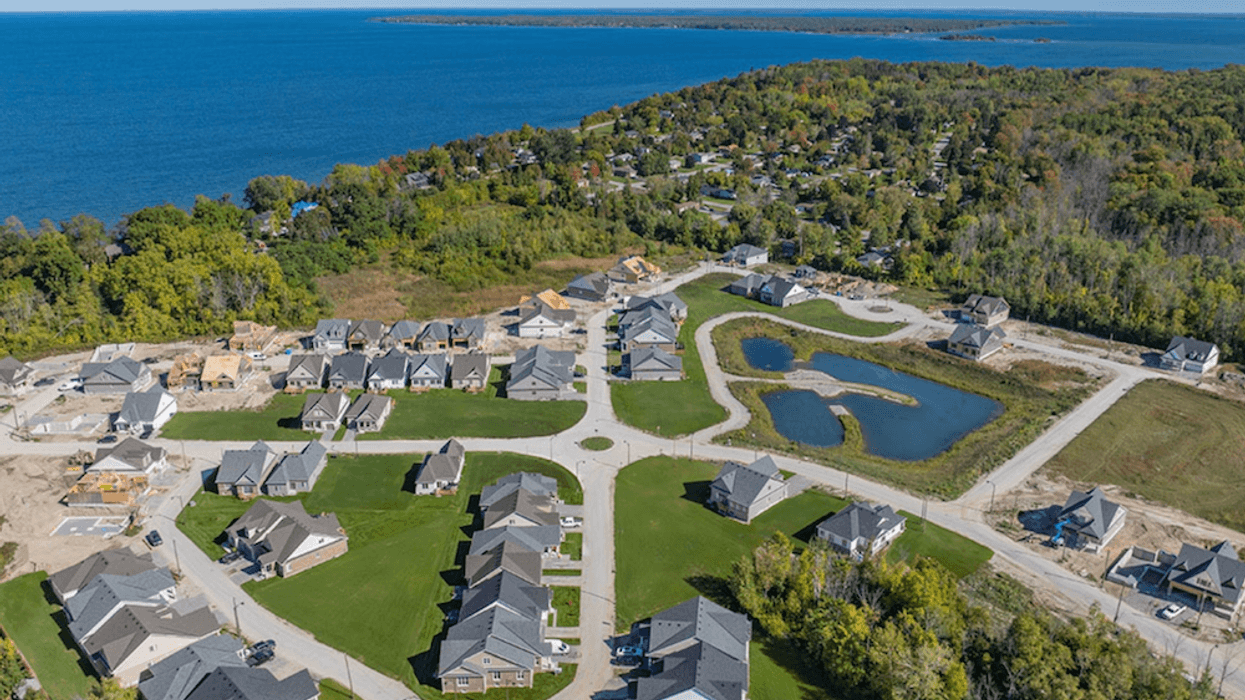
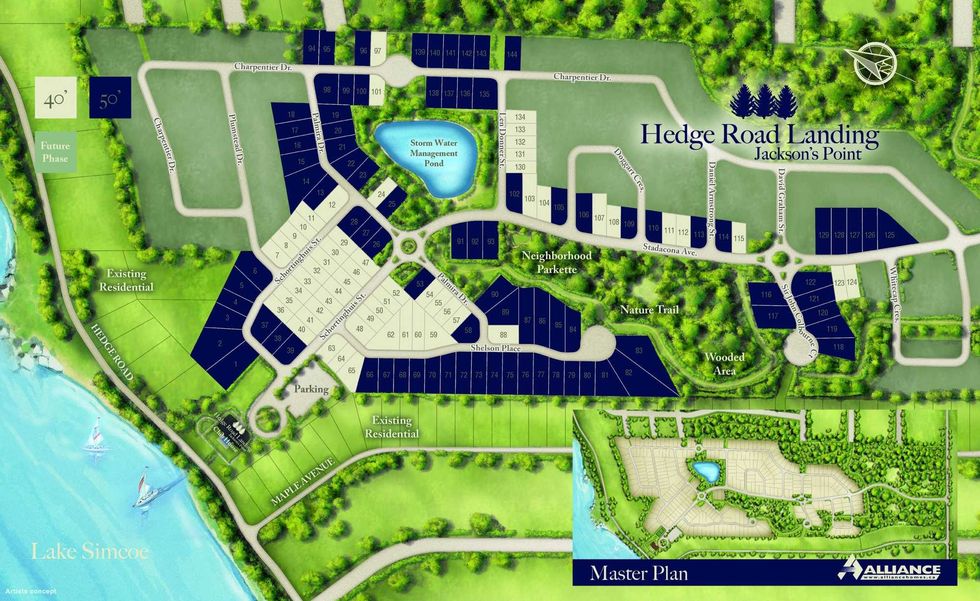 An overview of Hedge Road Landing. (Alliance Homes)
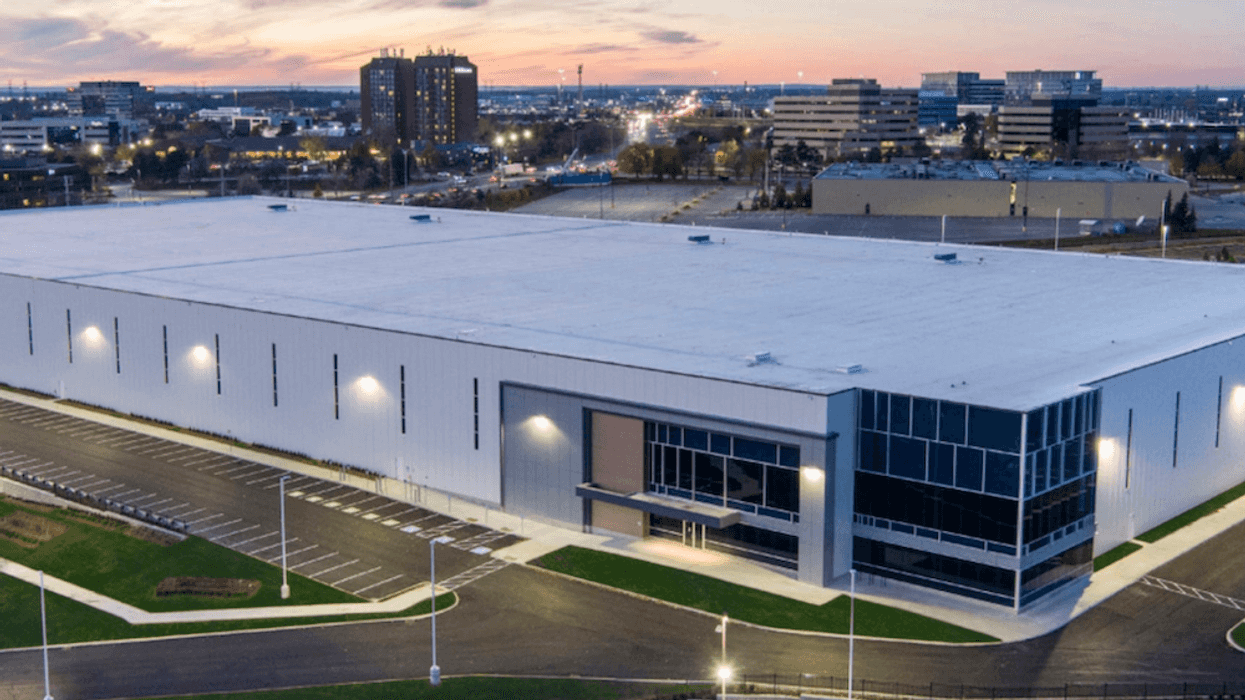
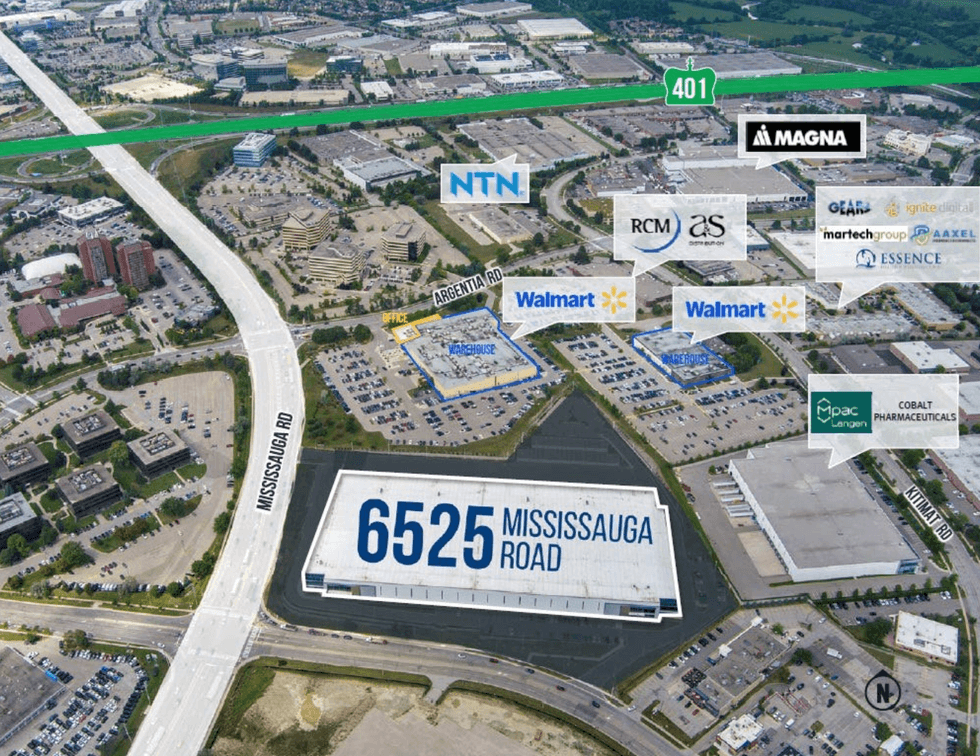 6525 Mississauga Road and its surrounding context. (RBC Capital Markets & CBRE)
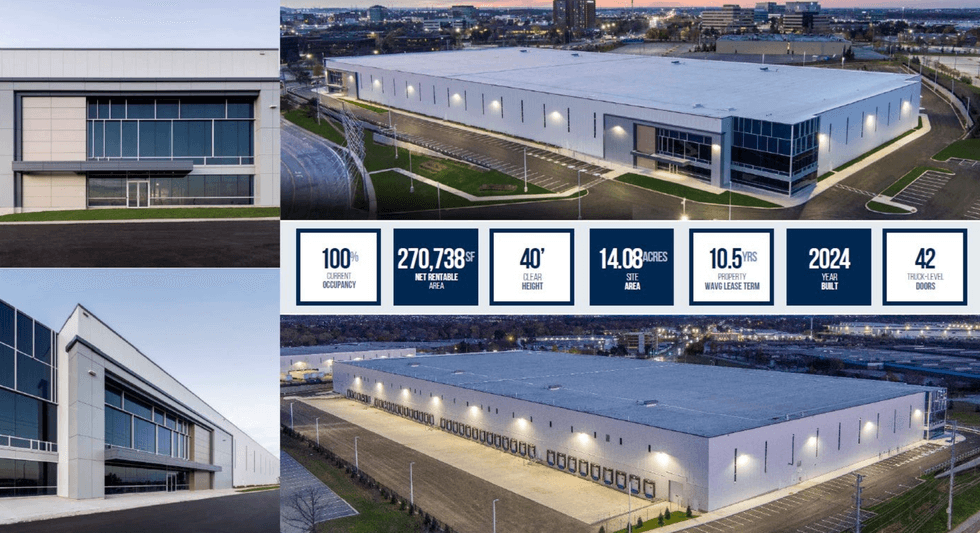 Property details for 6525 Mississauga Road. (RBC Capital Markets & CBRE)
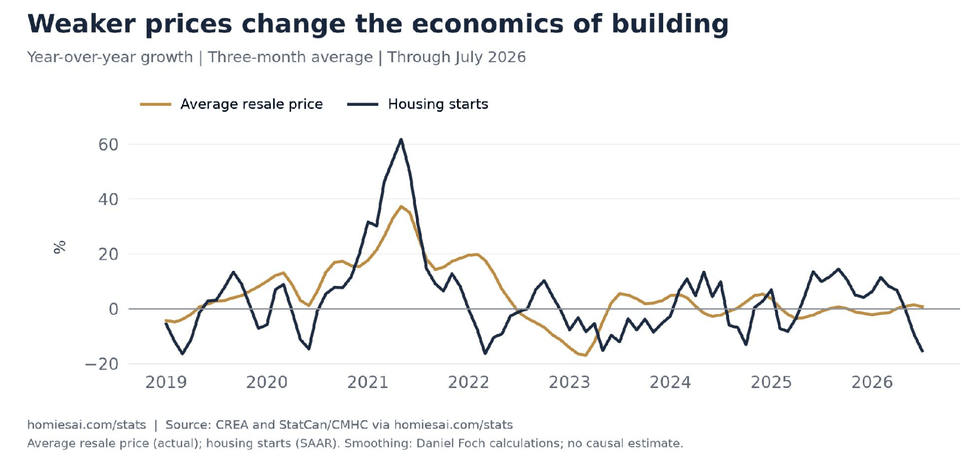 National average resale-price growth and housing-starts growth, smoothed over three months. The comparison illustrates the cycle; it does not establish how much a price change causes construction to change.
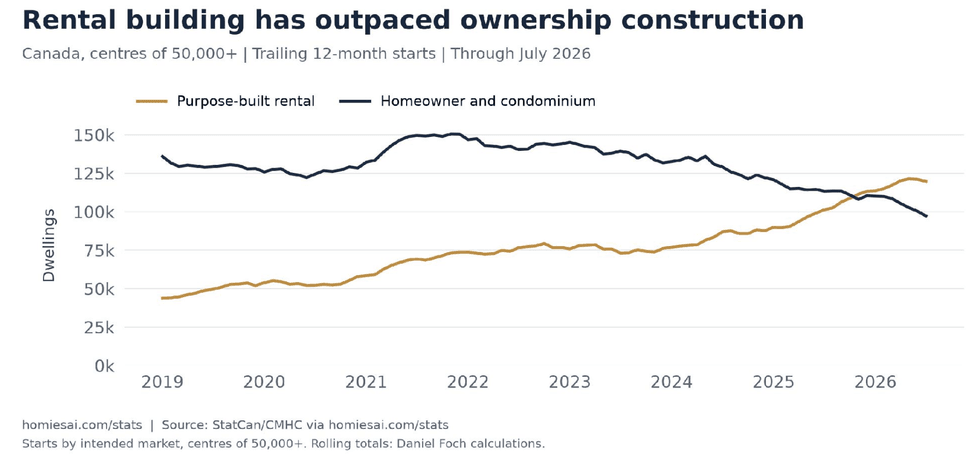 Trailing 12-month starts in centres of 50,000 or more remove the usual monthly seasonality. Ownership combines the homeowner and condominium categories; rental is shown separately.
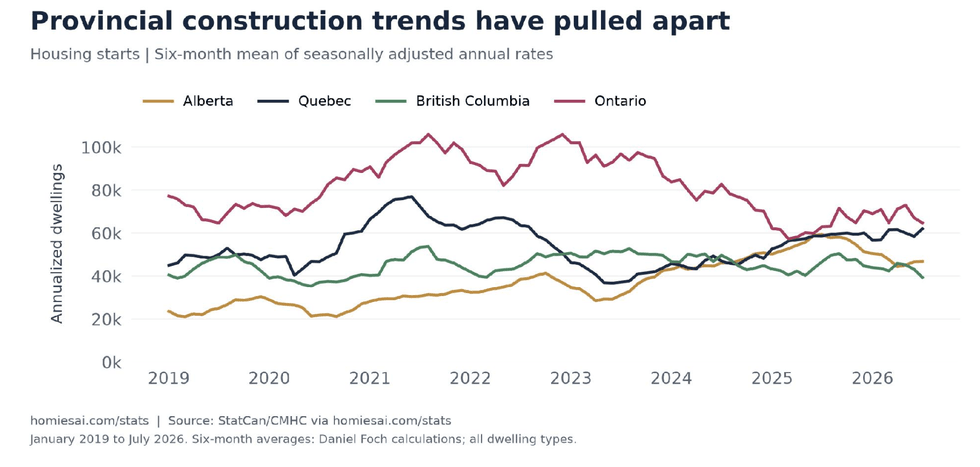 Six-month averages of provincial starts, expressed at annual rates. The smoothing reduces the influence of individual apartment projects.
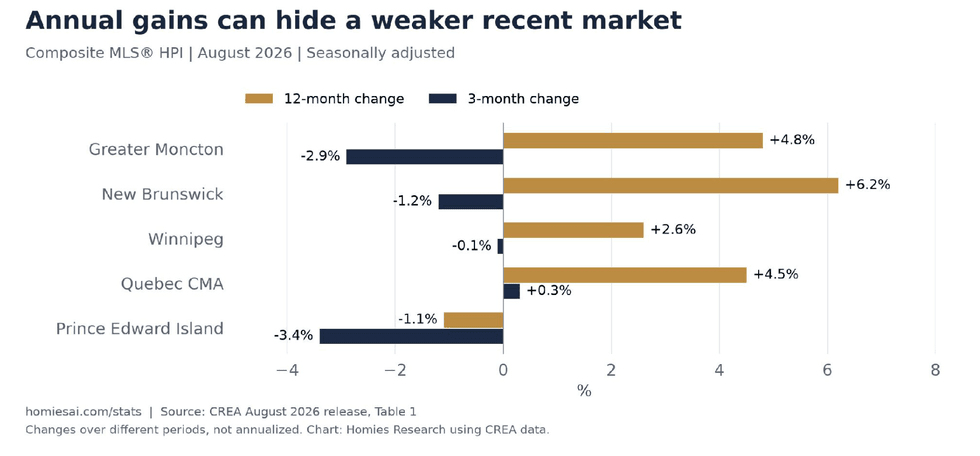 The same August benchmark compared with two different starting points. Three-month changes are not annualized.
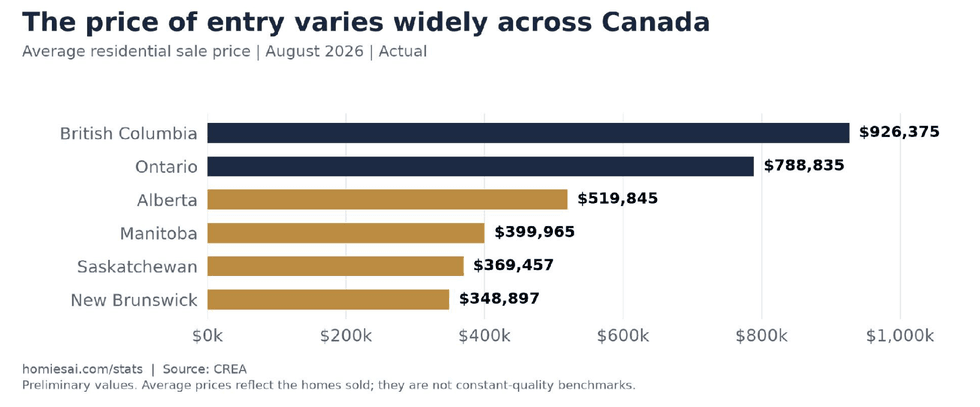 Average sale prices show the difference in purchase costs across markets. They do not measure affordability relative to local incomes or construction costs.
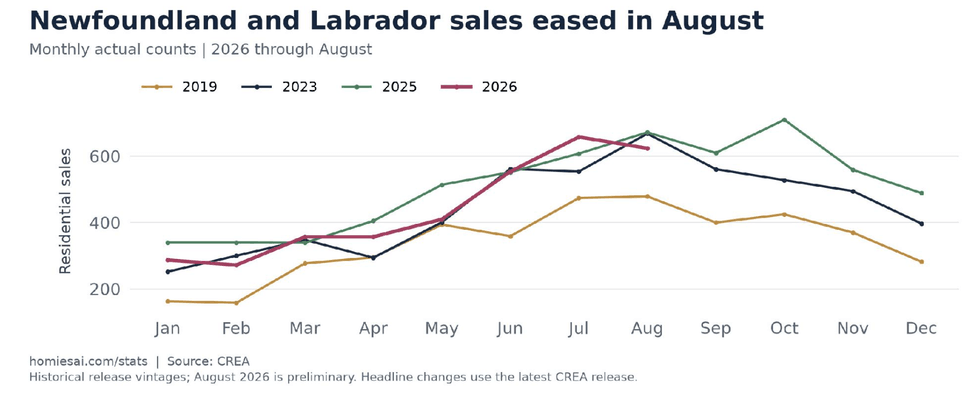 Newfoundland and Labrador remains above its pre-pandemic sales pattern, but August activity was below last year. Historical lines retain their original release vintages.
 Galleria III at Galleria on the Park (Hariri Pontarini Architects)
 Bisha Hotel & Residences (Lifetime Developments)