Home Equity Loan
Explore how home equity loans work in Canada, when to use them, and how to borrow responsibly against your property’s value.
National Bank
May 22, 2025
What is a Home Equity Loan?
A home equity loan is a type of loan where homeowners borrow against the equity they've built in their property, using the home as collateral.
Why Home Equity Loans Matter in Real Estate
In Canadian real estate, home equity loans are useful tools for accessing large sums of money at relatively low interest rates. Equity is calculated as the current market value of the property minus any outstanding mortgage balance.
These loans are typically used for:- Home renovations
- Debt consolidation
- Education expenses
- Large purchases
Home equity loans usually come with fixed interest rates and repayment terms, making them predictable and easier to budget than lines of credit. However, because the home is used as collateral, failure to repay the loan could result in foreclosure or power of sale.
Lenders generally allow borrowing up to 80% of the home’s appraised value, including the mortgage. Qualification depends on credit score, income, and the amount of existing debt.
Understanding home equity loans helps homeowners leverage their assets responsibly without overextending their finances.
Example of a Home Equity Loan?
A homeowner with $300,000 in equity borrows $50,000 through a home equity loan to renovate their kitchen and bathrooms.
Key Takeaways
- Borrow against built-up home equity.
- Fixed interest and repayment terms.
- Used for major expenses or debt reduction.
- Home is collateral—risk if unpaid.
- Must meet lender eligibility criteria.
Related Terms
- HELOC
- Equity
- Mortgage Refinancing
- Secured Loan
- Debt Consolidation
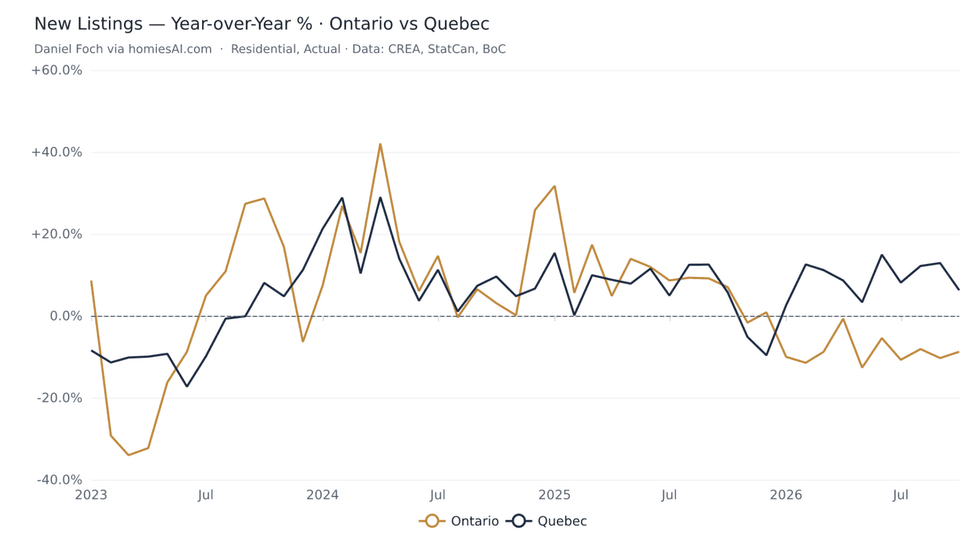 Chart: New listings, year-over-year %, Ontario vs Quebec. Daniel Foch via homiesai.com/stats. Data:
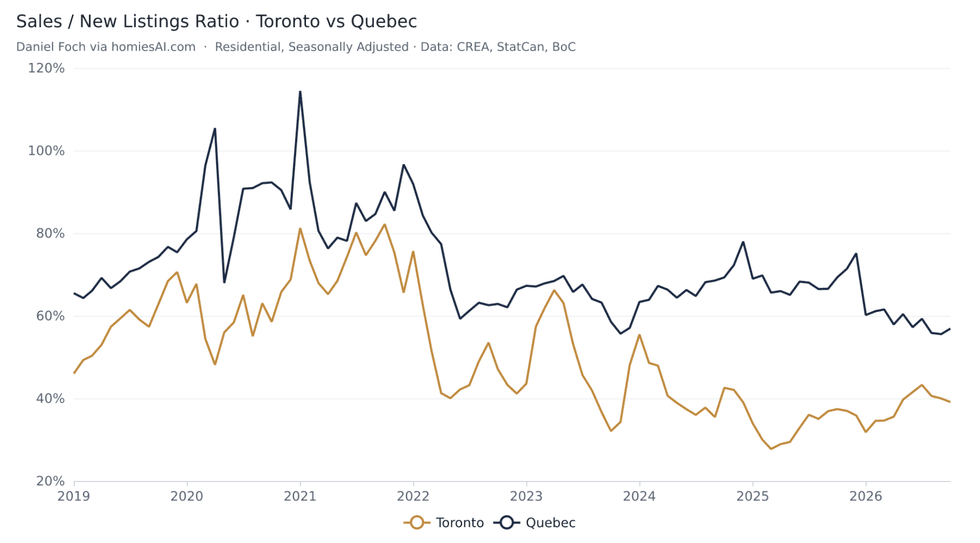 Chart: Sales-to-new-listings ratio, seasonally adjusted. Toronto vs Quebec. Daniel Foch via homiesai.com/stats. Data: CREA.
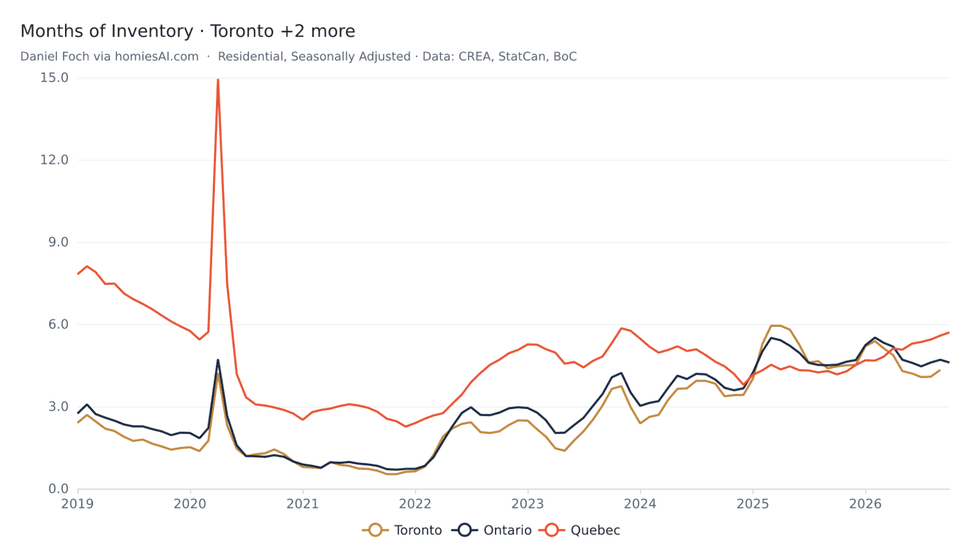 Chart: Months of inventory, seasonally adjusted. Daniel Foch via homiesai.com/stats. Data: CREA.
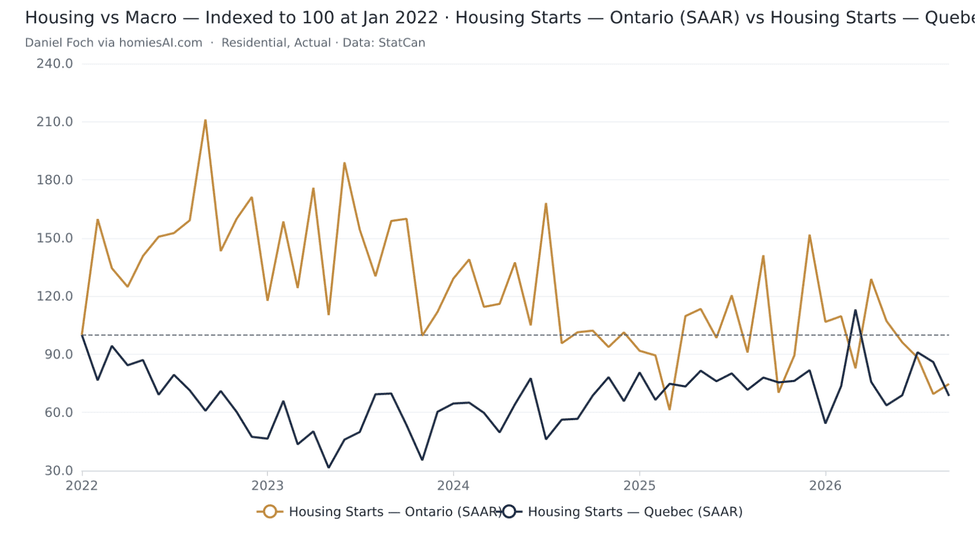 Chart: Housing starts, seasonally adjusted annual rate, Ontario vs Quebec, indexed to January 2022. Daniel Foch via homiesai.com/stats. Data: CMHC via Statistics Canada.
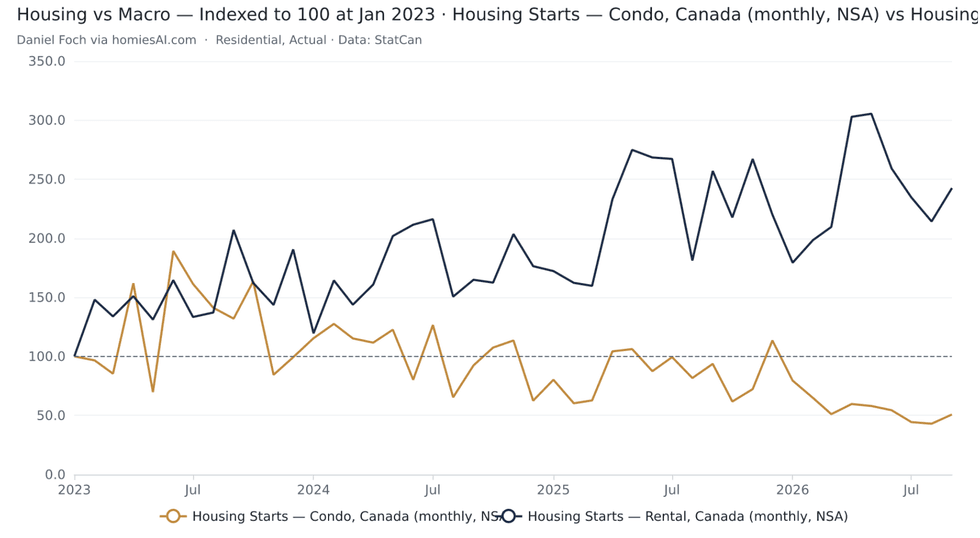 Chart: Condo vs rental housing starts, Canada, indexed to January 2023. Daniel Foch via homiesai.com/stats. Data: CMHC via Statistics Canada.
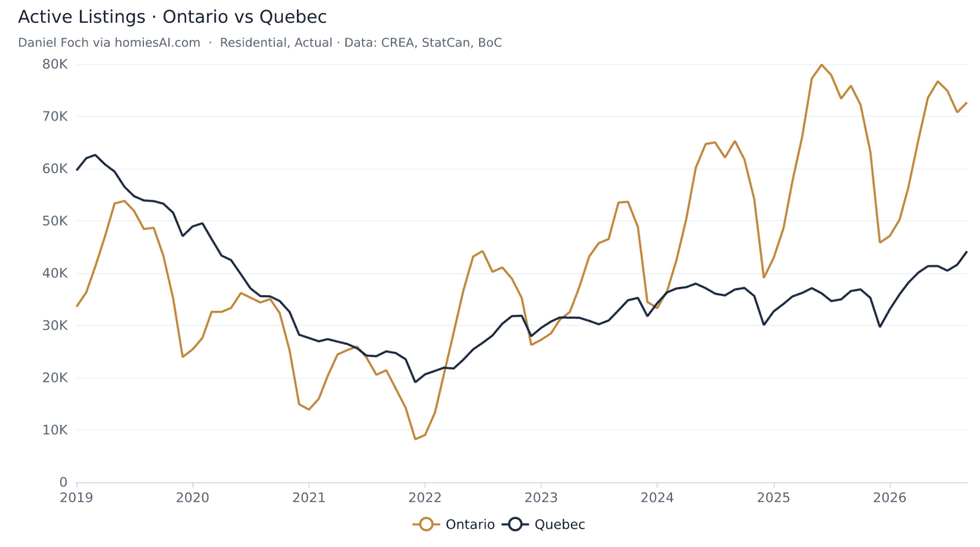 Chart: Active residential listings, Ontario vs Quebec. Daniel Foch via homiesai.com/stats. Data: CREA.



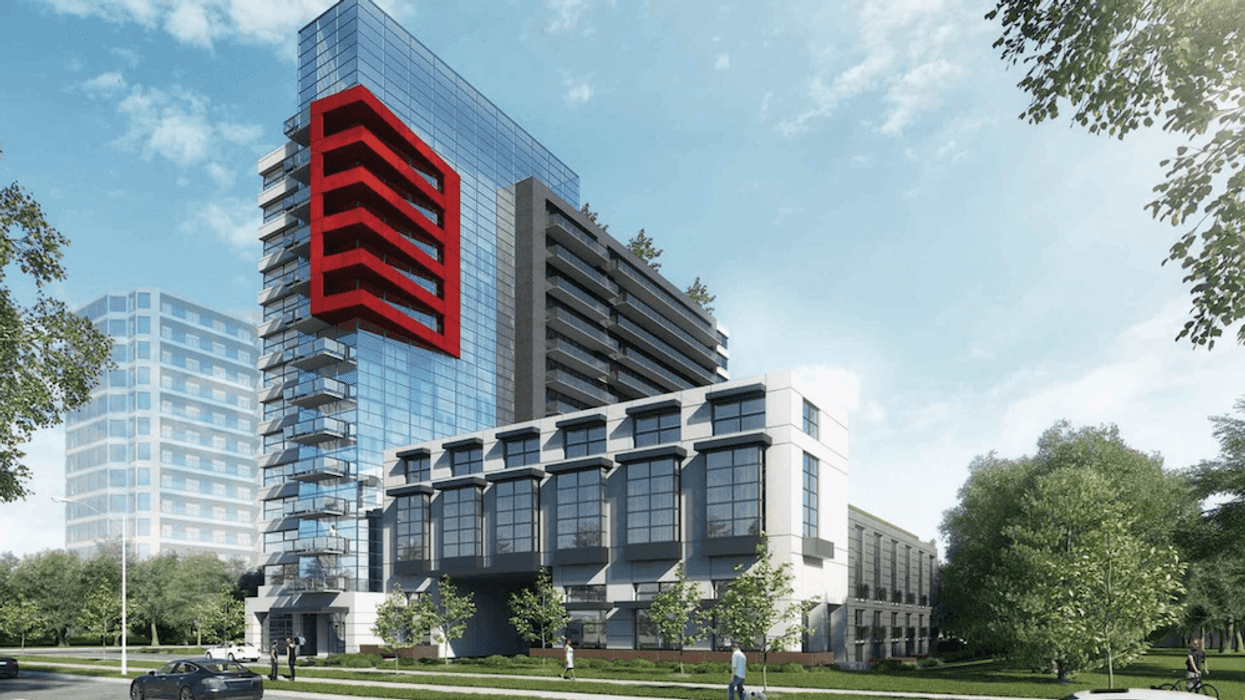
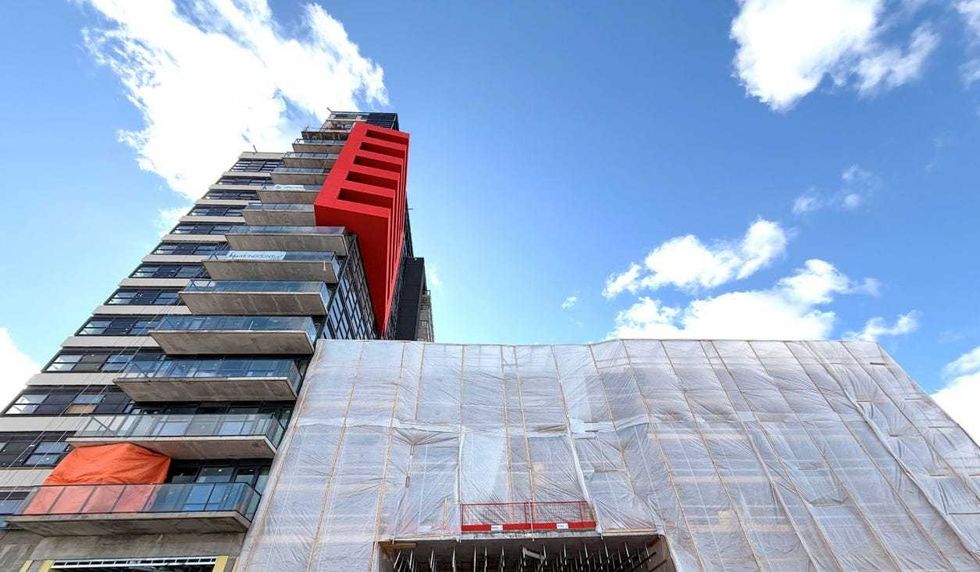 The Highlight of Mississauga as of March 2026. (Grant Thornton)
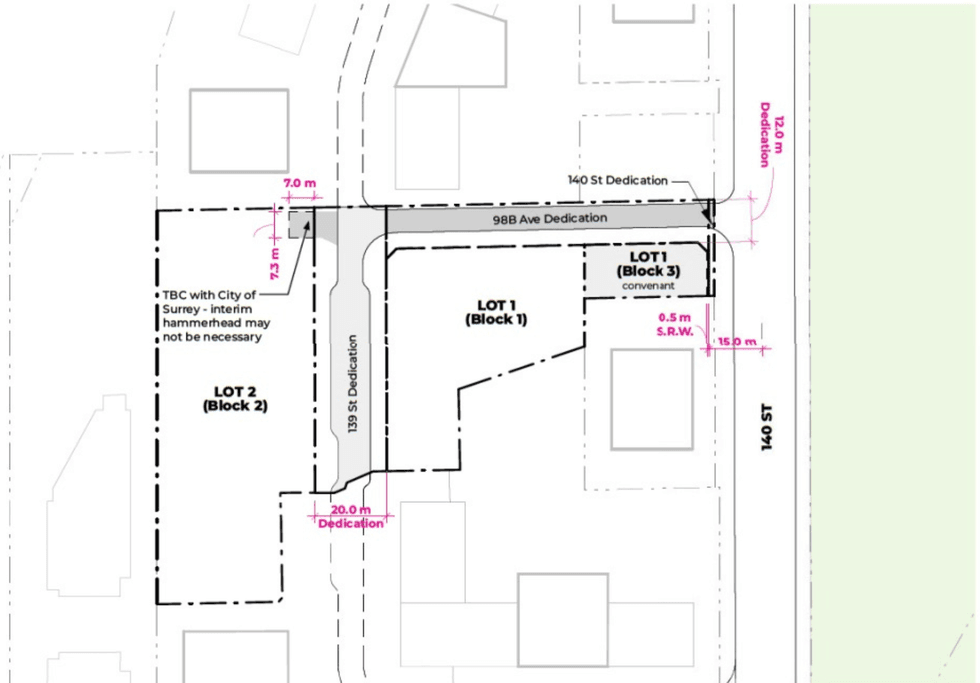 9883 140 Street and the proposed road dedications. (WW+P Architects, Entre Nous Femmes Housing Society)
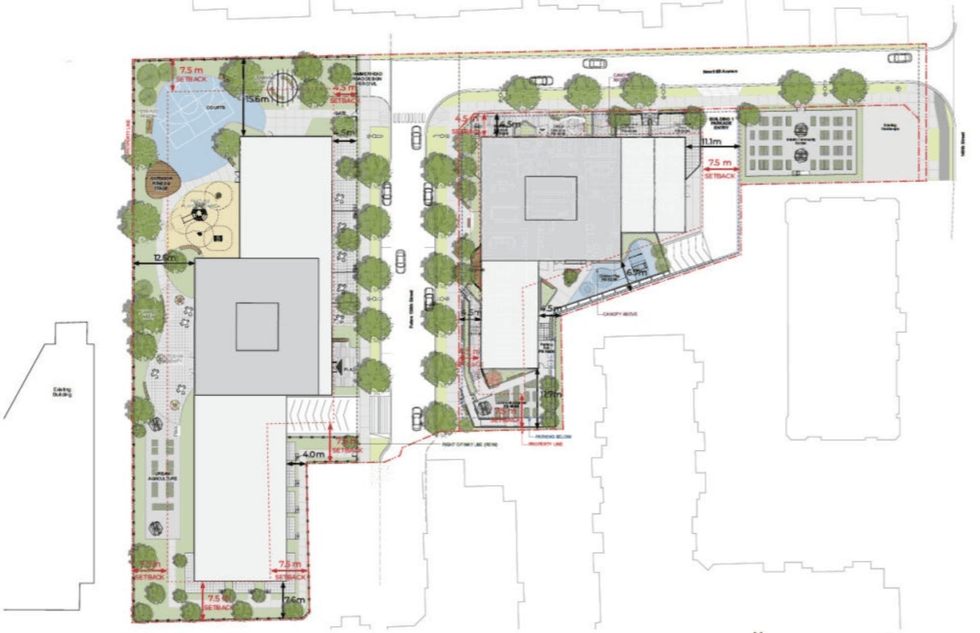 The
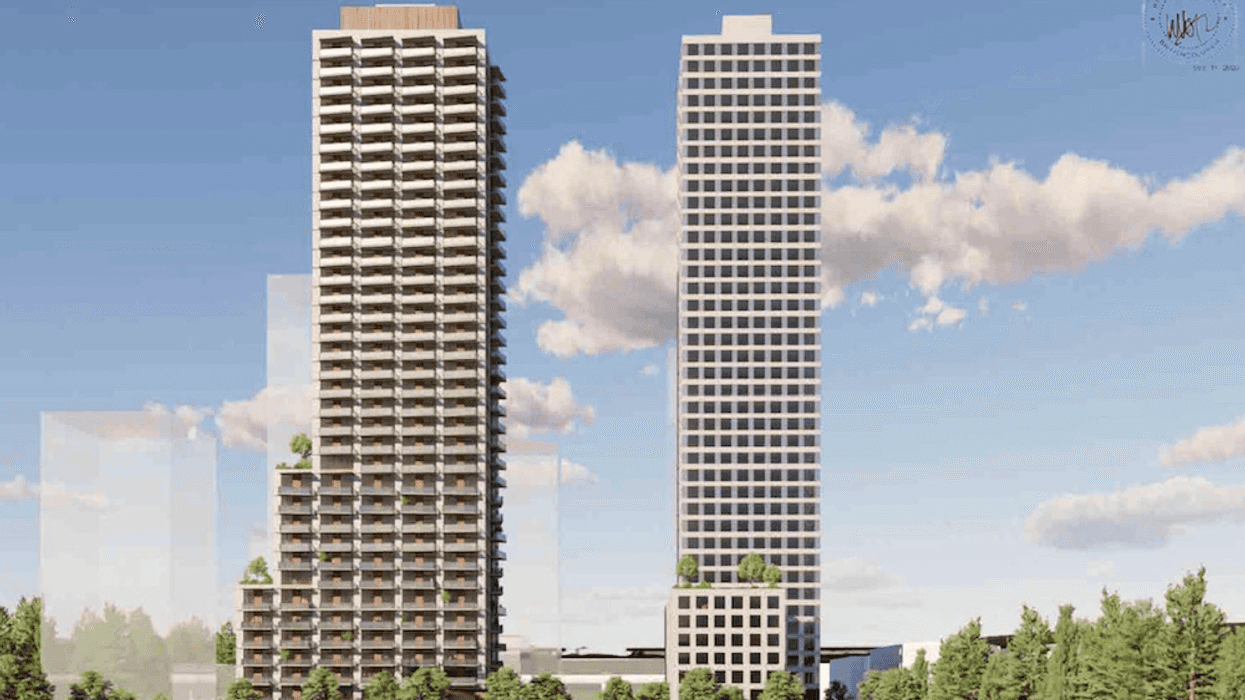
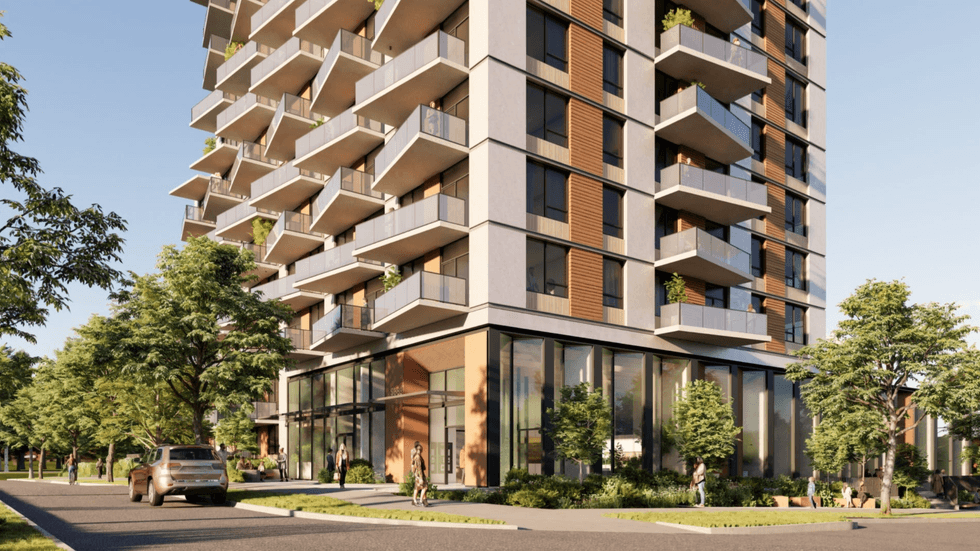 One of the towers proposed for 9883 140 Street. (Entres Nous Femmes Housing Society)

 Canadian respondents were more likely to expect an undersupply of development/redevelopment equity capital (63%) than debt capital (46%) in 2027. These are survey expectations, not measured financing volumes. Source: PwC and ULI, Emerging Trends in Real Estate 2027, pp. 136–137. Original chart.
 Toronto census metropolitan area housing starts fell from 37,718 units in 2024 to 26,087 in 2025, a 30.8% decline (rounded to 31%). Starts measure construction begun, not completed homes. Source: CMHC, as cited in PwC and ULI, Emerging Trends in Real Estate 2027, p. 145. Original chart.




 Illustrative calculation: a $4.5-million value ceiling versus income-based capacity of about $4.25 million at 4%, $3.62 million at 5% and $3.13 million at 6%. Assumes 50-year amortization and 1.15 debt coverage.
 Source: Department of Finance missing-middle backgrounder and Budget 2026 Chapter 3, November 5, 2026. Fiscal-year funding starts are not home-completion dates.