Financing Condition
Learn what a financing condition is in Canadian real estate, how it protects buyers, and why it’s important when making offers on property.
May 22, 2025
What is a Financing Condition?
A financing condition is a clause in a real estate purchase agreement that makes the offer contingent on the buyer securing mortgage approval within a set timeframe.
Why Financing Conditions Matter in Real Estate
In Canadian real estate, the financing condition protects buyers by giving them time—usually 3 to 5 business days—to obtain a mortgage commitment without risking their deposit.If financing is not secured:
- The buyer can back out with no penalty
- The deposit is refunded in full
Understanding the financing condition ensures buyers make informed decisions about risk tolerance, offer strength, and financial readiness.
Example of Financing Condition
A buyer includes a five-day financing condition in their offer, allowing time to receive final approval before committing to the purchase.
Key Takeaways
- Gives buyers time to secure financing.
- Allows withdrawal without penalty.
- Standard in most residential deals.
- Waiving increases risk.
- Part of offer negotiation strategy.
Related Terms
- Conditional Offer
- Firm Offer
- Mortgage Pre-Approval
- Buyer Risk
- Deposit
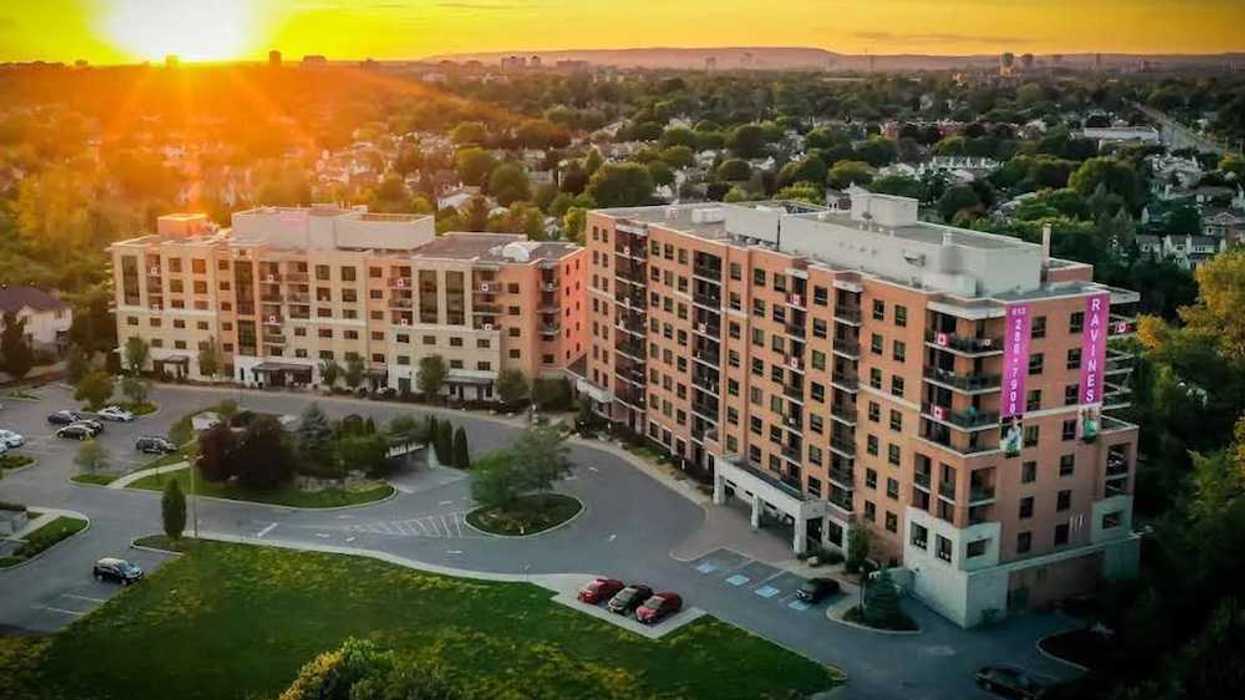
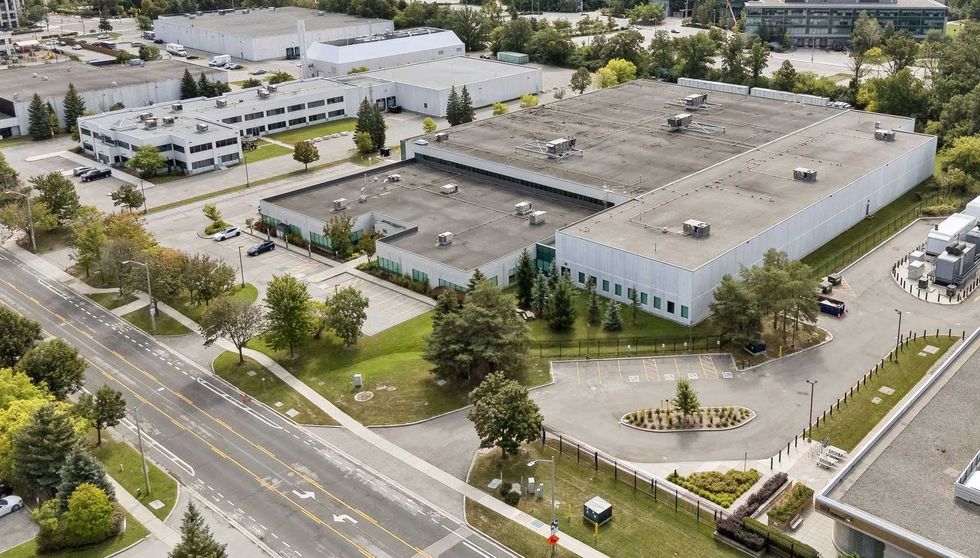
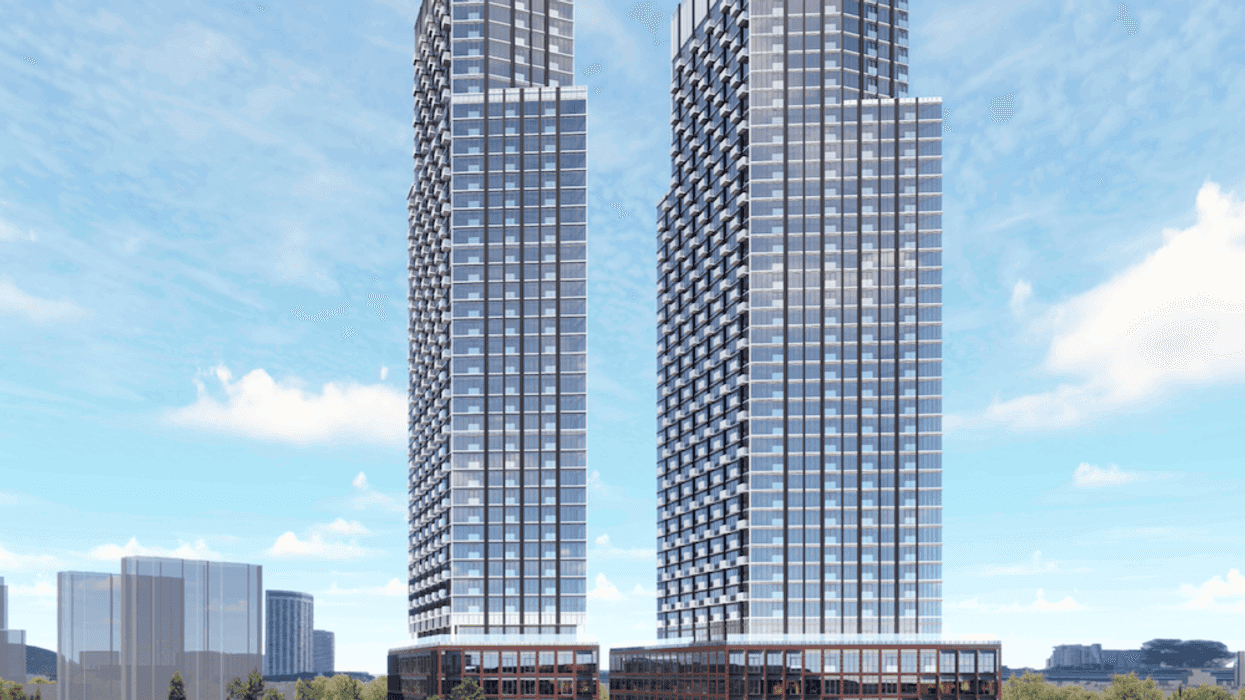
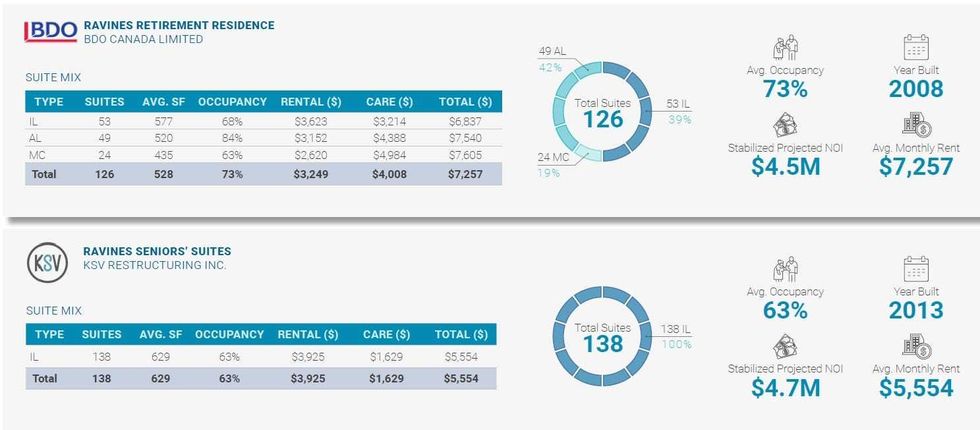 An overview of the two Ravine buildings. (Newmark)
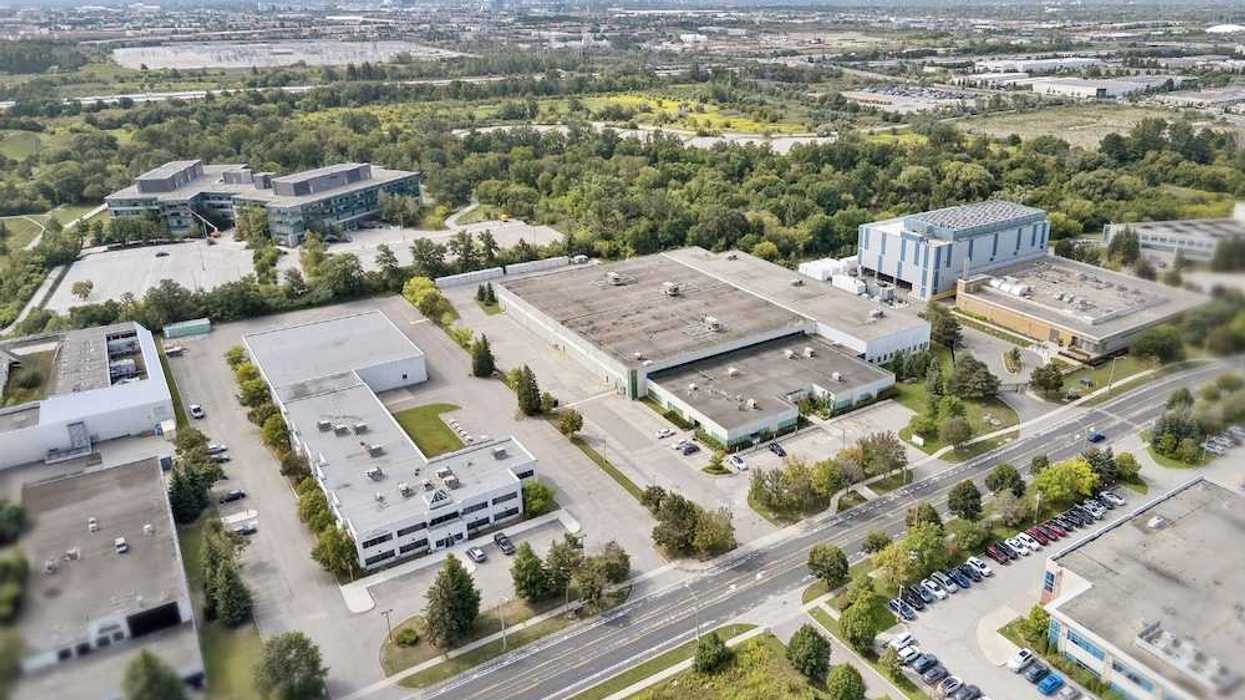
 95 Clegg Road in Markham, Ontario. (Colliers)
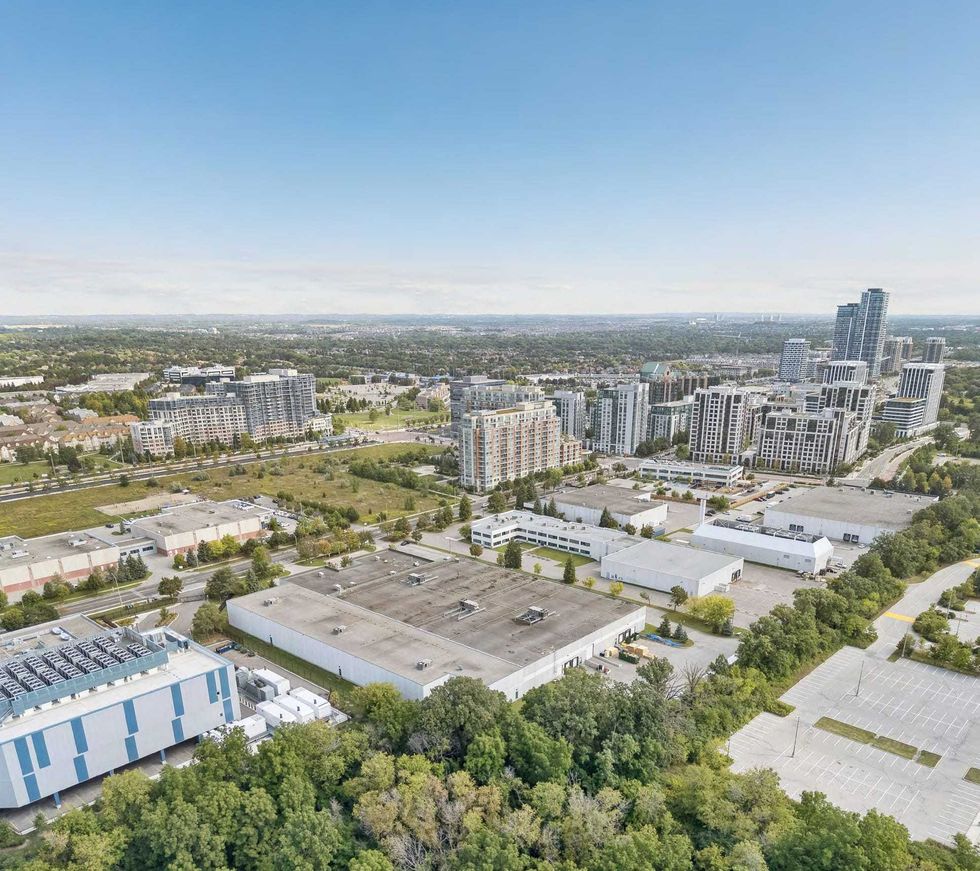 95 Clegg Road (centre) in Markham, Ontario. (Colliers)
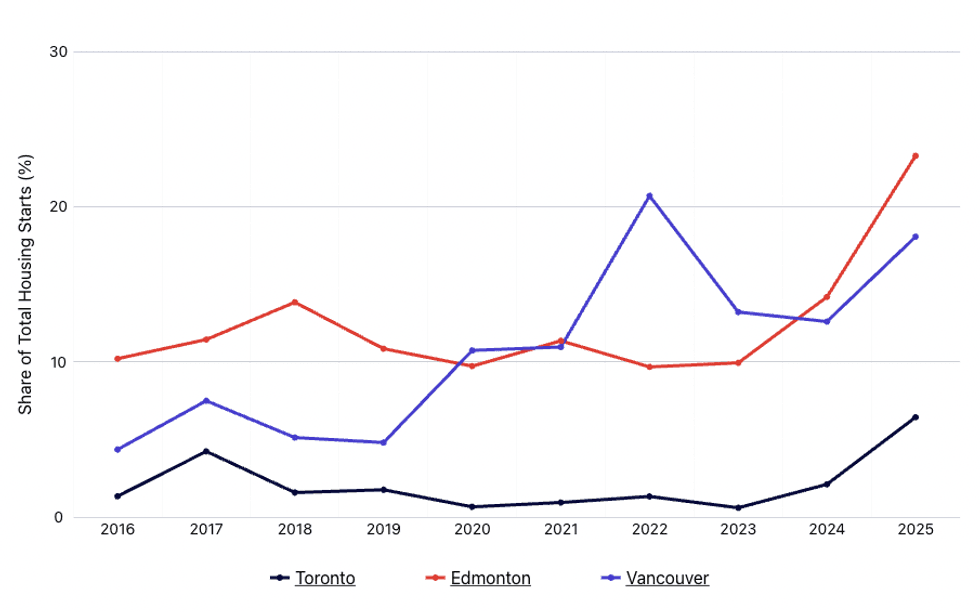 Small-scale infill share of housing starts in Toronto, Vancouver, and Edmonton/CMHC
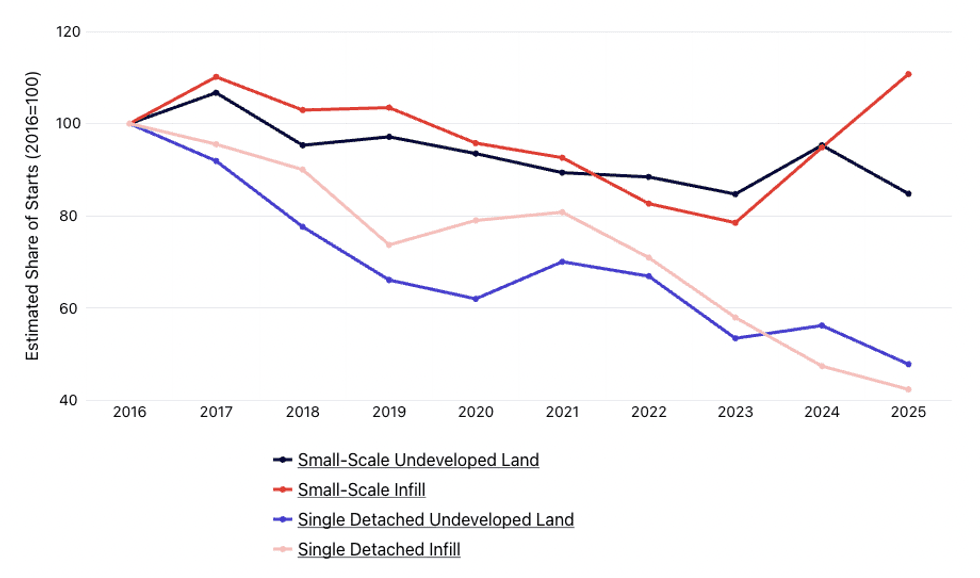 Housing starts for one to eight unit developments/CMHC
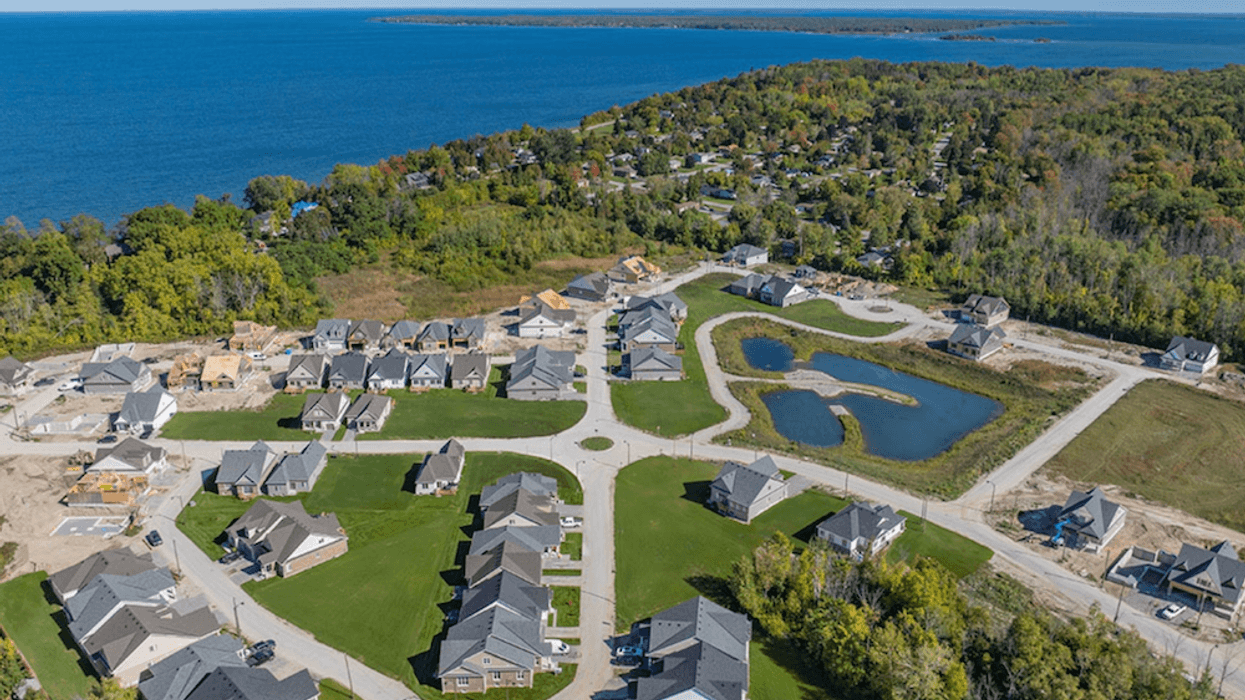
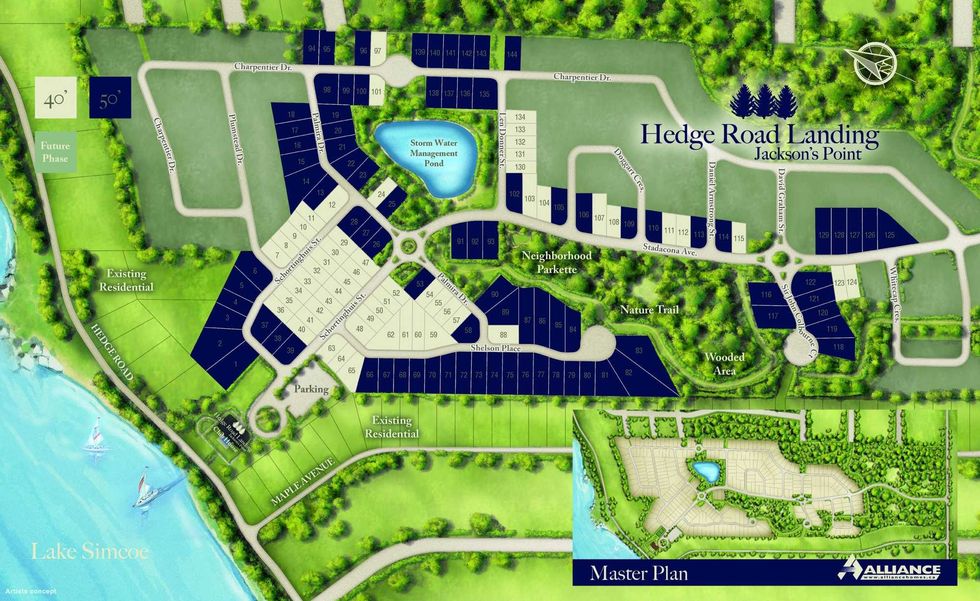 An overview of Hedge Road Landing. (Alliance Homes)
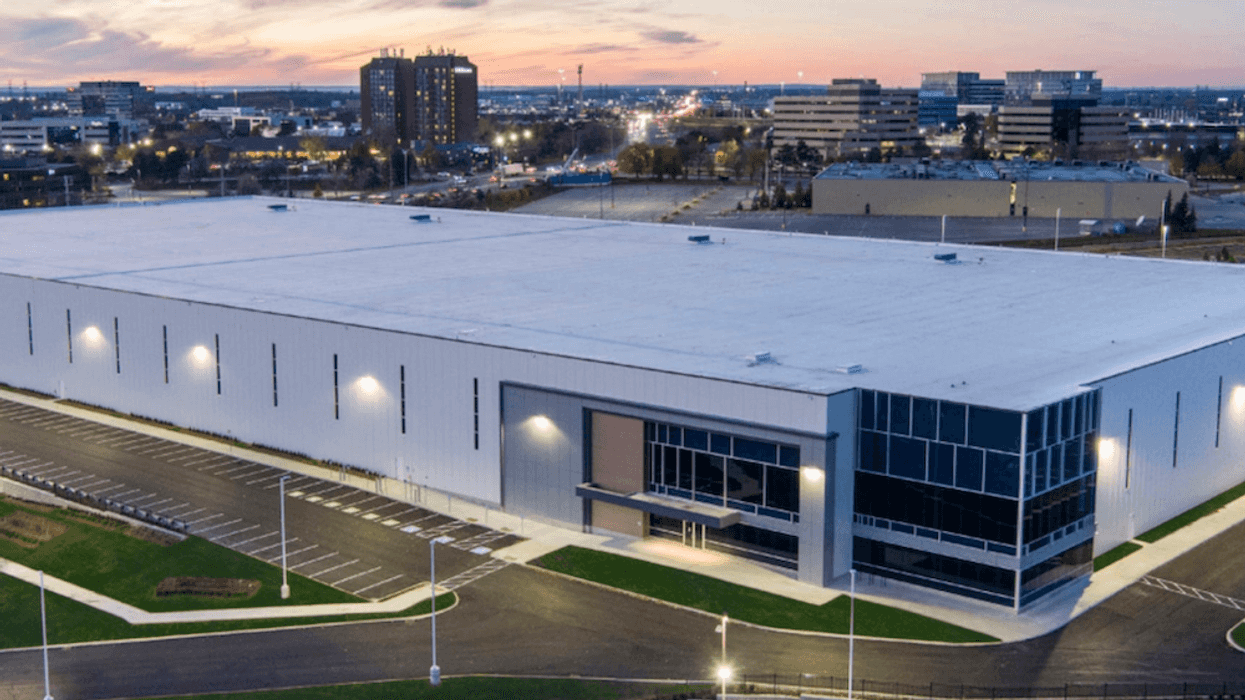
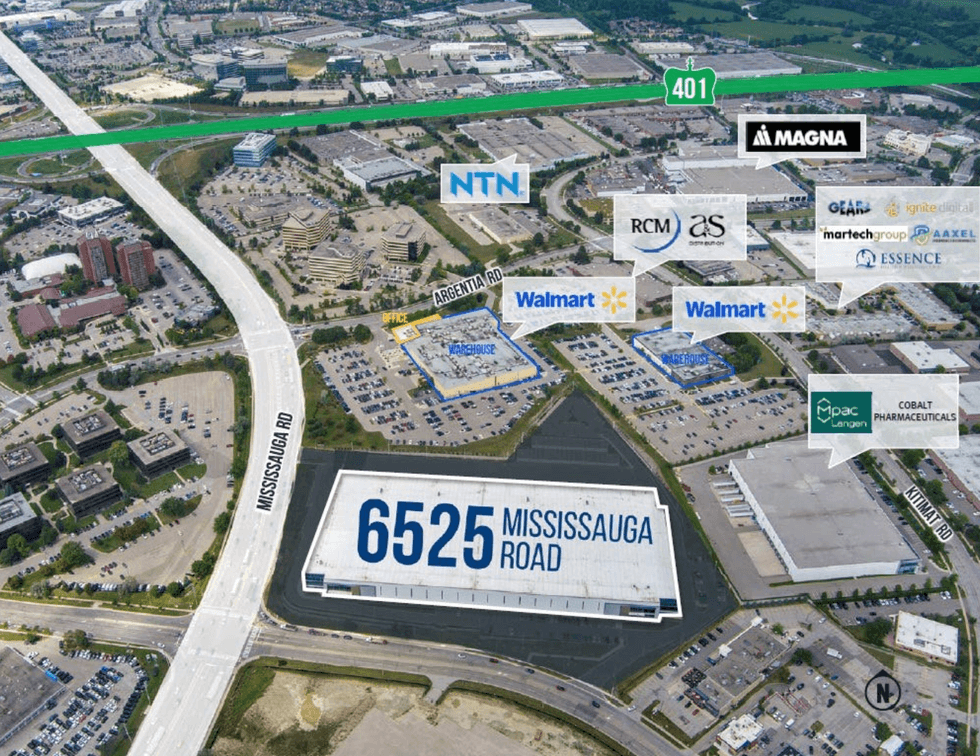 6525 Mississauga Road and its surrounding context. (RBC Capital Markets & CBRE)
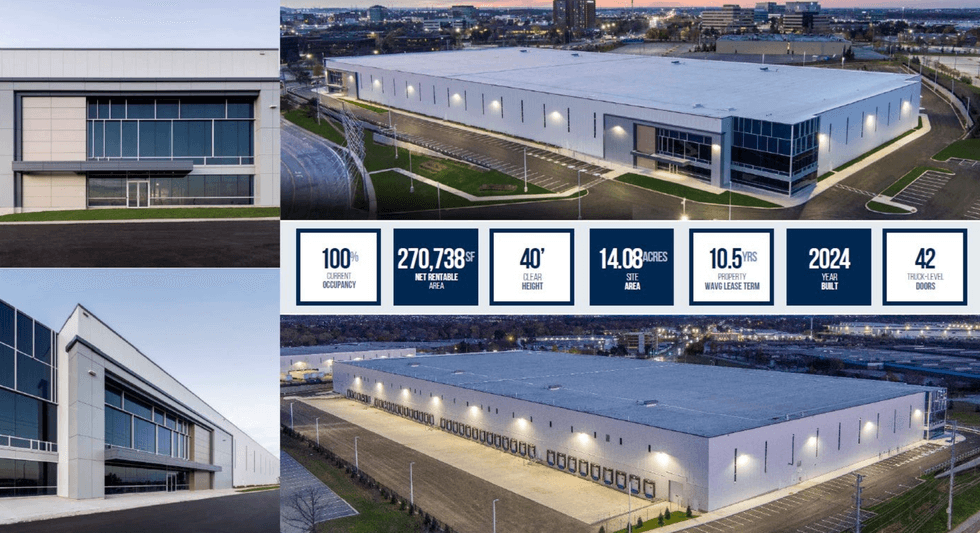 Property details for 6525 Mississauga Road. (RBC Capital Markets & CBRE)
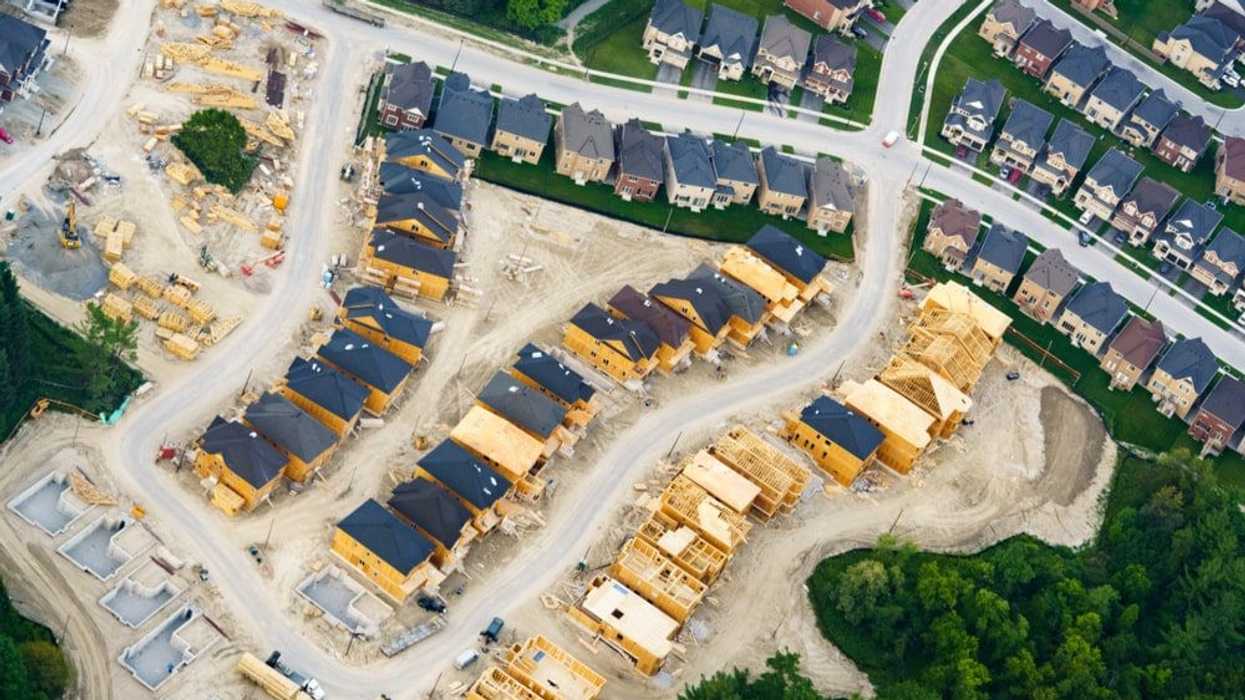
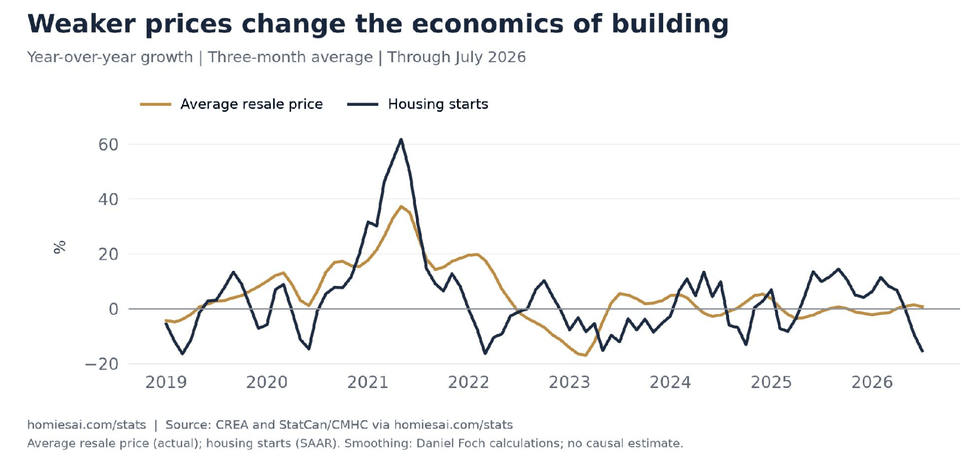 National average resale-price growth and housing-starts growth, smoothed over three months. The comparison illustrates the cycle; it does not establish how much a price change causes construction to change.
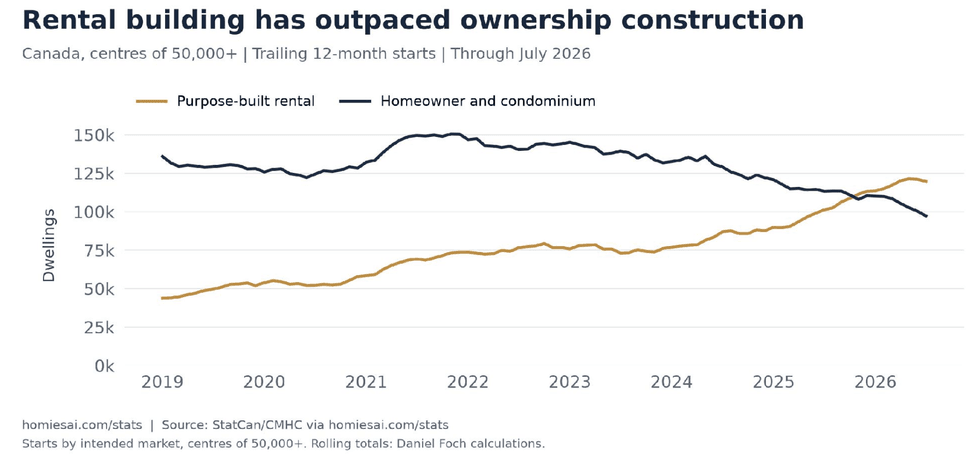 Trailing 12-month starts in centres of 50,000 or more remove the usual monthly seasonality. Ownership combines the homeowner and condominium categories; rental is shown separately.
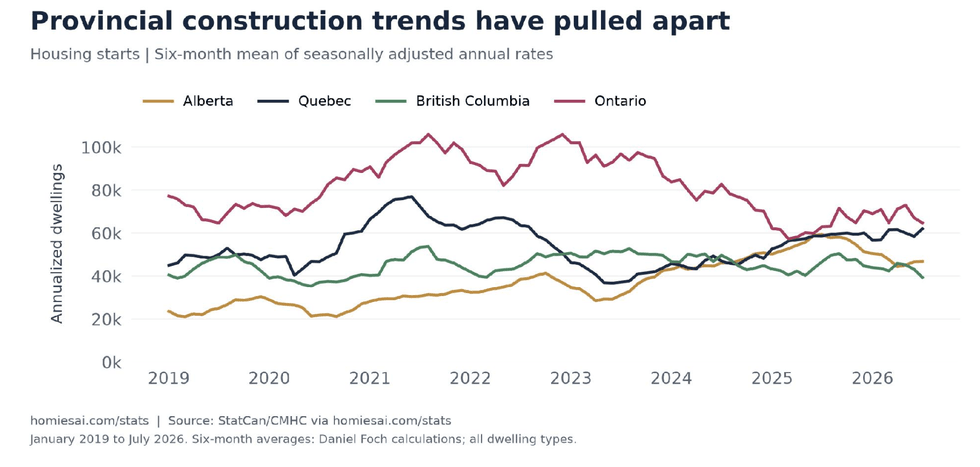 Six-month averages of provincial starts, expressed at annual rates. The smoothing reduces the influence of individual apartment projects.
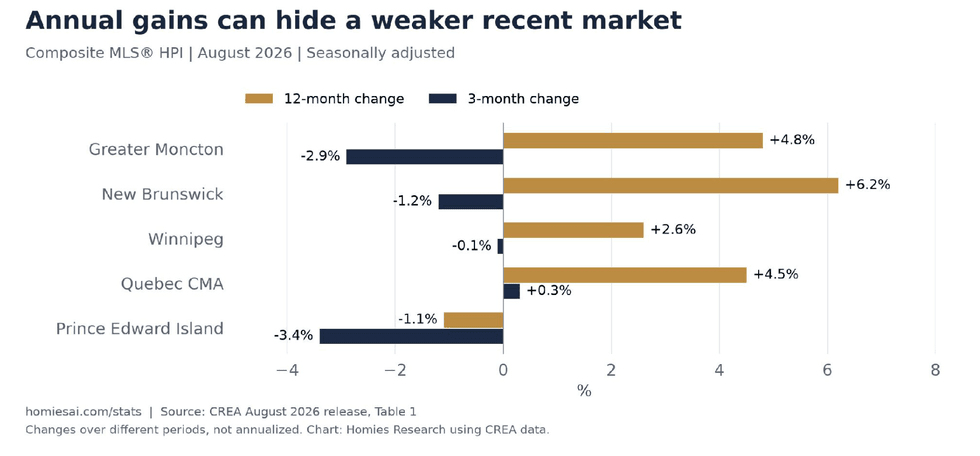 The same August benchmark compared with two different starting points. Three-month changes are not annualized.
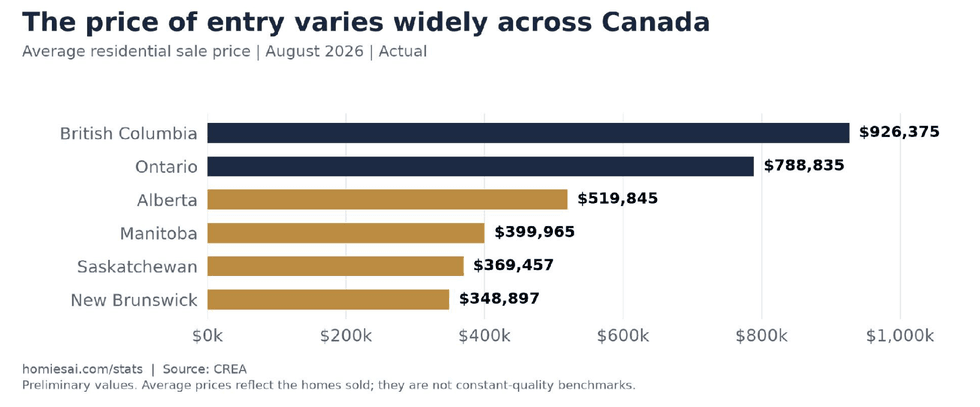 Average sale prices show the difference in purchase costs across markets. They do not measure affordability relative to local incomes or construction costs.
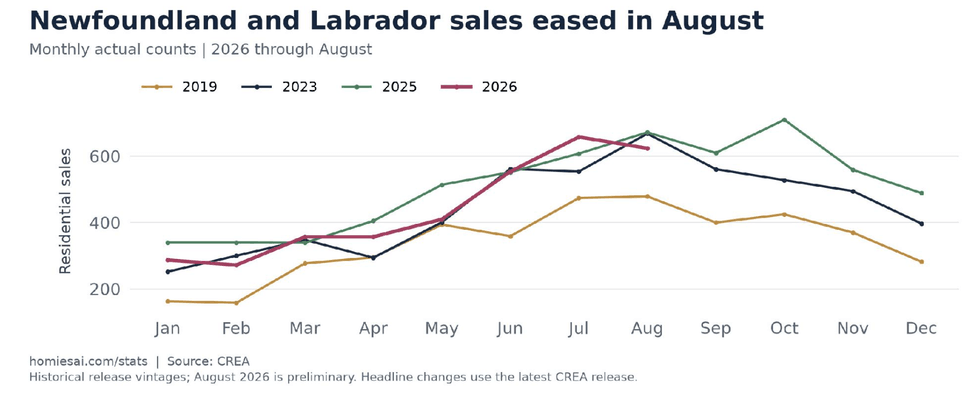 Newfoundland and Labrador remains above its pre-pandemic sales pattern, but August activity was below last year. Historical lines retain their original release vintages.