Default
Learn what default means in Canadian real estate, how it affects mortgages and contracts, and the legal and financial consequences of failing to meet obligations.
May 22, 2025
What is a Default?
Default in real estate refers to the failure to fulfill a legal obligation, such as missing mortgage payments or breaking the terms of a purchase agreement.
Why Defaults Matter in Real Estate
In Canadian real estate, default can occur in multiple contexts:- A mortgage default, where a borrower fails to make payments
- A buyer or seller defaulting on a signed purchase agreement
- Lender-initiated foreclosure or power of sale
- Loss of deposit or legal action by the opposing party
- Negative impact on credit score
Buyers should only enter contracts they can fulfill, and homeowners should seek help early if they struggle to meet mortgage obligations. In many provinces, lenders must follow legal processes before repossessing a home.
Understanding default is key to managing risk and protecting one’s financial and legal interests in real estate transactions.
Example of a Default in Action
A homeowner misses three consecutive mortgage payments and is issued a notice of default, initiating foreclosure proceedings.
Key Takeaways
- Occurs when contractual obligations are not met.
- Can lead to legal action or foreclosure.
- Applies to mortgages or real estate contracts.
- Damages credit and buyer reputation.
- Avoidable with early intervention or legal help.
Related Terms
- Foreclosure
- Power of Sale
- Mortgage Arrears
- Firm Offer
- Buyer Risk
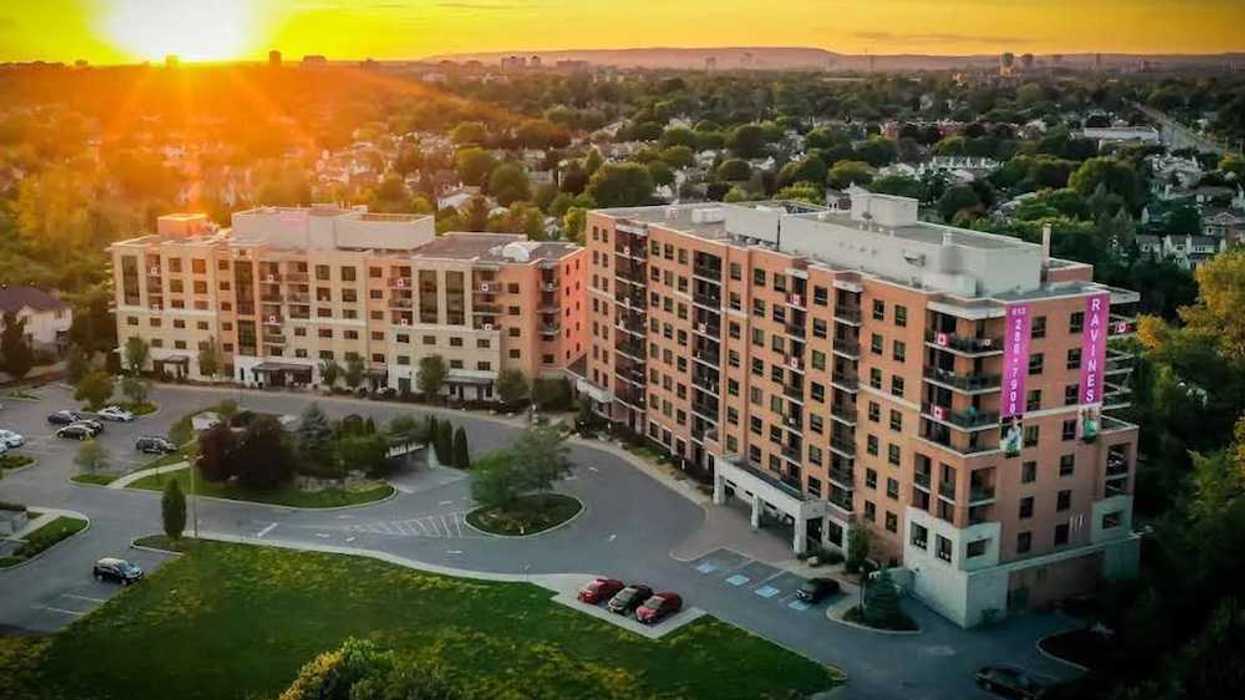
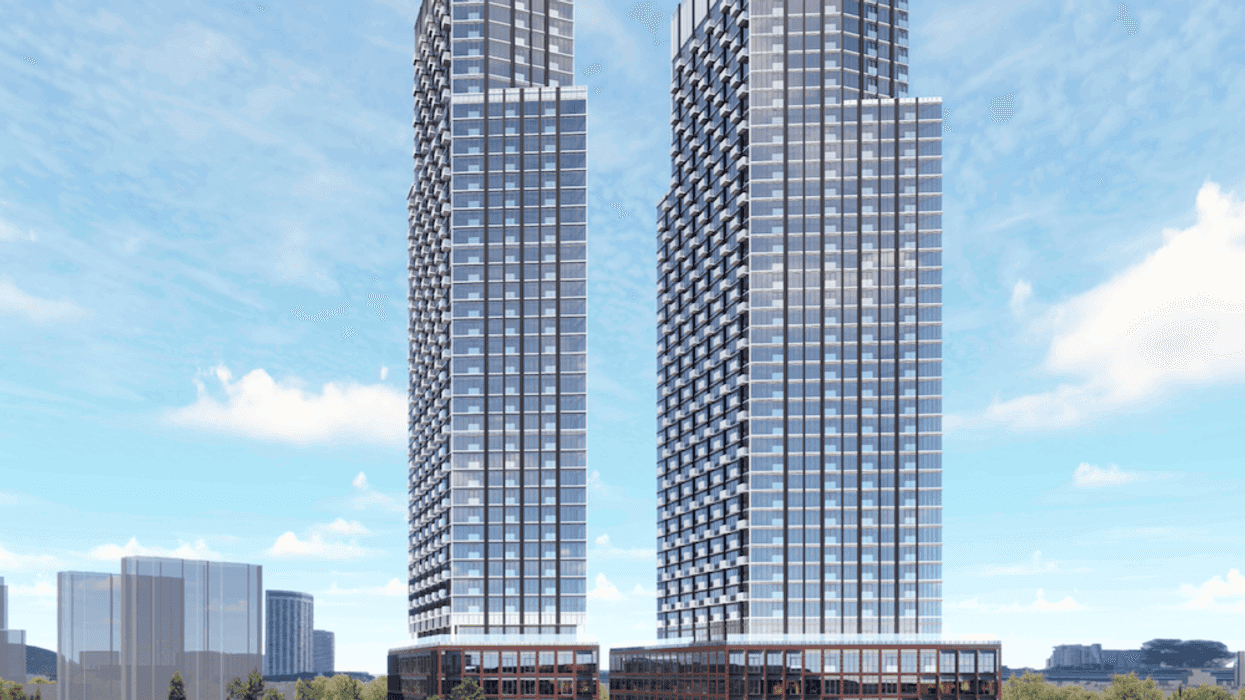
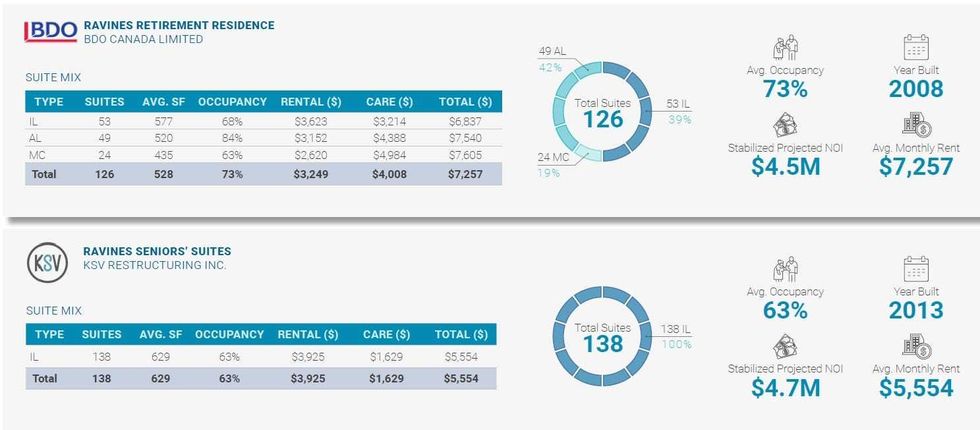 An overview of the two Ravine buildings. (Newmark)
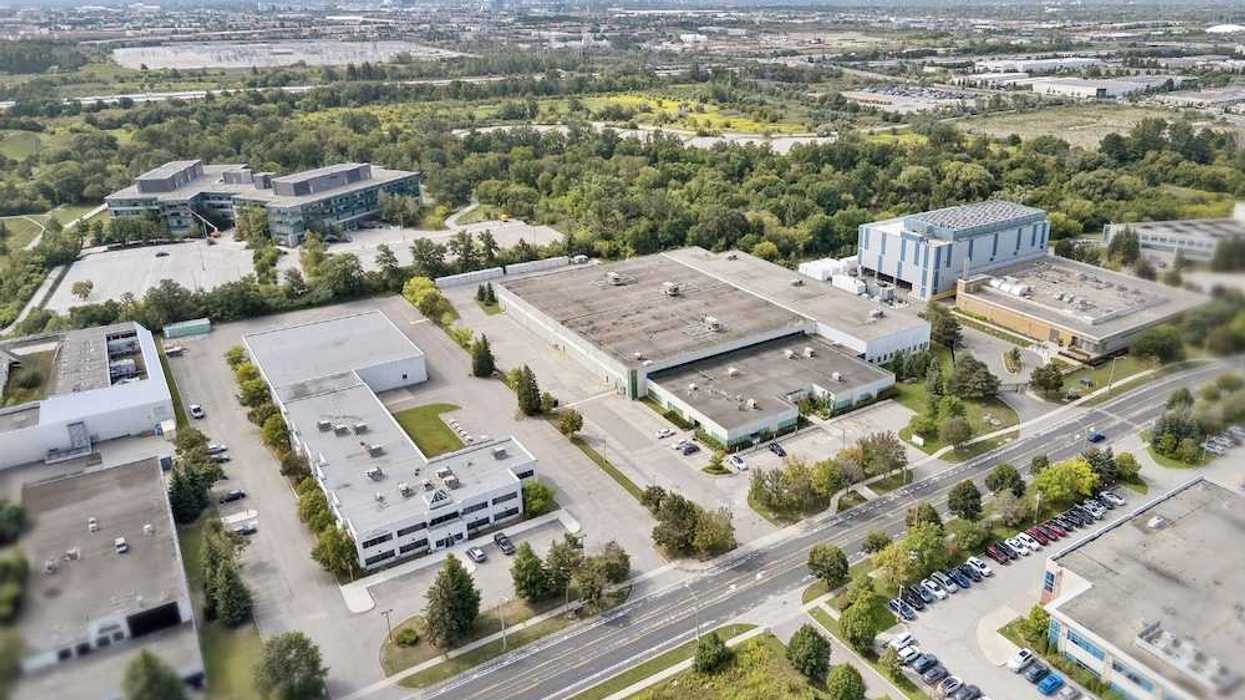
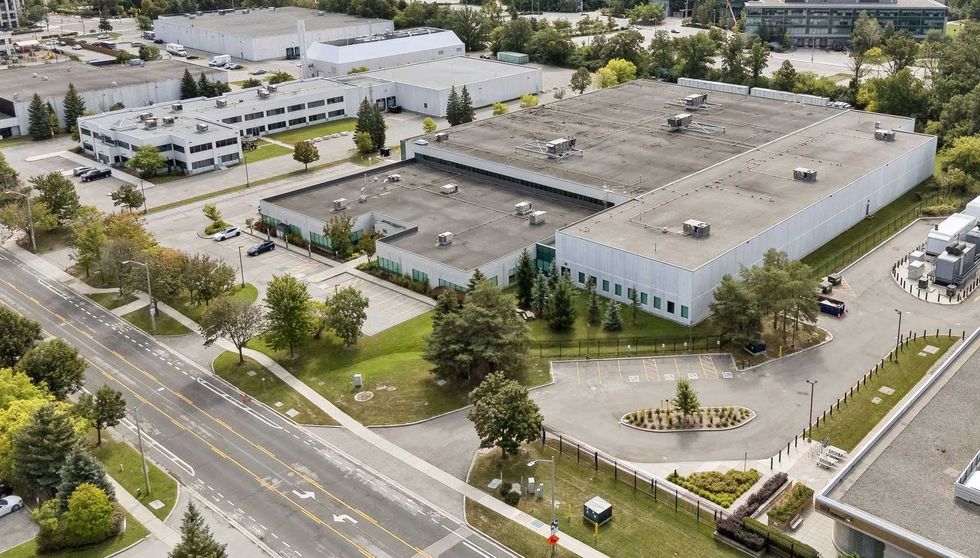 95 Clegg Road in Markham, Ontario. (Colliers)
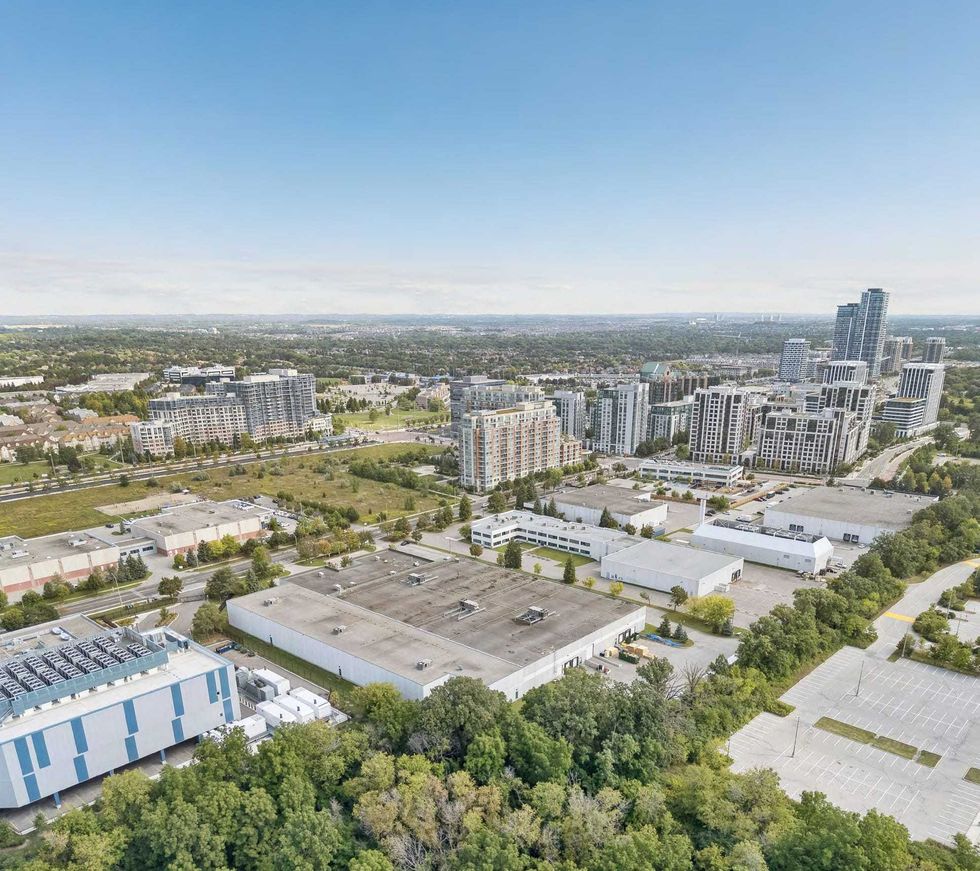 95 Clegg Road (centre) in Markham, Ontario. (Colliers)
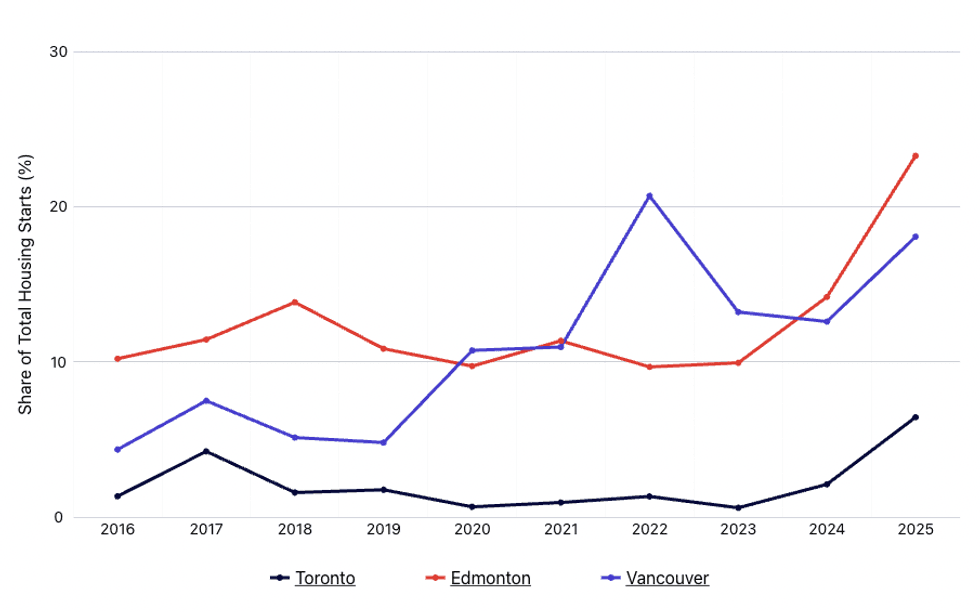 Small-scale infill share of housing starts in Toronto, Vancouver, and Edmonton/CMHC
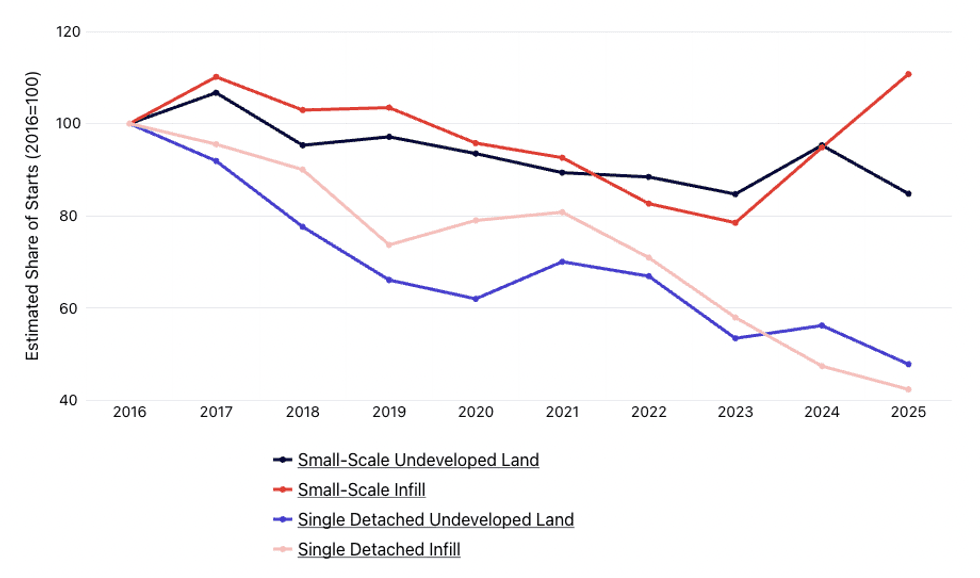 Housing starts for one to eight unit developments/CMHC
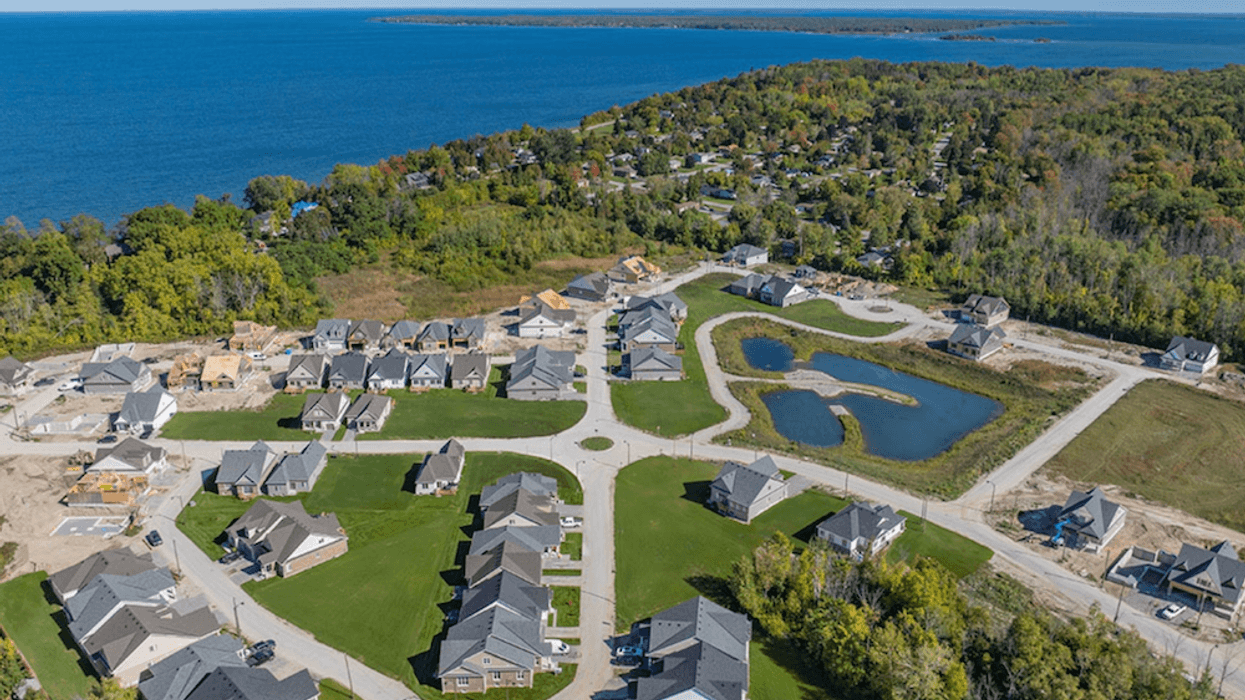
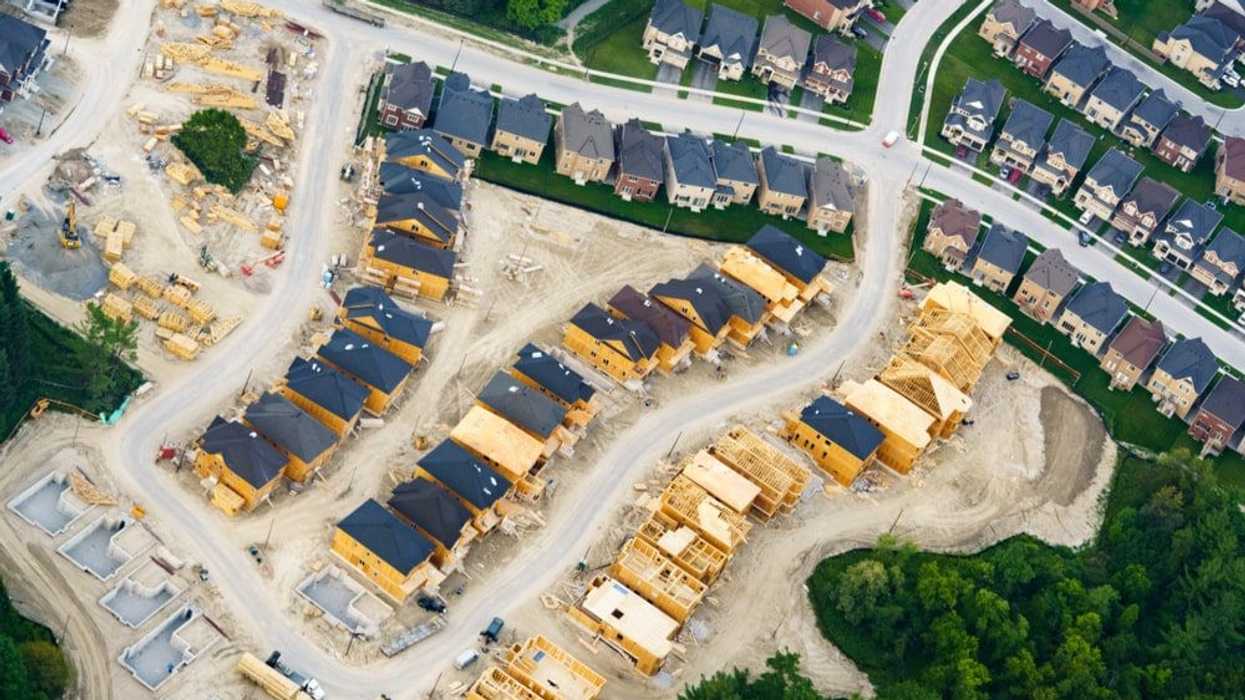
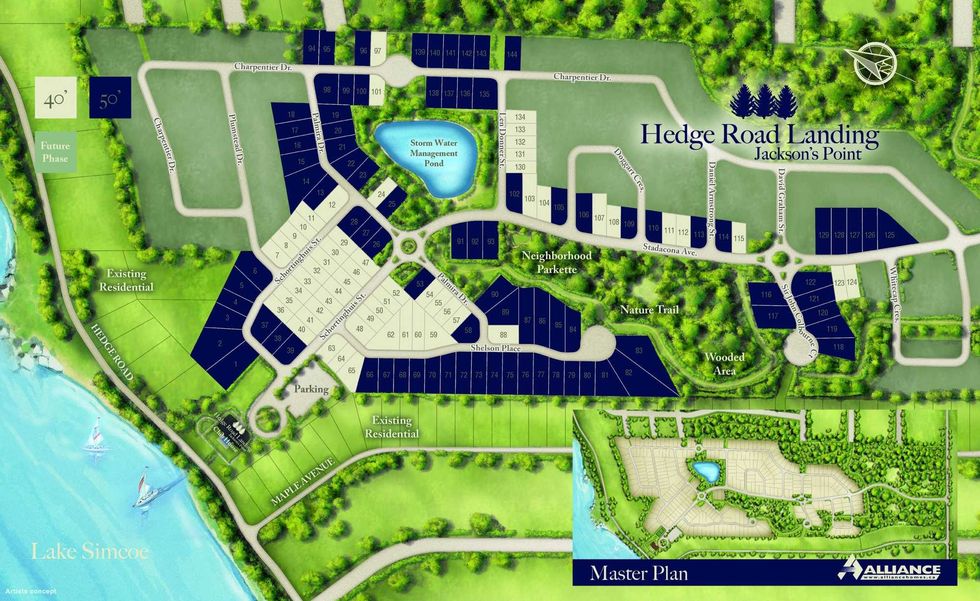 An overview of Hedge Road Landing. (Alliance Homes)
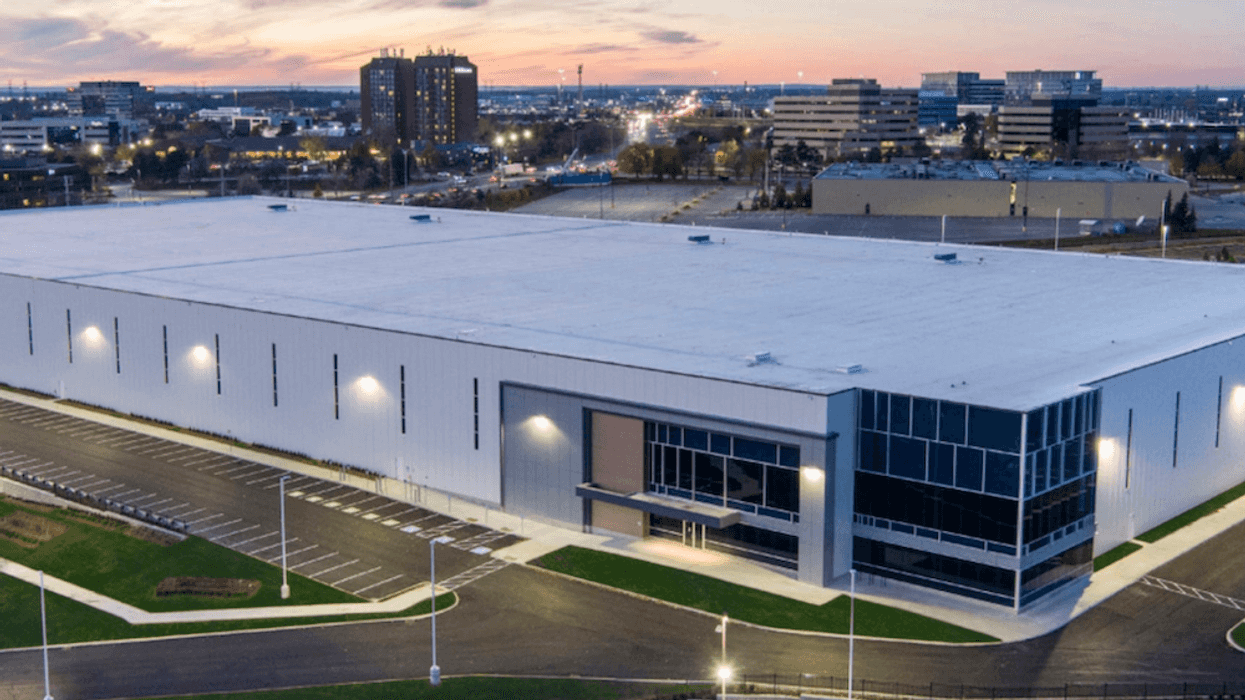
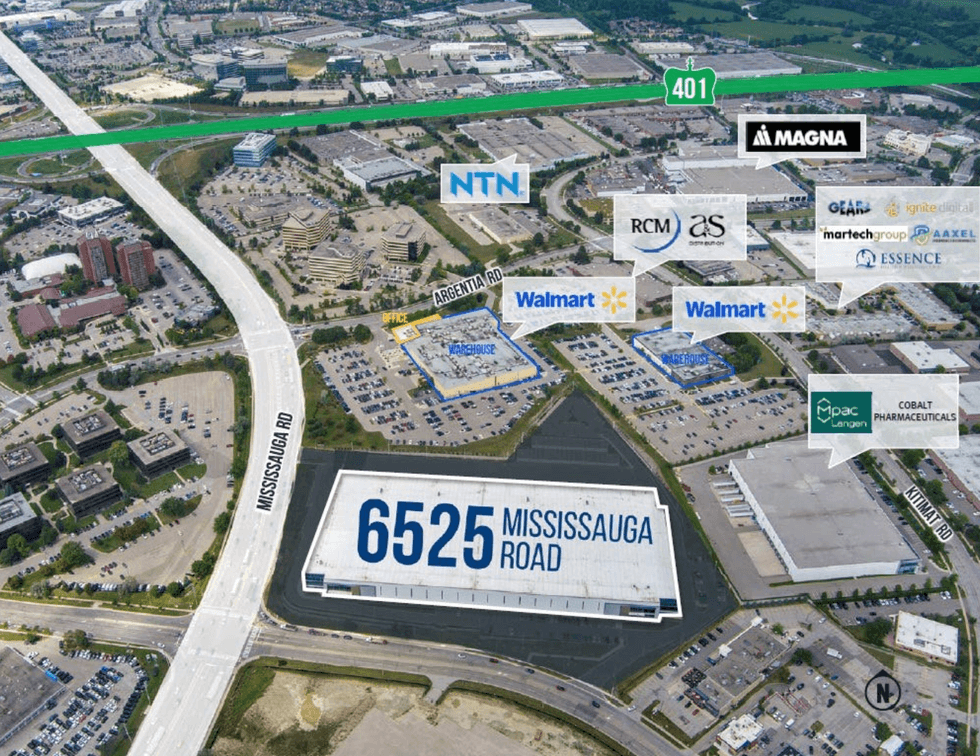 6525 Mississauga Road and its surrounding context. (RBC Capital Markets & CBRE)
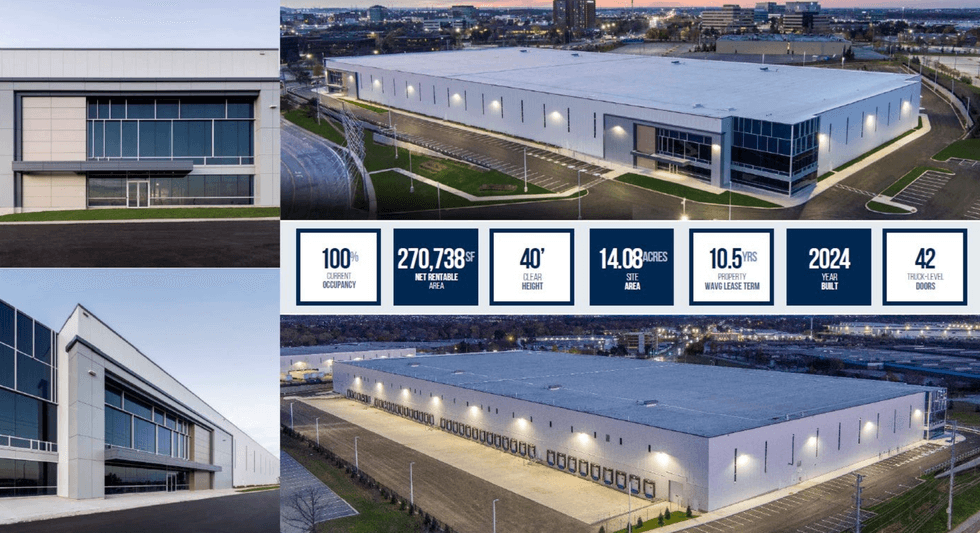 Property details for 6525 Mississauga Road. (RBC Capital Markets & CBRE)
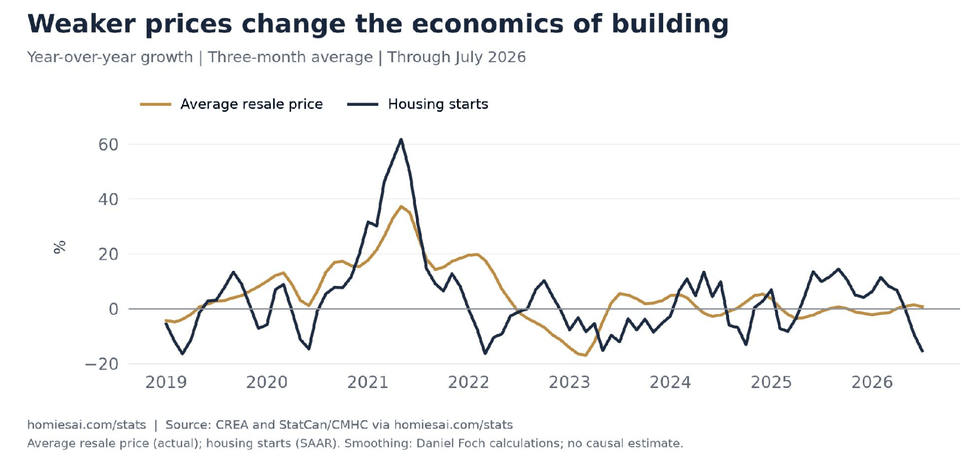 National average resale-price growth and housing-starts growth, smoothed over three months. The comparison illustrates the cycle; it does not establish how much a price change causes construction to change.
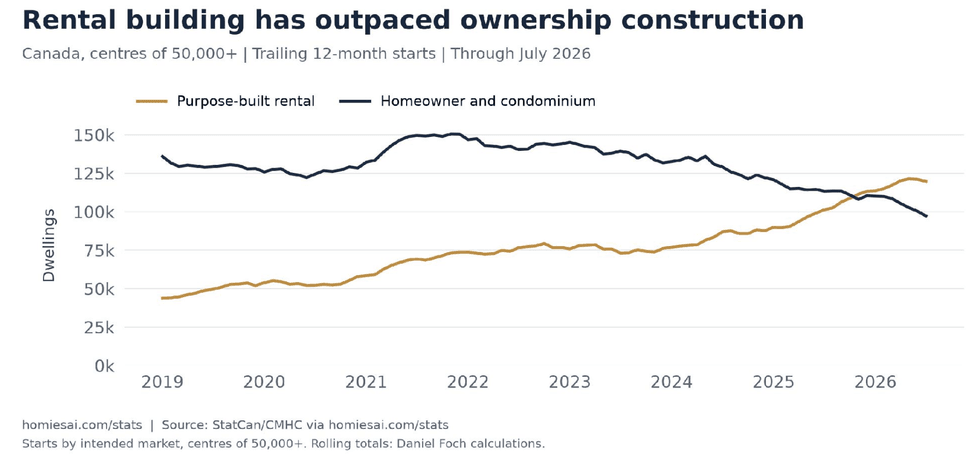 Trailing 12-month starts in centres of 50,000 or more remove the usual monthly seasonality. Ownership combines the homeowner and condominium categories; rental is shown separately.
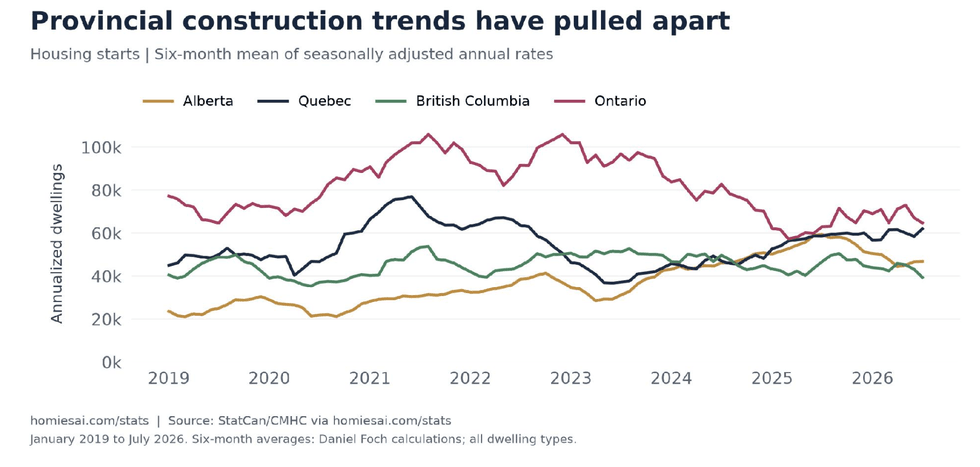 Six-month averages of provincial starts, expressed at annual rates. The smoothing reduces the influence of individual apartment projects.
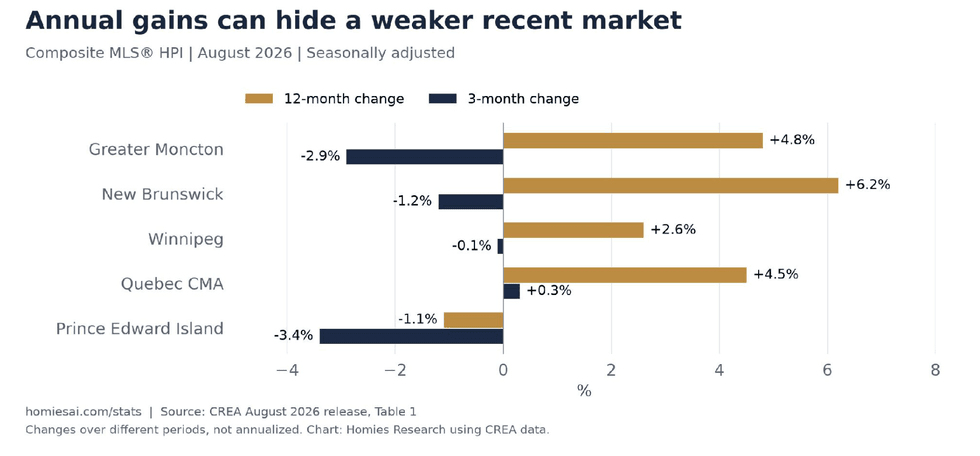 The same August benchmark compared with two different starting points. Three-month changes are not annualized.
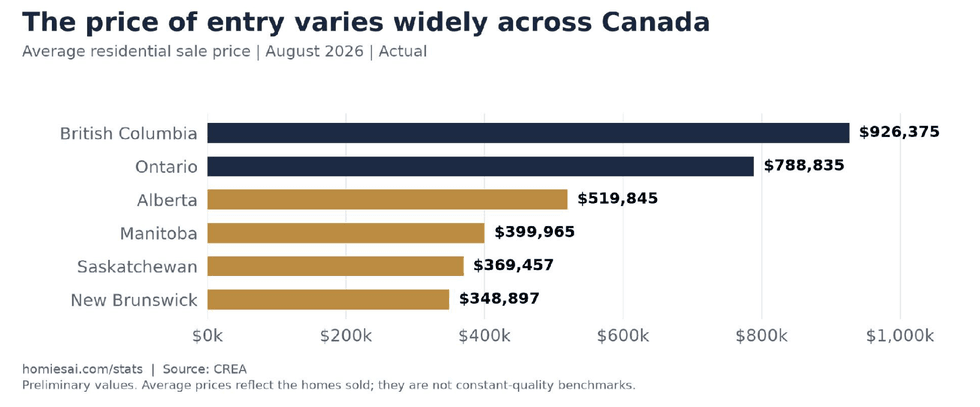 Average sale prices show the difference in purchase costs across markets. They do not measure affordability relative to local incomes or construction costs.
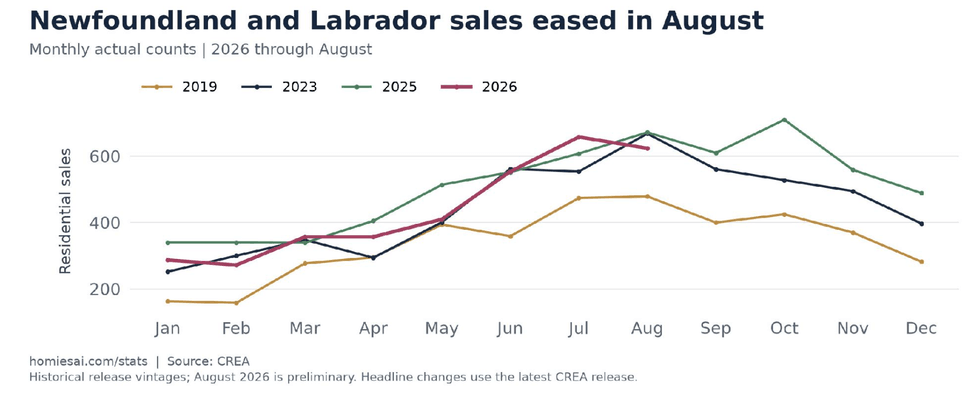 Newfoundland and Labrador remains above its pre-pandemic sales pattern, but August activity was below last year. Historical lines retain their original release vintages.