Interest Adjustment Date
Understand the interest adjustment date in Canadian mortgage financing — how it works, why it matters, and how to plan for the one-time cost.
May 22, 2025
What is the Interest Adjustment Date?
The interest adjustment date is the day your mortgage term officially begins and interest starts accruing, often separate from your closing date.
Why the Interest Adjustment Date Matters in Real Estate
In Canadian mortgage financing, if your closing date doesn't align with your regular payment schedule, lenders charge interest for the days in between. This short period is the 'interest adjustment period.'
Key details:- Occurs between closing date and first payment
- One-time interest-only payment may be required
- Ensures full alignment with lender’s payment cycle
Failing to account for this cost can surprise buyers on closing. Lenders typically explain the interest adjustment amount in the mortgage commitment or funding letter.
Understanding the interest adjustment date helps buyers budget accurately and avoid confusion during their first mortgage payment cycle.
Example of an Interest Adjustment Date
A buyer closes on June 20, but regular payments start July 1. The lender charges an interest adjustment for the 10-day gap.
Key Takeaways
- Aligns mortgage start date with payment schedule.
- Results in one-time interest-only payment.
- Typically occurs shortly after closing.
- Common with fixed payment cycles.
- Important for budgeting and clarity.
Related Terms
- Closing Date
- Mortgage Term
- Payment Schedule
- Interest Rate
- Amortization
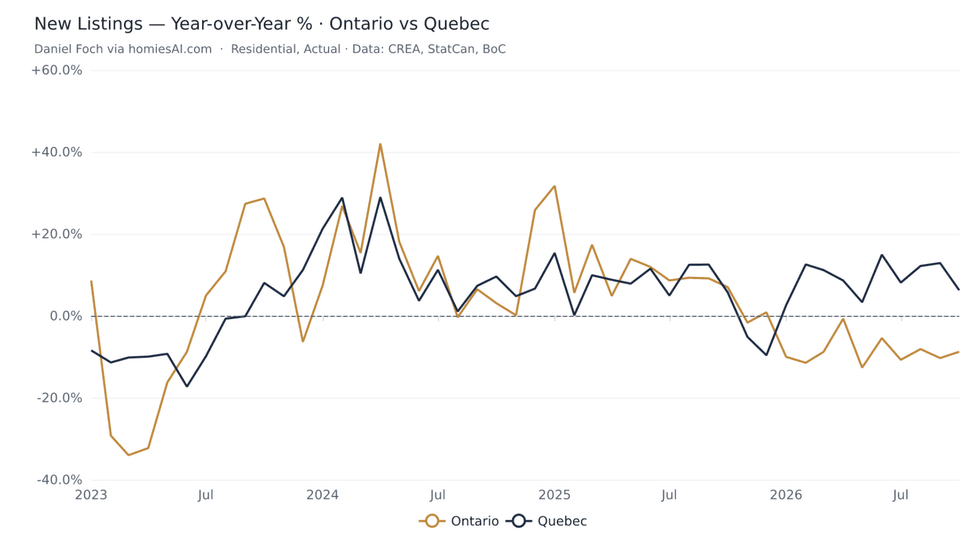 Chart: New listings, year-over-year %, Ontario vs Quebec. Daniel Foch via homiesai.com/stats. Data:
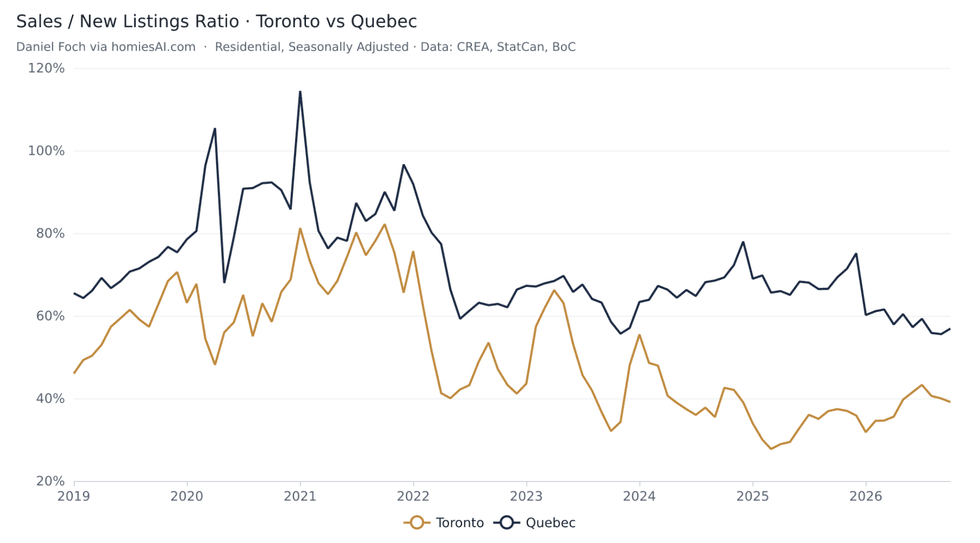 Chart: Sales-to-new-listings ratio, seasonally adjusted. Toronto vs Quebec. Daniel Foch via homiesai.com/stats. Data: CREA.
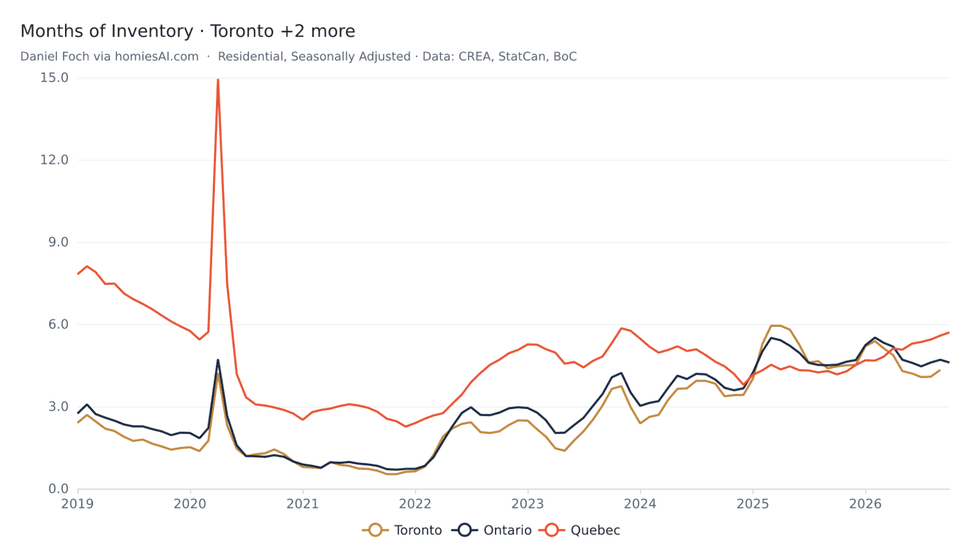 Chart: Months of inventory, seasonally adjusted. Daniel Foch via homiesai.com/stats. Data: CREA.
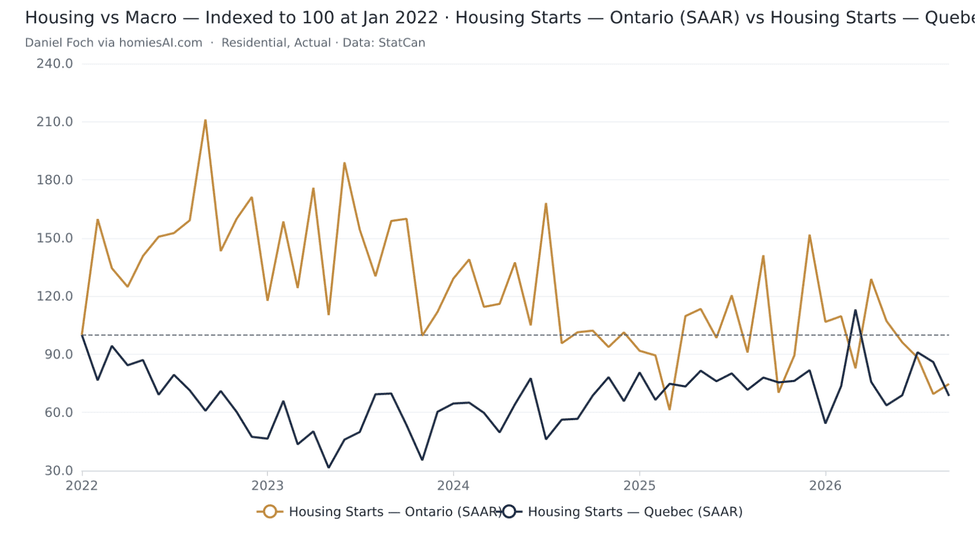 Chart: Housing starts, seasonally adjusted annual rate, Ontario vs Quebec, indexed to January 2022. Daniel Foch via homiesai.com/stats. Data: CMHC via Statistics Canada.
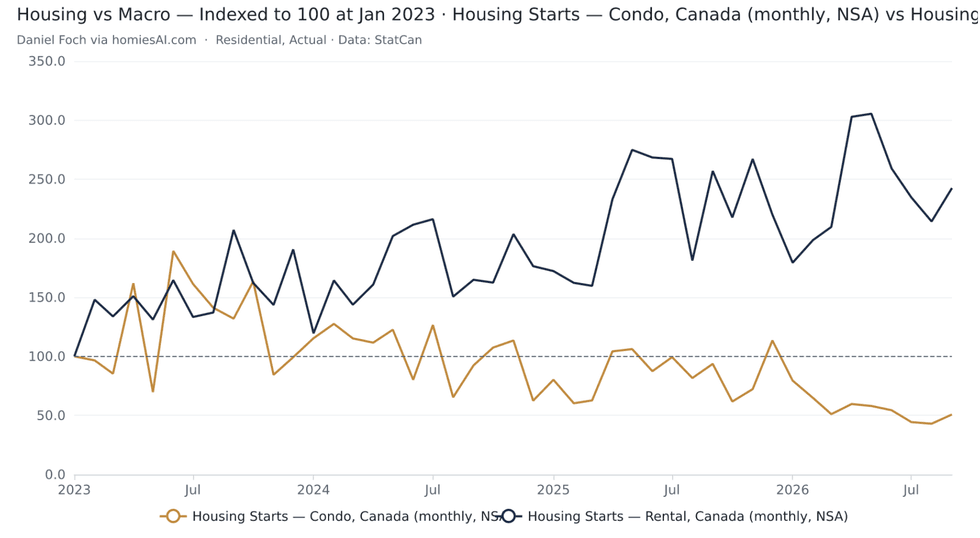 Chart: Condo vs rental housing starts, Canada, indexed to January 2023. Daniel Foch via homiesai.com/stats. Data: CMHC via Statistics Canada.
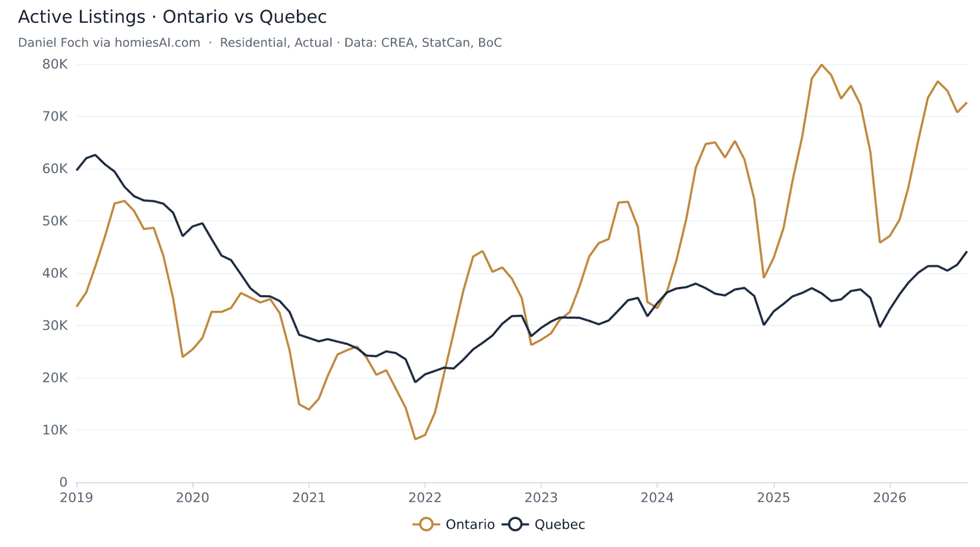 Chart: Active residential listings, Ontario vs Quebec. Daniel Foch via homiesai.com/stats. Data: CREA.



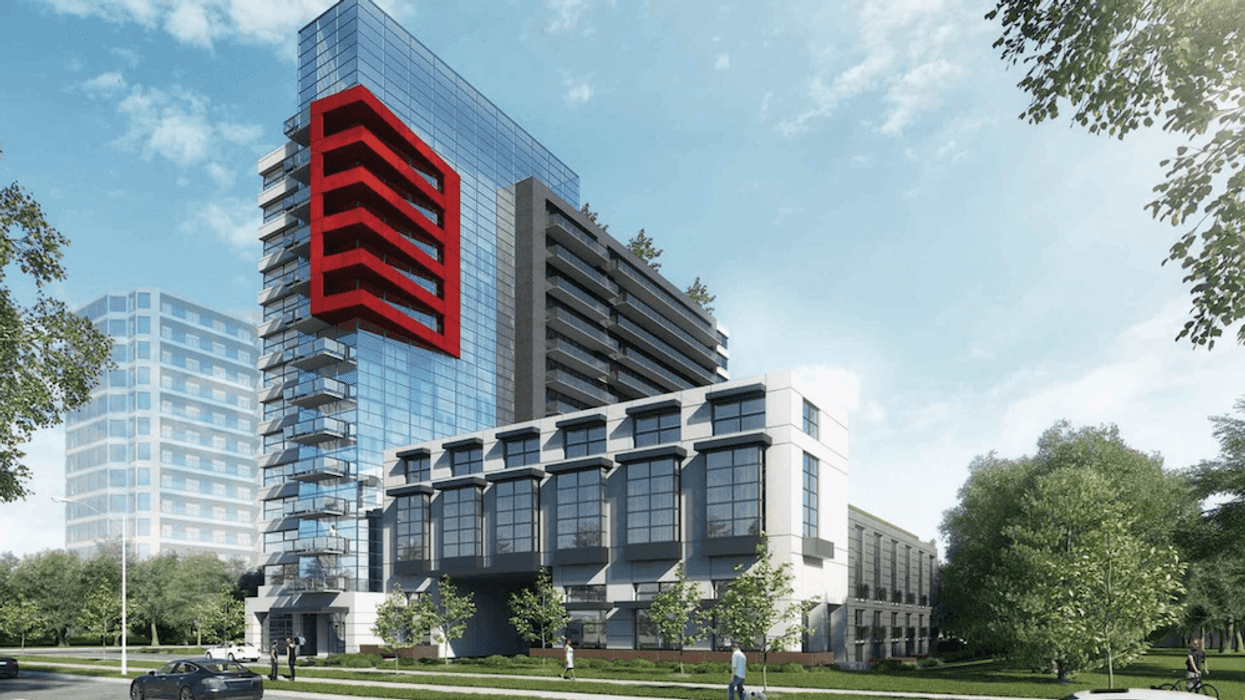
 The Highlight of Mississauga as of March 2026. (Grant Thornton)
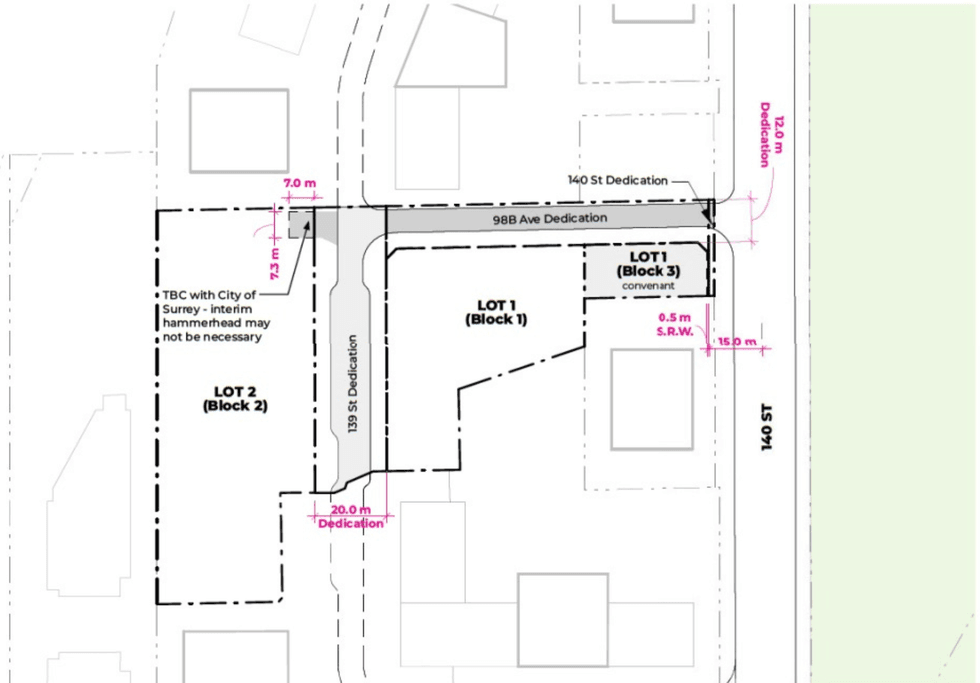 9883 140 Street and the proposed road dedications. (WW+P Architects, Entre Nous Femmes Housing Society)
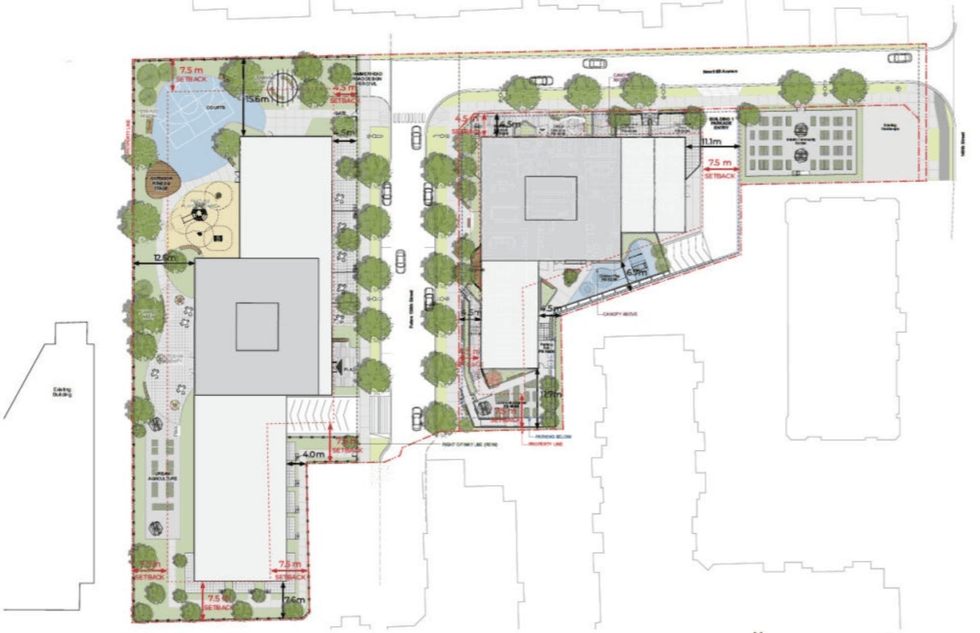 The
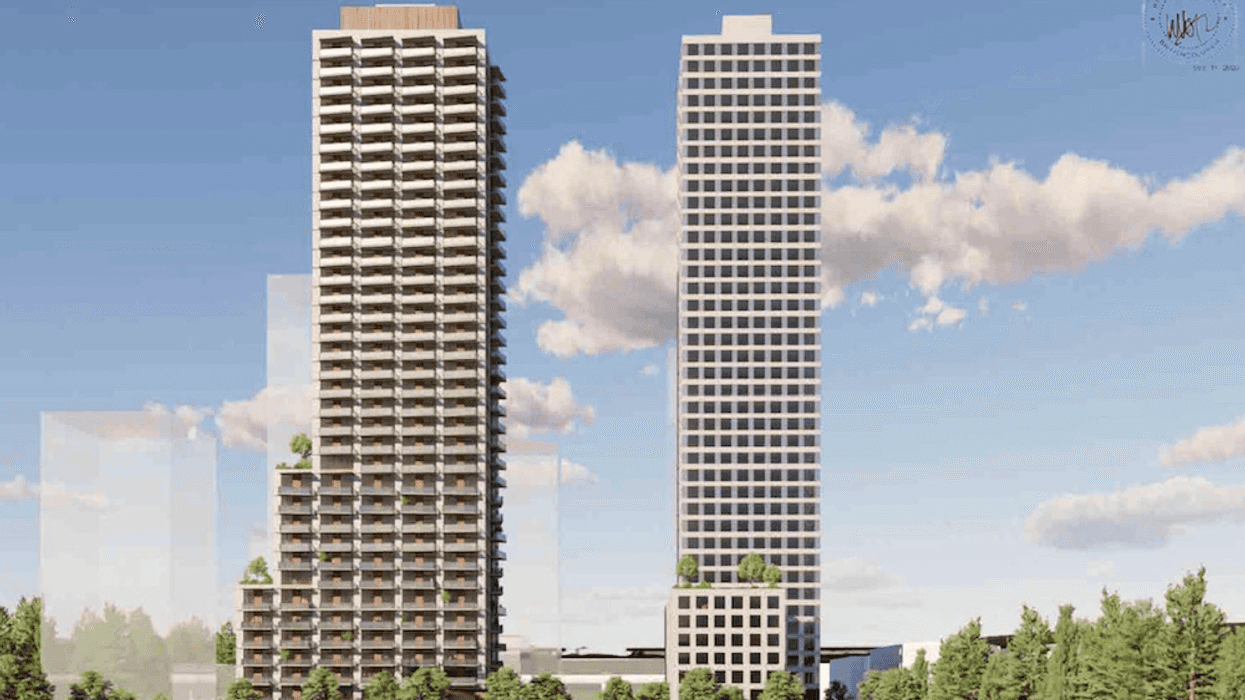
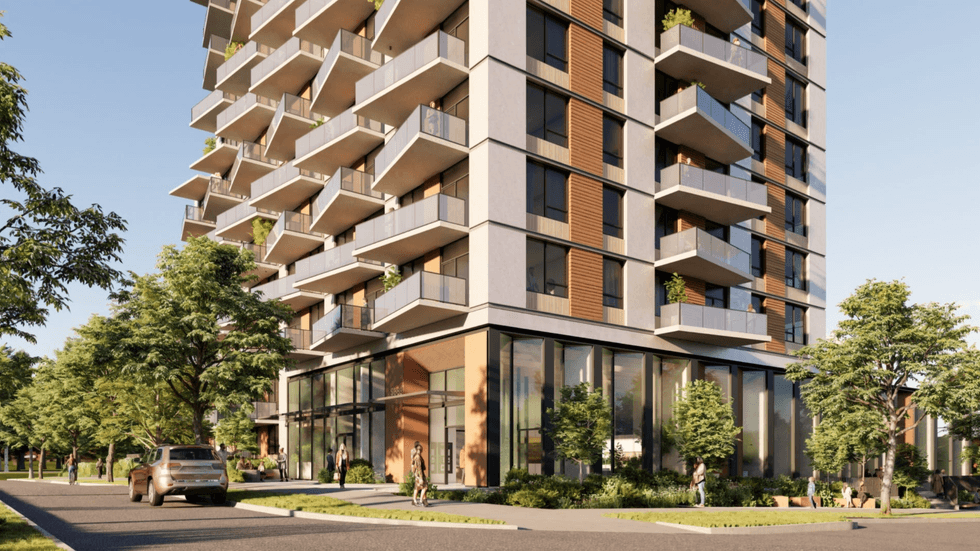 One of the towers proposed for 9883 140 Street. (Entres Nous Femmes Housing Society)

 Canadian respondents were more likely to expect an undersupply of development/redevelopment equity capital (63%) than debt capital (46%) in 2027. These are survey expectations, not measured financing volumes. Source: PwC and ULI, Emerging Trends in Real Estate 2027, pp. 136–137. Original chart.
 Toronto census metropolitan area housing starts fell from 37,718 units in 2024 to 26,087 in 2025, a 30.8% decline (rounded to 31%). Starts measure construction begun, not completed homes. Source: CMHC, as cited in PwC and ULI, Emerging Trends in Real Estate 2027, p. 145. Original chart.




 Illustrative calculation: a $4.5-million value ceiling versus income-based capacity of about $4.25 million at 4%, $3.62 million at 5% and $3.13 million at 6%. Assumes 50-year amortization and 1.15 debt coverage.
 Source: Department of Finance missing-middle backgrounder and Budget 2026 Chapter 3, November 5, 2026. Fiscal-year funding starts are not home-completion dates.